Finance Of America Must Prove Its AI-Driven Lending Momentum After A 51% Stock Collapse
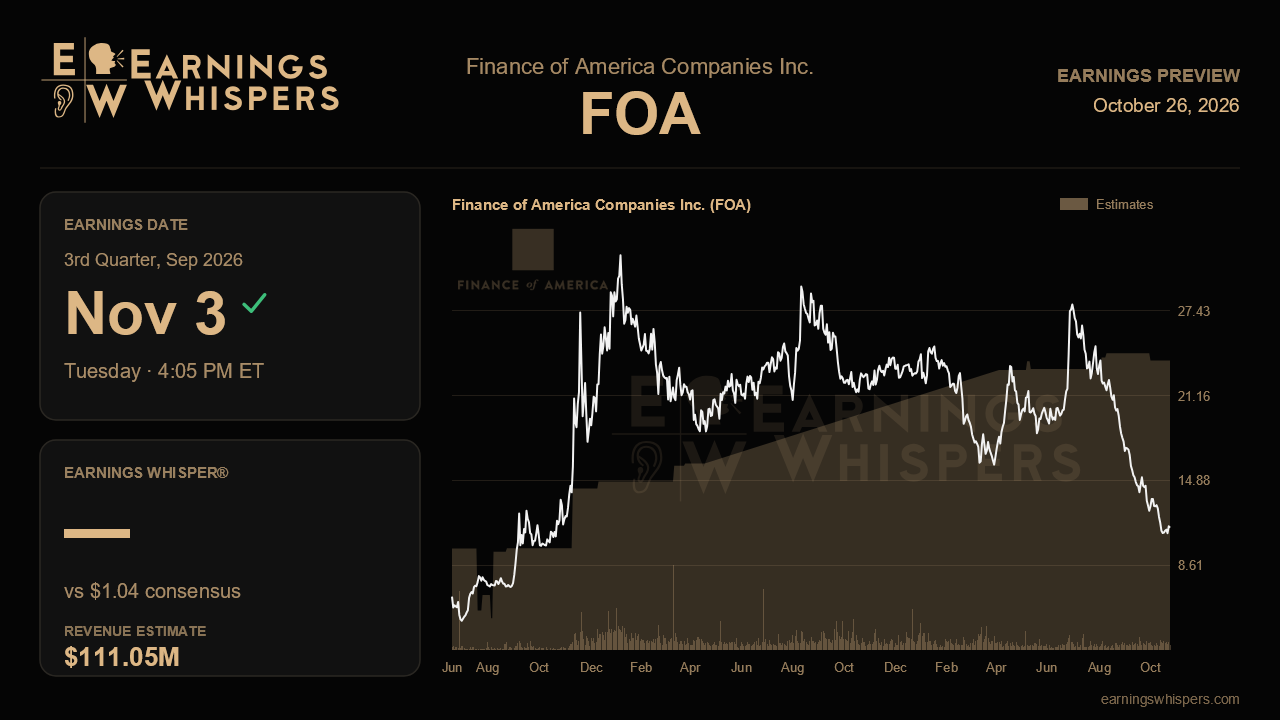
Few lenders head into earnings with a wider gap between what management says and what the market is pricing. Last quarter Finance of America described a business gaining conviction, with loan submissions topping $1 billion, call center productivity up sharply and adjusted earnings compounding. Since then the stock has lost roughly half its value, sliding to $11.38 against a 2.1% dip in the S&P 500. When the company reports third-quarter results after the close on November 3, the question is simple. Is the operating story still intact, or did the market see something the conference call did not?
The Street expects earnings of $1.04 per share on revenue of $111.1 million. That revenue figure would be up 37.4% from a year ago and a big step up from the $62.5 million reported last quarter, a swing that likely reflects how heavily this business depends on fair value accounting and rate-sensitive gains. Earnings, by contrast, are expected to fall about 22% from the $1.33 earned in the year-ago quarter, though $1.04 would still mark a solid sequential gain over the prior quarter's adjusted $0.84. Management reaffirmed full-year adjusted EPS guidance of $4.50 to $5.00 last quarter after raising it in the first quarter. With $1.94 banked in the first half, the company needs roughly $2.56 to $3.06 in the back half. A $1.04 third quarter would leave a heavy fourth-quarter lift of roughly $1.50 to $2.00 to stay inside the range, so a merely in-line print may not settle the debate over whether guidance is achievable.
The operating metrics matter more than the headline number. Management's pitch shifted last quarter from filling the top of the funnel to converting the pipeline already in hand, citing a 33% jump in retail funded loans and roughly 30% more funded loans per call center loan officer, all on stable headcount through its AI platform. Validation would be another quarter of rising submissions beyond $1 billion, funded volume climbing from the $730 million posted in the second quarter, and productivity gains that hold rather than fade. Funded volume guidance of $2.8 billion to $3.1 billion was held rather than raised despite the momentum, so a move toward the upper half of that range would be a meaningful signal. The closed Onity and PHH transaction, expected to deliver a mid-teens yield in the second half, should also begin showing up in results.
The risks flagged last quarter are the obvious swing factors. Rates rose in July after the quarter ended, and management signaled near-term fair value markdown pressure, which could again push GAAP results into the red after an $84 million negative adjustment drove a $29 million loss last quarter. Gain-on-sale margins on proprietary products were already volatile. There is a potential offset: part of last quarter's hit came from a non-cash mark on convertible notes tied to the rising share price, and the stock's steep decline could work in the opposite direction. Tangible equity per share, which slipped from around $15, deserves close attention as a measure of whether marks are eroding real value.
Sentiment has drifted from mildly bullish to essentially neutral, a modest shift that understates how badly the stock has been punished. Shares sit far below the 200-day moving average near $19.73 and just above the post-report low of $10.63, a sharp break from the prior quarter's $18 to $30 range. Capital return is also on the calendar, since buybacks were deferred until the $150 million senior notes are retired this month.
Ultimately, this report must show that conversion gains and origination growth are translating into earnings power strong enough to keep the full-year target credible. If volume and productivity keep climbing and management reaffirms guidance, the selloff starts to look excessive. If guidance softens or marks overwhelm the operating progress, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Sep-18 | |
| Aug-18 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-27 | |
| Jul-21 | |
| Jul-09 | |
| Jul-07 | |
| Jul-01 | |
| Jun-23 | |
| May-05 | |
| May-04 |
