Finance Of America's Volume Engine Keeps Running, But A Rate-Driven Margin Squeeze Sinks Q3 Earnings And Its 2026 Guidance
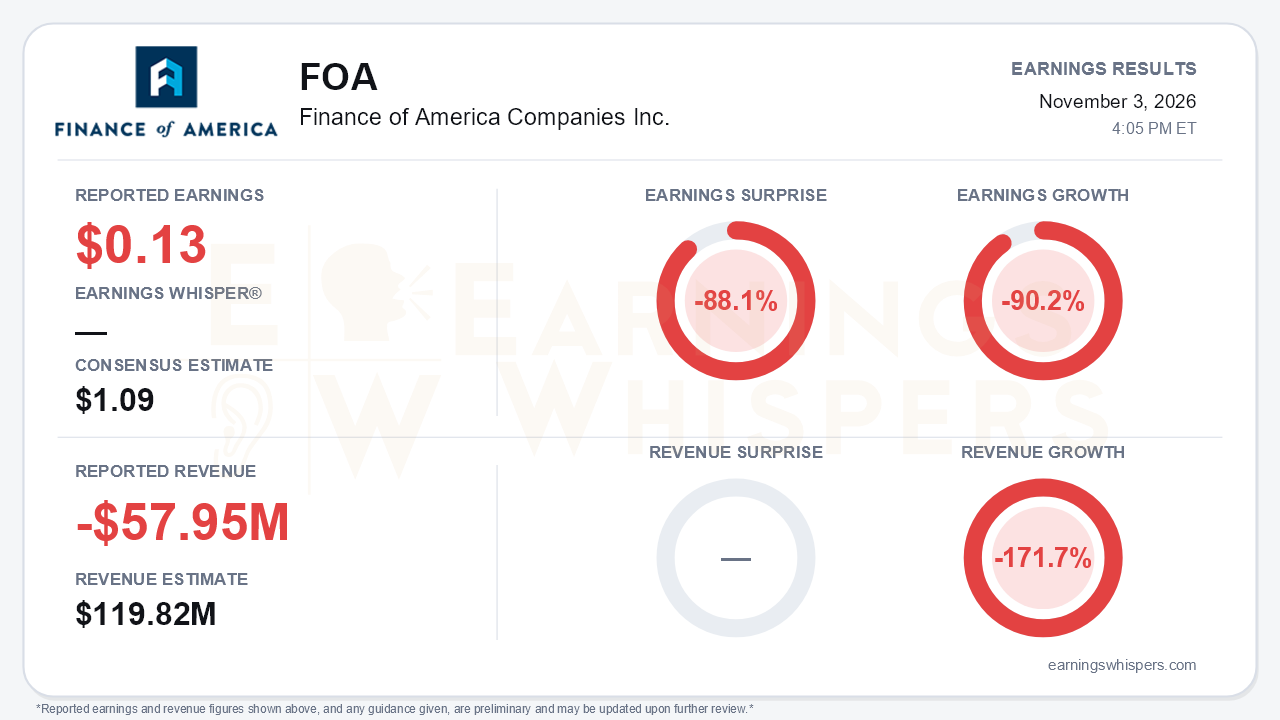
Finance of America (NYSE: FOA) delivered a quarter in which demand and profitability moved in opposite directions. Earnings Whispers' normalized EPS of $0.13 fell 88.1% short of the $1.09 consensus and was down 90.2% from a year ago. GAAP revenue was negative $57.95 million, against a $119.82 million consensus, a 148.4% miss and a 171.7% year-over-year decline. The company's own adjusted EPS of $0.28 differs from the normalized figure, but it tells the same story: down from $0.84 in Q2 and $1.10 in Q1. On a GAAP basis, the reverse-mortgage lender lost $110 million, or $5.24 per basic share. Meanwhile, funded volume rose 24% to $748 million. That is the central tension. The origination machine is growing, but rising rates are crushing what each loan earns, and management withdrew its full-year earnings target as a result.
The quality of the quarter deserves scrutiny on two levels. The GAAP loss was driven largely by non-cash items: $125 million of fair value adjustments, including roughly $142 million of negative marks from market inputs and model assumptions on retained securitization interests. Management leaned hard on the "non-cash" framing. Investors should not dismiss these marks so easily, because they hit capital directly. Total equity fell from $407 million to $307 million in one quarter. Book value per common share dropped to $28.08 from $33.20, and tangible equity per share fell to $8.29 from $13.31. The core business also weakened. In Retirement Solutions, revenue slipped to $67 million despite the volume growth, and segment pre-tax income fell to $3 million from $10 million in Q2 and $17 million a year earlier. Company-wide adjusted EBITDA fell 51% sequentially to $17 million.
The call explained the mechanism. A 75-basis-point-plus jump in the 10-year yield during the quarter compressed the Retirement Solutions revenue margin to 9.0%. That compares with 11.3% a year ago and a historical average of about 10.7%. Demand, by contrast, looks robust:
- Submissions rose 20% year over year.
- Wholesale submissions reached a seven-quarter high.
- Retail funded volume jumped 54% to $303 million.
- Production per loan officer climbed more than 40% to $1.2 million a month on flat headcount.
- HomeSafe second-lien volume grew 63%.
The problem is pricing, not customers. Management repriced loan-to-value ratios and rates in October to restore historical margins in the first half of 2027. However, a 60-90 day pipeline lag means the fourth quarter will look much like the third.
The guidance reset was the sharpest blow. The FY2026 adjusted EPS target of $4.50-$5.00 had been raised in Q1 and reaffirmed in Q2; it is now gone, with Q4 expected near Q3's $0.28. Full-year volume is now expected at the low end of the $2.8-$3.1 billion range. Management reframed earnings power as a $4-$5 annualized run-rate, but only by the second half of 2027. Even that outlook will be partly offset by lower Portfolio Management earnings as higher discount rates weigh on the book. Balance-sheet plans also slipped. Rather than retiring all $150 million of senior notes in November as previously targeted, FOA will repay $60 million and extend roughly $90 million to November 2027. Cash did rise $33 million to $118 million, and management flagged buybacks and dividends once the notes are retired. Still, the tone shifted noticeably from earlier "inflection" and "conviction" language toward a defensive emphasis on the pressure being "temporary."
The market had largely anticipated trouble before the release. Shares fell 52.8% from the $23.18 open after the August report to $10.95. They sit 43.4% below the 200-day moving average and just 9.1% above a 52-week low of $10.04 set on October 30. The stock now trades well below stated book value, though much closer to tangible equity per share. Investor sentiment, measured just before the report, improved modestly from 0.02 to 0.11. That suggests some investors saw the selloff as overdone, but it is hardly a strong vote of confidence. Price and AVWAP readings remain negative, consistent with a stock still under distribution.
Bulls can point to accelerating volume, an initial FY2027 volume outlook of $3.1-$3.4 billion, and identifiable catalysts:
- margin repricing already in place;
- a HomeSafe second line-of-credit launch;
- HECM MSR financing expected in the first half of 2027.
Bears have legitimate ammunition as well. Guidance credibility has been damaged, and capital has eroded sharply. Further rate moves could require yet another round of repricing.
The bottom line is that FOA's demand story survived the quarter intact, but its earnings story did not. Normalization now depends on rate stability and on whether the October repricing restores margins toward 10.7% without choking off volume. The steep pre-report decline means expectations are already low. However, a recovery the company has pushed out to the second half of 2027 leaves investors waiting several quarters for proof.
Read our earnings preview for Finance of America Companies Inc.: https://www.earningswhispers.com/article/FOA/21573
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Sep-18 | |
| Aug-18 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-27 | |
| Jul-21 | |
| Jul-09 | |
| Jul-07 | |
| Jul-01 | |
| Jun-23 |
