GXO's Record Signings Face A Test: Can Third-Quarter Revenue Ramp Before Investor Day?
GXO Logistics heads into its third-quarter report with an unusual imbalance between what it has signed and what it has shown. Last quarter the contract logistics giant posted its strongest commercial period in three years, with $410 million of new business wins and more than $1 billion of incremental 2026 revenue already secured. Yet reported organic growth slowed to 3.4% from 4.1% in the first quarter, and management only tightened its full-year outlook rather than raising it. The results, due after the close on November 3, are the first chance to see whether those record wins are turning into revenue on schedule, and they arrive just two weeks before a November 16 Investor Day where the company has promised to lay out its margin story.
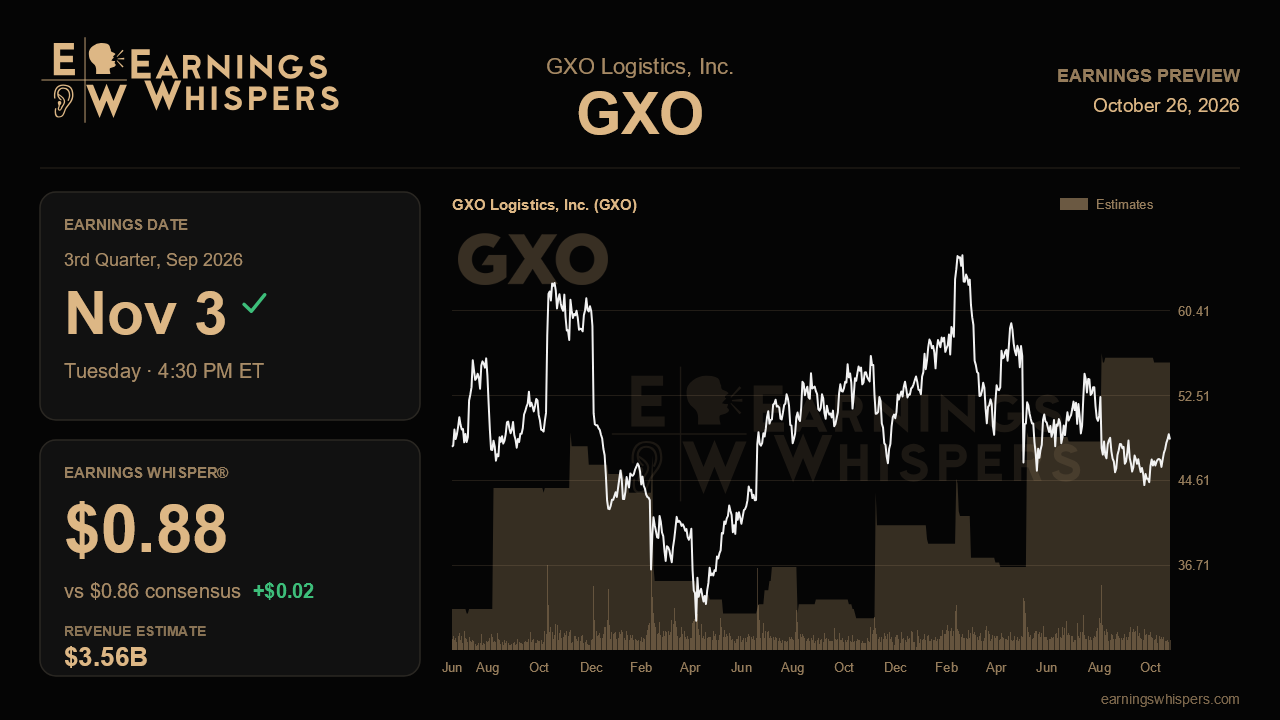
The Street is looking for earnings of $0.86 a share on revenue of $3.56 billion, up roughly 9% and 5% respectively from a year ago. That is modest but respectable growth, and a clear step up from the $0.59 GXO earned last quarter on $3.44 billion of sales. The Earnings Whisper sits at $0.88, only a couple of cents above consensus, which suggests the bar is slightly elevated rather than demanding. On the full year, consensus of $3.07 a share sits comfortably inside management's $2.95 to $3.15 range and just above its midpoint. Revenue is a different matter: the Street's $14.01 billion annual estimate is above the company's $13.71 billion to $13.837 billion outlook, so any sign that ramp timing is slipping could force analysts to trim top-line numbers.
The central operating question is organic growth. Management's 4% to 5% full-year target requires a back-half acceleration driven by new contract startups, and the company itself flagged that the timing of launches and exits can push revenue around. A third-quarter organic print that moves back toward or above 4% would validate the idea that last quarter's slowdown was a timing blip. Another reading in the low 3% range would make the full-year target look stretched and raise doubts about how quickly wins like the large hyperscaler relationship, the Ahold e-commerce award in continental Europe and expanded aerospace and defense work actually hit the income statement. Updates on the 2027 secured revenue figure, which stood near $353 million, and on whether the record $2.7 billion pipeline held up after heavy closings will also show if commercial momentum is durable.
Margins are the other swing factor. Adjusted EBITDA margin was flat year over year at 6.4% last quarter, and management deferred visible improvement to fourth-quarter green shoots and to Investor Day. That makes this report something of a bridge quarter. Investors should look for evidence that Wincanton integration remains on track for $60 million of run-rate synergies by year end, that the GXO IQ automation rollout toward roughly 50 sites is progressing, and that standardized labor management and procurement are beginning to show up in costs. Continued positive free cash flow and leverage holding near 2.6x would support the resumed buyback.
Sentiment has warmed noticeably, with bearishness easing to 9.4% from 28.8% ahead of the prior report, yet the stock has not followed. Shares are down 5.1% since the last report, trailing the S&P 500 by about 3 points, and at $48.43 they trade below the 200-day moving average near $52, in the middle of a post-earnings range between $43.61 and $51.04. The market, in other words, is giving GXO credit for its pipeline but withholding it on execution.
That sets up the core issue. If third-quarter revenue shows the new-business ramp arriving and margins holding steady, the record signings start to look like a genuine growth inflection heading into Investor Day. If organic growth stalls again, the narrative of strong bookings outrunning weak conversion will harden, and management will need to do far more convincing on November 16.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-15 | |
| Oct-08 | |
| Oct-07 | |
| Sep-29 | |
| Sep-28 | |
| Sep-23 | |
| Sep-17 | |
| Sep-15 | |
| Sep-03 | |
| Sep-02 | |
| Aug-19 | |
| Aug-17 | |
| Aug-12 |
