Ferroglobe's Recovery Faces A Pricing Test As Critical-Materials Promises Near Their Deadline
Ferroglobe enters its third-quarter report with two stories pulling in different directions. Operationally, the second quarter looked like a genuine turn off the bottom, with adjusted EBITDA jumping to $13 million from $3 million and free cash flow swinging to a $20 million inflow. Strategically, management pitched a new identity as a government-backed critical-materials supplier. Yet the core silicon business is still losing money on weak prices, and Wall Street's numbers suggest analysts are not convinced the improvement will hold.
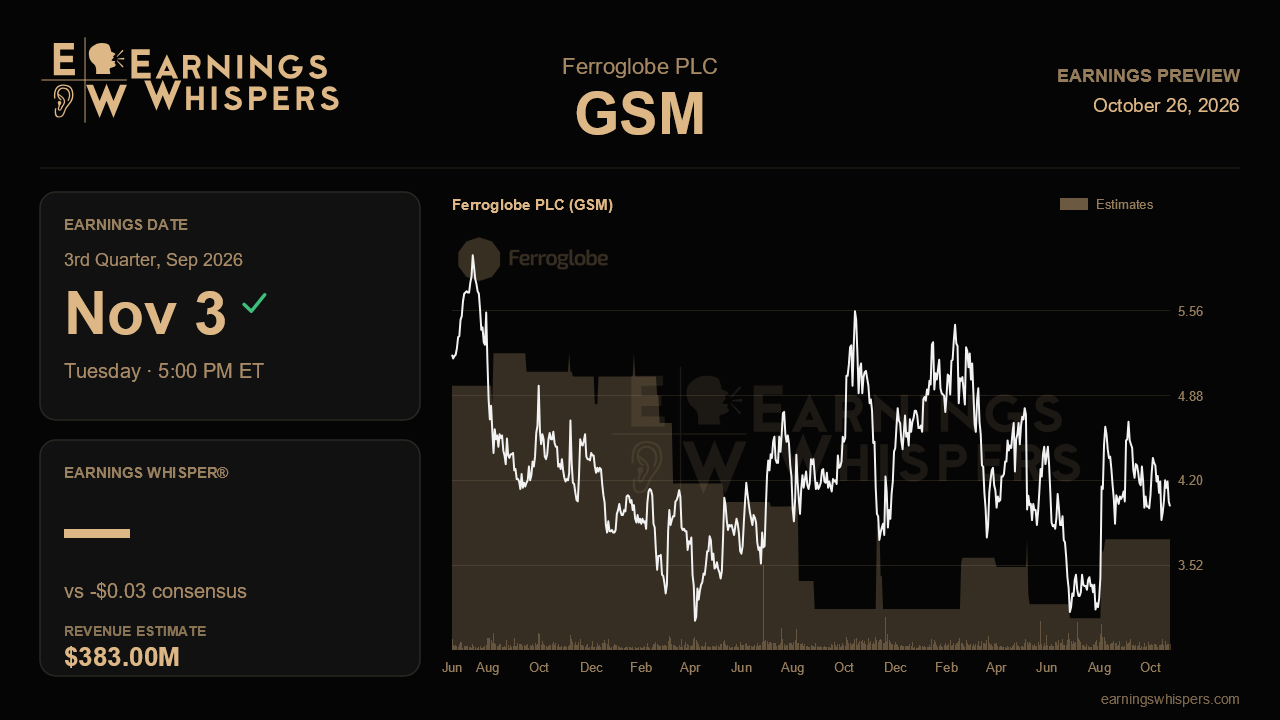
Consensus calls for a loss of $0.03 per share on revenue of $383.0 million. That revenue figure is up nearly 23% from the year-ago $311.7 million but essentially flat against the $378.6 million posted last quarter, while the expected loss is wider than both the breakeven second quarter and the $0.02 loss a year ago. In other words, the Street is modeling volume gains that have already happened and margins that slip back. Part of that caution is reasonable: the second quarter's silicon-based alloys result included a $5 million benefit from Spanish litigation that will not repeat. There is also a guidance gap to consider. Management did not reiterate its earlier $1.5 billion to $1.7 billion full-year revenue target on the last call. With first-half sales around $727 million, consensus for the third quarter leaves the company needing a stronger fourth quarter just to reach the low end, so any commentary on that range will be telling.
The most important operating question is whether the second-quarter mix shift can be sustained. Manganese was the hero, with segment EBITDA tripling to $30 million as index prices climbed on European safeguards. Silicon metal shipments rebounded 34%, but the average selling price fell 6% to $2,592 a ton and the segment stayed in the red. Validation this quarter would look like manganese holding most of its gains, silicon metal pricing stabilizing as finalized U.S. duties on Australian and Norwegian imports take hold, and early signs that the polysilicon price floor is lifting U.S. demand. A challenge would come from another leg down in European ferro-silicon, which management has already described as poorly protected by safeguards, or from new low-cost imports from countries such as Angola and Azerbaijan eroding U.S. volume gains.
The critical-materials pivot faces its first credibility check. Management targeted initial commercial activity in ferromolybdenum and magnesium before year-end, pointing to sizable North American markets and active talks with the Department of Energy and the Department of War. This report should show whether those discussions are turning into contracts, offtake agreements or funding. A decision on the U.S. permit to engage with Venezuela on roughly 120,000 tons of low-cost capacity was also expected by the end of the third quarter. With buybacks suspended to fund these ambitions, shareholders deserve concrete milestones, along with clarity on the cost-reduction program and the French power contract that produced a $60 million mark-to-market swing last quarter.
Sentiment has cooled noticeably, with the bearish reading roughly doubling from the prior quarter. The stock has edged up about 2% since the last report while the S&P 500 fell, a modest relative win, but at $3.99 it sits below its 200-day moving average and near the bottom of its post-earnings range between $3.75 and $4.75. That combination suggests the market has not paid up for the turnaround.
The central issue is whether the second quarter was a floor or a blip. If margins hold near last quarter's level without the litigation help and critical materials produce something tangible, the modest expectations bar looks easy to clear. If silicon pricing keeps sliding and the new strategy remains a slide-deck opportunity, the improving narrative will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Sep-22 | |
| Sep-01 | |
| Aug-04 | |
| Jul-21 | |
| May-05 | |
| Apr-21 | |
| Feb-18 | |
| Feb-18 | |
| Feb-17 | |
| Feb-17 | |
| Feb-02 | |
| Jan-09 | |
| Dec-29 |
