Ferroglobe Misses As Spanish Energy Shock Sinks EBITDA, Forcing Five Plant Closures And A $100 Million Self-Help Bet
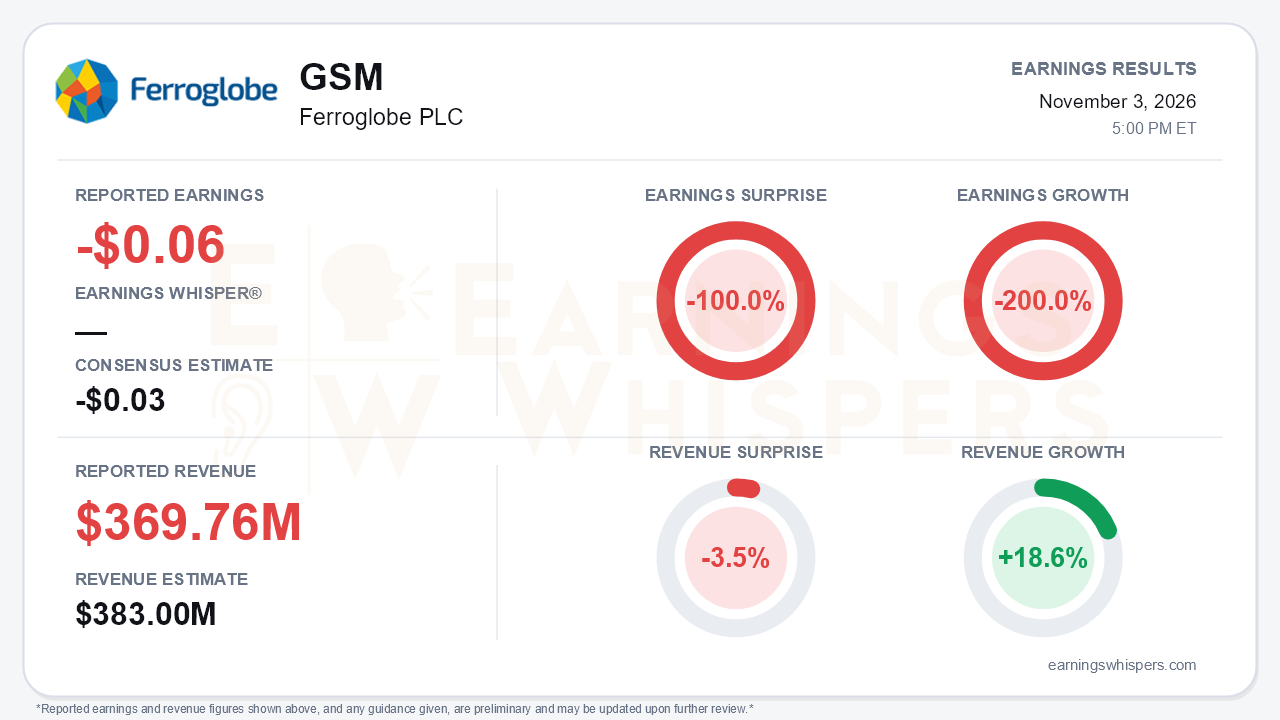
Ferroglobe's third quarter undid the modest recovery it showed in the second. The company reported an adjusted loss of $0.06 per share, twice the $0.03 loss consensus expected, a 100.0% miss. Earnings fell 200.0% year over year. Revenue of $369.76 million rose 18.6% from a year ago but missed the $383.0 million consensus by 3.5% and slipped 2.3% sequentially. Adjusted EBITDA turned negative at $(2.4) million, down from $13.1 million in Q2 and $18.3 million a year earlier. The company attributes nearly $19 million of the damage to higher Spanish energy costs tied to the Middle East conflict. The central tension is that management answered a quarter it called disappointing with its most aggressive restructuring yet. The investment case now rests far more on self-help and trade policy than on the end markets.
The GAAP numbers deserve scrutiny because they point in the opposite direction. Net profit attributable to the parent was $57.9 million, or $0.31 per diluted share. That profit came almost entirely from a $76.8 million positive fair-value adjustment on long-term energy contracts, which is a non-cash mark that management strips out of adjusted results. Excluding those marks, raw materials and energy consumed 72.5% of sales, up from 67.3% in Q2. That jump is the clearest measure of the cost squeeze. Cash flow was better than earnings: operating cash flow reached $25.9 million and free cash flow $5.6 million. Both figures leaned on a $34.8 million working-capital release rather than on profitability. Free cash flow fell from $20.4 million in Q2, and net debt edged up to $42.1 million.
Beneath the headline, the segments diverged sharply. Silicon metal pricing finally turned, with realized prices up 3.0% to $2,669 per ton after declines in Q1 and Q2. The call noted U.S. and EU silicon metal indices rose 10% and 6% following trade actions. Shipments, however, fell 6.5%, and the segment still lost money. Silicon-based alloys were the real problem. Volumes dropped 6.0%, European pricing weakened, and segment EBITDA swung from $14.5 million to $(2.0) million, although Q2 had included a roughly $5 million litigation benefit. The European ferrosilicon index is down 16% year to date despite safeguards, as imports from Malaysia, Bhutan, Azerbaijan, India and Angola fill the gap. Manganese alloys were the steady performer, with revenue up 5.9% to $114.0 million on a 4.7% price gain. Even there, energy costs compressed the margin from 12.1% to 10.0%.
The forward story is now about restructuring. Management plans to close five plants, subject to employee consultations, and cut overhead by 20%. The goal is to lift utilization from below 60% to about 80% while keeping annual volumes largely unchanged. The target is an adjusted EBITDA improvement of $85 million to $115 million at full run rate. On the Q2 call, management had called sizing such a program premature, so quantifying it now is a material shift. The cost is real, though: $40 million to $60 million upfront over 18 months, net of an expected $30 million to $40 million working-capital release. The plan also carries labor and execution risk.
Other catalysts advanced:
- Critical materials moved to first commercial ferromolybdenum shipments in Q3, ahead of the year-end target, with ferrovanadium, low-carbon ferrochrome and ferroboron work planned for Q4.
- A final proposal to the U.S. Department of War is due in November, with negotiations expected to conclude by the end of Q1 2027.
- The EU's anti-dumping review and registration of Chinese silicon metal imports opens the door to retroactive duties.
The outlook still has clear weak spots. Management guided Q4 to remain challenging, and South African plants are mothballed. The Venezuela OFAC license, previously expected by the end of Q3, is still pending.
Guidance credibility has also eroded. On the Q4 FY2025 call, management framed 2026 revenue at $1.5 billion to $1.7 billion. Revenue through three quarters totals about $1.1 billion, which leaves that range out of reach without an implausible fourth quarter. Management's tone shifted from Q2's "cautiously optimistic" to an explicit focus on factors within its control.
Investors were already skeptical heading into the print, and they grew more so. Earnings Whispers sentiment stayed negative and weakened modestly, from -0.12 to -0.20. Shares closed at $3.86, essentially flat (-1.5%) since the open following the August report. They also sit about 8.5% below the 200-day moving average of $4.22, and the AVWAP trend reading remains negative. In other words, the stock has made no headway this quarter despite improving silicon pricing and trade wins.
The bottom line is that Ferroglobe delivered a clean miss on both lines, and its GAAP profit is an accounting artifact of energy-contract marks. The genuine news is strategic. A sizable cost program, firming silicon metal prices and earlier-than-planned critical-materials revenue give bulls a self-help narrative. Bears have legitimate ammunition in the abandoned growth framework, the collapse in silicon-based alloys, rising net debt and $40 million to $60 million of restructuring cash still to be spent. Until the closures begin showing up in margins, the restructuring target remains a promise rather than a result.
Read our earnings preview for Ferroglobe PLC: https://www.earningswhispers.com/article/GSM/21579
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Sep-22 | |
| Sep-01 | |
| Aug-04 | |
| Jul-21 | |
| May-05 | |
| Apr-21 | |
| Feb-18 | |
| Feb-18 | |
| Feb-17 | |
| Feb-17 | |
| Feb-02 |
