IFF's First Quarter As A Leaner Company Tests Its Buyback-Fueled Rally
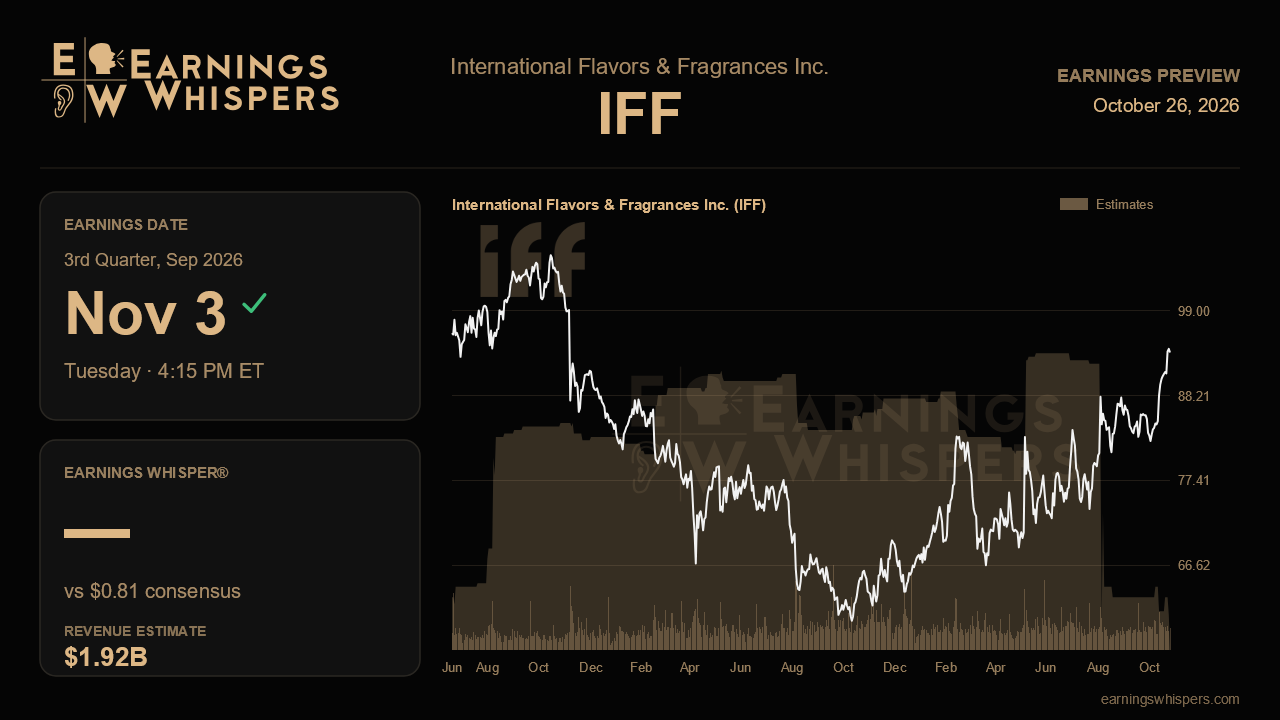
International Flavors & Fragrances heads into its third-quarter report with a stock that has already started pricing in a better company. Since management signed the Food Ingredients sale to CVC and unveiled a $2.5 billion buyback, shares have climbed 12.3% while the S&P 500 slipped 2.1%. The question now is whether the slimmer IFF can show the operating results to match. That is harder when the company itself has warned that the second half will be slower.
The headline numbers will look alarming at first glance, and mostly for accounting reasons. Analysts expect earnings of $0.81 a share on revenue of $1.92 billion. That works out to declines of roughly 23% and 29% from a year ago. Most of that gap comes from moving Food Ingredients into discontinued operations, not from a collapse in demand. The more useful comparison is with the prior quarter: $0.82 a share on $1.95 billion. On that basis, the Street is looking for a roughly flat quarter. Management's revised 2026 revenue outlook of $7.4 billion to $7.6 billion now excludes the divested business. Older full-year consensus figures near $10.75 billion still reflect the former structure, so they are not a fair yardstick. What matters more is whether management reaffirms its continuing-operations targets of 2% to 4% sales growth and 4% to 8% EBITDA growth.
Those targets were raised last quarter. But the increase largely reflected a strong first half rather than any expected acceleration, so the hard part of the year is still ahead. Second-quarter sales rose about 6%, driven by volume in all three remaining segments. Management guided to a moderation toward low-single-digit growth in the back half. Scent is the segment to watch. Fragrance ingredients jumped about 20% against an easy comparison, and that pace is expected to fade. Fine fragrance faces a 20% comparison in the third quarter, and the Middle East conflict continues to weigh on it. Modest input-cost inflation, with pricing trailing behind, is also most acute in Scent. If Taste and Health & Biosciences keep growing in the mid-single digits while Scent merely softens rather than stalls, the guidance looks safe. A sharper slowdown in Scent paired with margin compression would challenge the idea that the first half was a sign of underlying strength rather than a high-water mark.
Margins carry their own complication. Roughly $100 million of stranded corporate costs now sit across the three remaining units. Management stretched the timeline for removing them, aiming for about two-thirds in the first year and the rest in year two. Early, concrete progress on those savings would ease concerns that the cleanup is slipping. Silence on the topic would invite skepticism.
Cash is the other test. First-half free cash flow reached $378 million, a dramatic improvement from the full-year 2025 figure of about $256 million. Management has flagged a second-half working-capital drag of roughly $200 million tied to the separation. Investors should look for evidence that underlying cash generation is holding up despite that drag. They should also look for an update on the roughly $500 million of repurchases planned for the second half, and on the path to a leverage target of 2.0 to 2.5 times by the end of 2027.
Expectations have clearly risen. Sentiment has turned modestly bullish at 7.6%, up from essentially neutral at 0.9% a quarter ago. The stock, at $94.15, sits comfortably above its 200-day average near $78. It is also within a whisker of its post-earnings high of $94.59, so the report could determine whether shares break out or stall at resistance. The narrative stays intact if IFF can absorb the tough Scent comparison, show stranded costs coming out, and keep cash flowing toward buybacks. Falling short on that combination would leave a rally built on portfolio moves vulnerable to doubts about the core business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-13 | |
| Oct-06 | |
| Sep-30 | |
| Sep-18 | |
| Sep-17 | |
| Aug-25 | |
| Aug-18 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 |
