IFF Beats And Raises The Floor, But Health & Biosciences Stalls And Cost Pressure Builds Into 2027
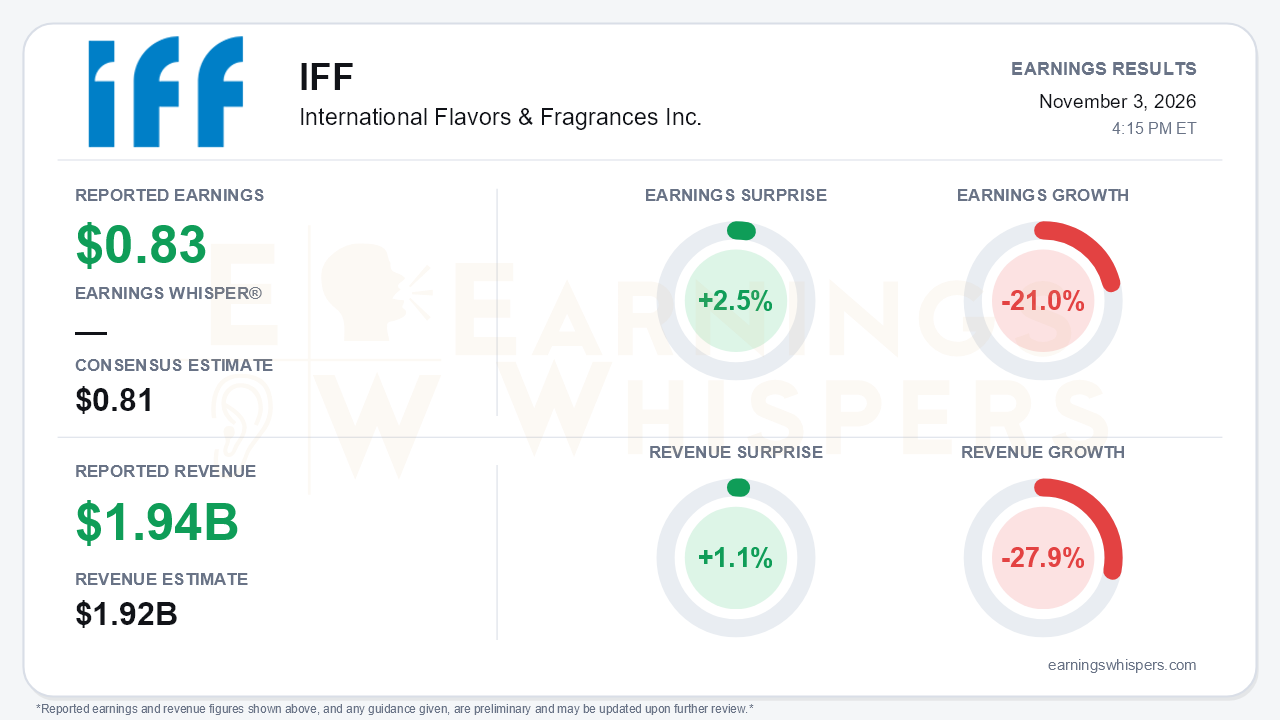
IFF delivered a clean beat on the measures investors were watching. Adjusted EPS excluding amortization was $0.83, ahead of the $0.81 consensus by 2.5%. Revenue of $1.942 billion topped the $1.92 billion estimate by 1.1%. Management also raised the low end of its full-year sales and EBITDA ranges for the second straight quarter. The year-over-year picture depends on the basis used. Earnings Whispers' normalized comparison shows earnings down 21.0% and revenue down 27.9%. On the continuing-operations basis the company now reports, sales rose 4% and adjusted EPS ex-amortization climbed from $0.76. That gap appears to reflect the reshaped reporting perimeter, which treats Food Ingredients and the SCL businesses as discontinued operations, rather than a collapse in the remaining business. The central tension is different: Taste and Scent are accelerating, while Health & Biosciences has stalled and fourth-quarter margins are set to soften.
The quality of the quarter is better than the GAAP line suggests, but it still deserves scrutiny. IFF posted a GAAP loss from continuing operations of $0.50 per share, a swing from a $0.39 profit a year ago. Most of that came from three items:
- a $236 million loss on assets classified as held for sale, tied to the Botanicals & Food Enhancements disposal group;
- a $23 million goodwill impairment;
- $34 million of regulatory costs tied to the ongoing fragrance investigations, up from $7 million a year earlier.
The regulatory charge is the item bears should watch, because it is recurring and growing: $115 million year-to-date. Underneath, the business worked. Currency-neutral comparable sales rose 5%, adjusted operating EBITDA increased 6% to $403 million, and margin edged up 30 basis points to 20.8%, all driven primarily by volume.
The segment mix tells the real story. Scent was the standout. Comparable currency-neutral EBITDA grew 10%, double the roughly 5% pace in the second quarter, on high-single-digit growth in Consumer Fragrances. Fine Fragrance grew mid-single digits against a strong double-digit comparison that management had expected to weigh on results. Taste sales accelerated to 6% from 4% in the prior quarter, with double-digit growth in Greater Asia. Health & Biosciences went the other way. Sales growth slowed to 1% from 5% in the second quarter, and EBITDA growth slowed to 2% from 6%, as the Health business declined. Management had previously expected Health to return to growth in the second half of 2026. It now describes a soft dietary-supplement market in the U.S. and Europe and a turnaround that is taking time.
The forward guidance carries a quieter warning. The raised full-year ranges ($7.5 billion to $7.6 billion in sales and $1.55 billion to $1.60 billion in adjusted EBITDA) imply fourth-quarter sales growth of about 3%, down from roughly 5% in the third quarter. Management explicitly flagged softer fourth-quarter profitability in Health & Biosciences. The causes are adverse health mix, logistics and energy inflation, and the timing of reinvestment. On the call, management said price-to-input costs turn unfavorable in the fourth quarter and that the gap peaks in the first quarter of 2027, with about 3% raw material inflation expected next year. Pricing negotiations are underway, and management expects the gap to narrow each quarter through 2027. Investors are being asked to look through two soft quarters of cost lag.
The balance sheet and cash flow also deserve attention.
- Nine-month free cash flow of $371 million is up $245 million year over year, but slightly below the $378 million reported at the half. That implies a flat-to-negative third quarter.
- Net leverage rose to 2.75x from 2.5x after short-term debt funded the completed $500 million accelerated share repurchase.
- No further buybacks are planned for the fourth quarter.
The offsetting catalyst is the Food Ingredients sale to CVC, valued at about $4.3 billion. It remains on track to close by the end of the second quarter of 2027, though eliminating about $100 million of stranded costs introduces execution risk. Smaller positives include a new Health product launch with strong early interest, fine fragrance wins with major houses, and new creative centers in Madagascar, Brazil and Mumbai.
The market had already moved toward the improving story. Shares have gained 10.0% since the open following the August report, to $92.18, and sit 17.1% above the 200-day moving average of $78.72. Investor sentiment became more positive, rising from 0.0088 to 0.0953, but it remains only modestly above neutral rather than euphoric. Price, momentum and AVWAP trend readings are positive, while sequential growth remains negative. That split matches the slowing Health business and the guided fourth-quarter slowdown.
The bottom line is that IFF delivered a credible beat-and-raise quarter. The strength came from Taste and Scent volume, while Health & Biosciences weakened noticeably. Shares already trade well above their long-term average, and the guidance points to slower growth and margin pressure through early 2027. That makes the setup more demanding than the headline beat implies. The next leg likely depends on Health stabilizing, pricing catching up with costs, and the Food Ingredients sale closing cleanly.
Read our earnings preview for International Flavors & Fragrances Inc.: https://www.earningswhispers.com/article/IFF/21584
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-13 | |
| Oct-06 | |
| Sep-30 | |
| Sep-18 | |
| Sep-17 | |
| Aug-25 | |
| Aug-18 |
