Huron Must Show Its Growth Inflection Can Justify A 46% Post-Earnings Rally
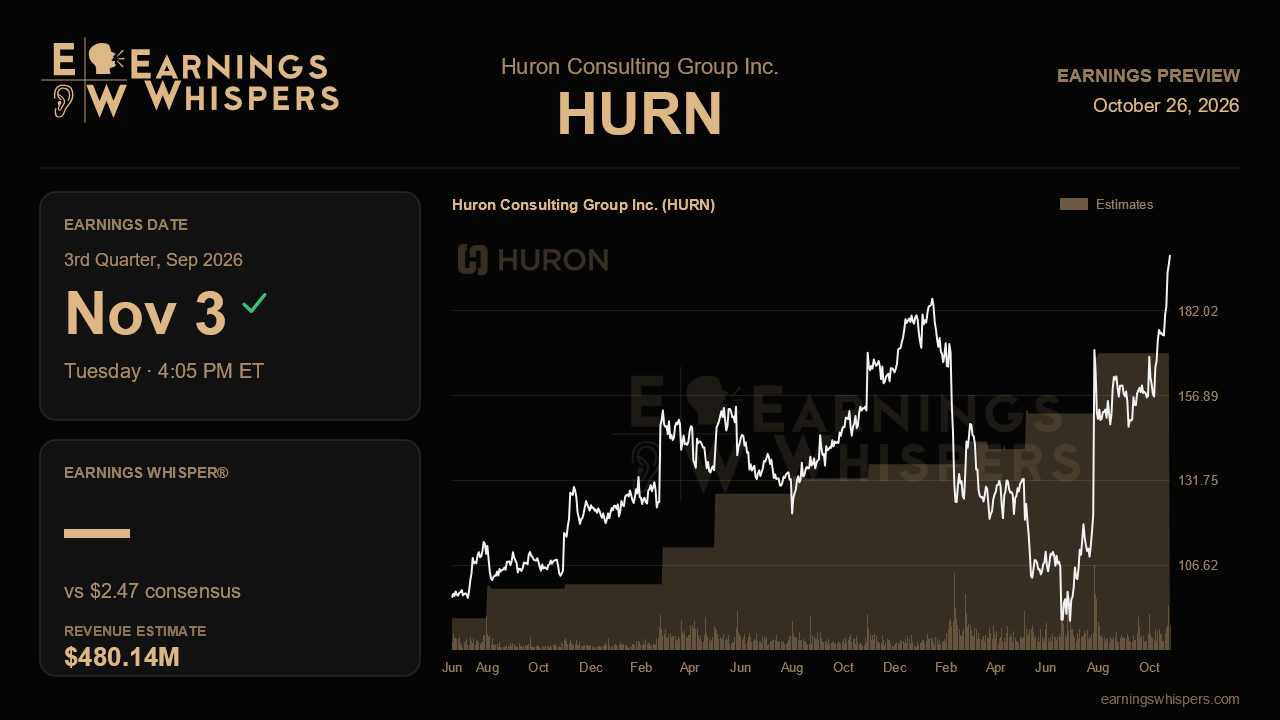
Huron Consulting Group heads into its third-quarter report with an unusual problem: the market has already priced in a great deal of good news, yet Wall Street's published estimates still sit below the company's own outlook. Shares have climbed nearly 46% since the last report, while the S&P 500 managed less than 3%, a gap that reflects how decisively investors embraced management's mid-year guidance raise. The question now is whether the September quarter confirms that the acceleration seen in the spring was a new baseline rather than a high-water mark.
Analysts expect earnings of $2.47 per share on revenue of about $480.1 million. That would represent roughly 18% earnings growth and nearly 9% revenue growth from a year ago, solid but noticeably calmer than the second quarter, when revenue before reimbursements grew almost 16% and adjusted earnings jumped about 30%. Sequentially, the forecast is nearly flat with the prior quarter's $2.46 and $475 million. The more striking detail is the full-year comparison. Management now guides to $9.00 to $9.40 in adjusted earnings and $1.85 billion to $1.89 billion in revenue, yet consensus sits at $8.71 and $1.82 billion, below the bottom of both ranges. Either the Street is being deliberately cautious about the back half, or estimates simply have not caught up. In either case, the bar for this quarter looks lower than the stock price implies.
The prior call gave investors a clear checklist. Healthcare, the firm's engine, was lifted to a mid-teens growth outlook, and healthcare managed services surged 64%, with 43% of that organic. Education growth doubled to nearly 8% from under 4% in the first quarter, prompting a raised mid-to-upper single digit target. Most importantly, management grew noticeably more assertive about artificial intelligence, noting that digital bookings rose more than 20% in the first half and that over 60% of them carried direct AI scope, up from roughly 35% a year earlier. Continued strength in digital bookings, organic growth that stays near double digits, and early contribution from the RelateCare acquisition, expected to add about $30 million in revenue and $0.10 in earnings this year, would validate that narrative.
The risks are specific and worth watching. Management flagged that its commercial segment faces tougher second-half comparisons as prior acquisitions anniversary and a couple of distressed financial advisory engagements wind down. Utilization ran above 80% in the second quarter, well over the upper-70s target, which forced accelerated hiring. That is a sign of healthy demand, but new consultants cost money before they bill efficiently, and RelateCare brings integration expenses this year. Notably, the full-year EBITDA margin target of 14.5% to 15% was maintained rather than raised, so any slippage toward the low end would raise questions about operating leverage. A share count reduced by buybacks to 16.6 million to 16.8 million offers some cushion on a per-share basis.
Sentiment tells an intriguing story. Positioning remains about as bearish as it was ahead of the last report, essentially unchanged despite the stock's surge, suggesting plenty of skeptics remain. The shares trade near $196, far above the 200-day average of about $138 and roughly 4% below the post-earnings high of $203.37, an entire trading range that sits above the prior quarter's peak. That leaves the stock elevated but not yet pressing against a breakout.
Ultimately, this report hinges on whether healthcare and AI-driven digital demand can keep organic growth strong enough to absorb commercial softness and heavier hiring costs without denting margins. Reaffirming or nudging up the raised guidance would likely pull consensus higher and support the rerating. A margin squeeze or cooling organic growth, by contrast, would suggest the rally ran ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Sep-22 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-14 | |
| Jun-29 | |
| Jun-22 | |
| Jun-03 | |
| May-05 |
