Huron Beats And Raises On Record Margins, But Slowing Organic Growth And A Cash-Flow Cut Complicate A 45% Run
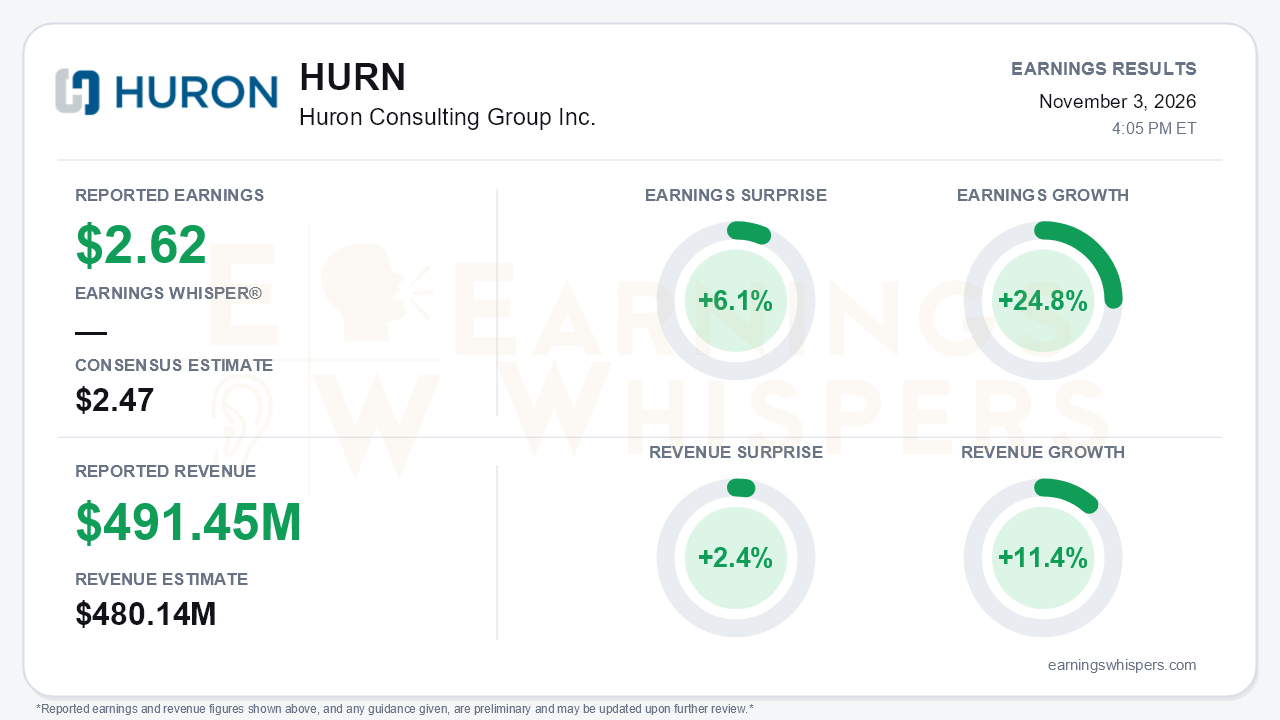
Huron Consulting Group delivered the beat-and-raise quarter its rally demanded, but the details are less clean than the headline. Adjusted EPS of $2.62 topped the $2.47 consensus by 6.1% and grew 24.8% year over year. Revenue of $491.45 million beat expectations by 2.4% and rose 11.4%. Management lifted the midpoint of full-year adjusted EPS guidance to $9.30, now a $9.20-$9.40 range. That is the central tension: profitability is clearly improving, while top-line growth, the Commercial segment and cash conversion all moved the wrong way.
The quality of the beat deserves scrutiny. Revenues before reimbursable expenses rose 11.6% to a record $482.5 million, but $21.1 million came from acquisitions. Organic growth was 6.7%, below the 8.2% year-to-date pace, and total growth slowed from 15.7% in the second quarter.
The EPS line also benefited heavily from capital deployment. Adjusted net income grew 14.1%, well short of the 24.8% per-share gain. The gap reflects a diluted share count that fell to 16.3 million from 17.8 million after Huron repurchased about 10% of its stock this year. Much of that buyback was debt-funded, with long-term debt climbing to $794 million from $490 million at year-end.
GAAP EPS rose only 2.3% to $1.75. That figure absorbed a $0.36 hit from a non-cash credit loss on a convertible debt investment, plus a $4.9 million contingent-consideration charge. Management attributed the contingent-consideration charge to acquired businesses outperforming their original assumptions, which is arguably a high-class problem.
Margins are the genuine bright spot. Adjusted EBITDA margin reached 16.0%, an eight-year quarterly high. Utilization rose to 76.2% in Consulting and 81.2% in Digital. Education was the standout: segment operating income jumped 21% on just 6.6% revenue growth, and margin reached 29.1%. Management said Education is tracking at or above the top of its 24%-26% target. Healthcare grew 16.5%, and Healthcare managed services revenue nearly doubled to $48.9 million, with a third straight quarter of 40%-plus organic growth.
Beneath those numbers, however, momentum cooled:
- Healthcare organic growth slowed to 9% from 12% in the second quarter.
- Commercial revenue growth collapsed to 6.4% from 24.6%. Organic Commercial growth was only low single digits, and Commercial digital fell 1% amid slower conversion of AI projects.
- Commercial margin fell to 13.9% from 21.0% in the prior quarter. Management cut the segment's full-year outlook to low-double-digit growth at the low end of its 19%-21% margin range.
Utilization near its ceiling also limits how much more efficiency can carry earnings.
The weakest disclosure was cash. Management cut full-year free cash flow guidance to $150-$170 million from $180-$220 million, a range it had held on the two prior calls. It cited a revised payment schedule on a multi-year engagement and a heavier mix of performance-fee work. Days sales outstanding rose to 83 from 79. Year-to-date operating cash flow was just $15.3 million versus $67.0 million a year earlier, as unbilled services swelled by $64 million. Revenue guidance was merely narrowed to $1.855-$1.885 billion with an unchanged midpoint, trimming the top end, and the 14.5%-15.0% EBITDA margin outlook was only affirmed. Bears have legitimate ammunition here: earnings are being recognized faster than they are being collected.
The forward story still has credible supports:
- Trailing six-month bookings are up more than 20%.
- AI involvement in digital bookings rose above 65%, from about 60% in the first half and roughly 50% a year ago.
- Management framed 2027 Medicaid changes under the OBBBA as a demand driver and expects a very strong healthcare year.
- RelateCare cross-sell synergies are just beginning.
- Huron is investing about $2.2 million per quarter in Commercial talent, targeting above-average Commercial growth in 2027.
- A $200 million buyback increase leaves $265.9 million available.
- Leverage eased to 2.6x from 2.8x.
- The effective tax rate outlook was lowered to 27%-29%.
The market setup is more complicated than the surprise implies. Shares entered the report at $195, up 45.4% from the $134.09 open after the July release. That price sits 40.7% above the 200-day moving average and about 4% below the 52-week high of $203.37 set on October 23. Investor sentiment, meanwhile, remained negative and was essentially unchanged, edging from -0.33 to -0.32. The Earnings Whispers trend readings are uniformly positive, consistent with the strength of the run. Still, a stock priced this close to its highs leaves little room for a quarter featuring decelerating organic growth and a cash-flow cut.
The bottom line is that Huron's margin expansion, Healthcare managed-services surge and higher EPS guidance keep the earnings story intact. However, the headline beat leaned on buybacks, acquisitions and near-peak utilization. Slowing organic growth, a stumbling Commercial segment and a roughly $40 million free-cash-flow cut are the issues to watch. After a 45% run, the burden now shifts to proving that 2027 demand and cash conversion can catch up with reported profits.
Read our earnings preview for Huron Consulting Group Inc.: https://www.earningswhispers.com/article/HURN/21583
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-28 | |
| Oct-26 | |
| Oct-22 | |
| Oct-22 | |
| Oct-20 | |
| Sep-22 | |
| Jul-29 | |
| Jul-28 | |
| Jul-28 | |
| Jul-27 | |
| Jul-14 | |
| Jun-29 |
