IGI Needs A Quieter Quarter On War Losses To Restore Faith In Its Margins
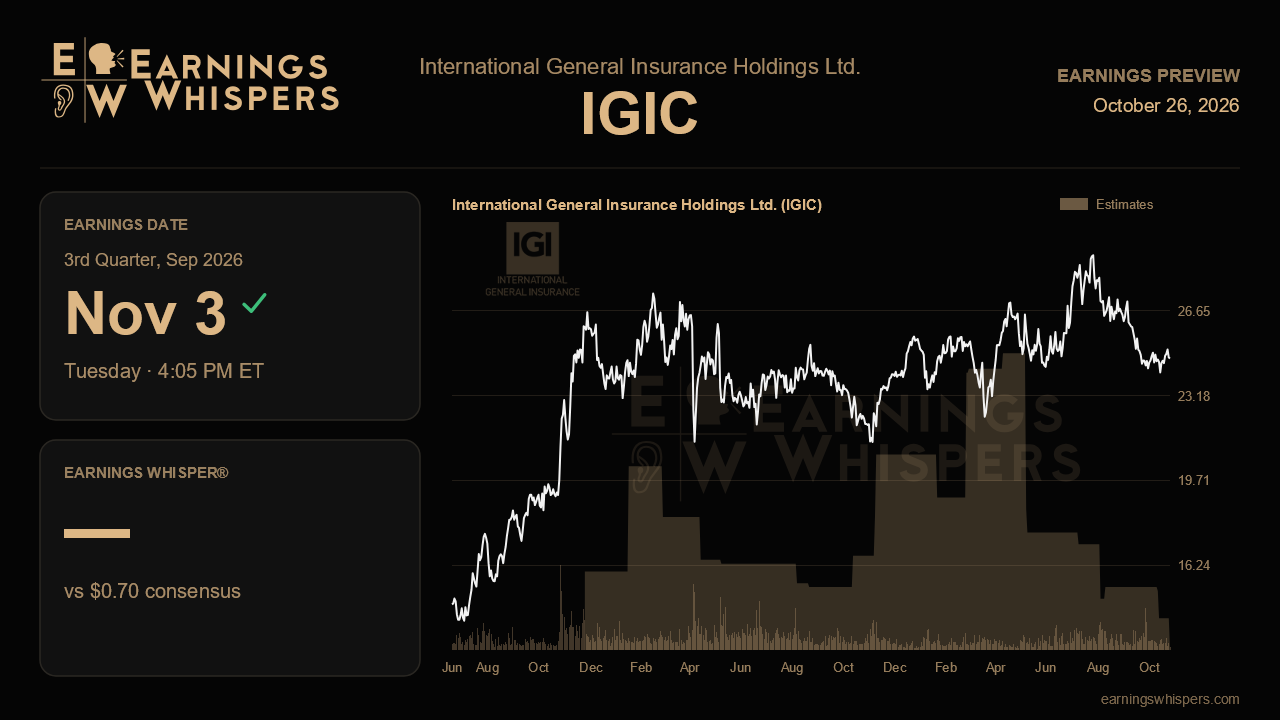
International General Insurance enters its third-quarter report needing to prove that the record war losses that marred the first half were a passing storm rather than a new climate. The specialty insurer told investors last quarter that its underlying underwriting remained sound even as headline profitability slid. The stock's behavior since then suggests the market has not fully bought that argument, which makes this release a referendum on whether the softer numbers were mostly bad luck or the start of something more durable.
The Street is looking for earnings of $0.70 per share, down roughly 19.5% from the $0.87 earned a year earlier. That is a contraction, but it is also a meaningful rebound from the $0.44 posted in the second quarter. In other words, consensus already assumes catastrophe and war losses recede sharply. Management did not issue a formal numerical outlook, instead leaning on its over-the-cycle return framing, so the burden falls on the combined ratio to bridge the gap. After deteriorating from about 86% for 2025 to 89.1% in the first quarter and 95.1% in the second, the ratio likely needs to move back toward the low 90s or better for the $0.70 target to hold.
The core issue is how much of last quarter's damage recurs. Roughly 19 points of catastrophe losses hit the second quarter, about 12 of them tied to the Middle East conflict, plus another 4.5 points of indirect war losses booked elsewhere. First-half net war losses of about $39 million were likely the largest single loss event in IGI's roughly 25-year history. Any meaningful additional war development would directly challenge the idea that these losses were contained. Conversely, a clean quarter would let the ex-catastrophe accident-year combined ratio, which improved to 74.9%, show through, validating management's insistence that discipline held.
There are genuine offsets to track. The long-tail segment swung to underwriting profit, with net earned premiums up 33% in the second quarter, and management sounded more confident about rate stabilization there than it had in prior calls. Investors should want continued profit in that book and, importantly, a return to favorable reserve releases after the modest $1.7 million strengthening last quarter broke a long streak of positive development. The Middle East political violence book, which grew about 45% on enormous pricing corrections, should be earning through at attractive margins. The new India Gift City branch, which wrote about $10 million of niche reinsurance within weeks of approval, is a fresh catalyst whose next quarter of premium will indicate whether it is a meaningful growth leg or a small sideline. Investment income at a 4.5% yield should also provide steady support.
The risks are equally clear. Management described competition in energy and property as increasingly irrational, treaty reinsurance softened at mid-year renewals, and regional infrastructure projects have been delayed or cancelled. Premium growth that stalls, or commentary hinting at a weaker January renewal season, would reinforce the view that IGI is shifting from harvesting a hard market to defending margins in a soft one. Book value per share, which slipped to $16.04 from $16.91 at year-end partly due to a $1.15 special dividend, will also be scrutinized.
Sentiment has soured noticeably, moving from 8.2% bearish before the last report to 37.2% bearish now, and the shares have fallen 12.1% since then, trailing the S&P 500 by 10 points. At $24.74, the stock sits below its 200-day average of $25.54 and just above its post-earnings low of $24.00, so expectations are subdued. That lowers the bar for a relief move, but only if IGI can show that, stripped of war losses, its combined ratio and reserve trends still support the mid-teens or better returns that once defined the story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Sep-29 | |
| Sep-01 | |
| Aug-07 | |
| Aug-05 | |
| Aug-04 | |
| Jul-07 | |
| Jun-09 | |
| Jun-08 | |
| May-14 | |
| May-05 | |
| Apr-22 | |
| Apr-16 | |
| Mar-18 | |
| Feb-25 |
