IGI Misses As Underwriting Rebounds From War Losses, But Shrinking Premiums And An Accelerating Soft Market Cloud The Outlook
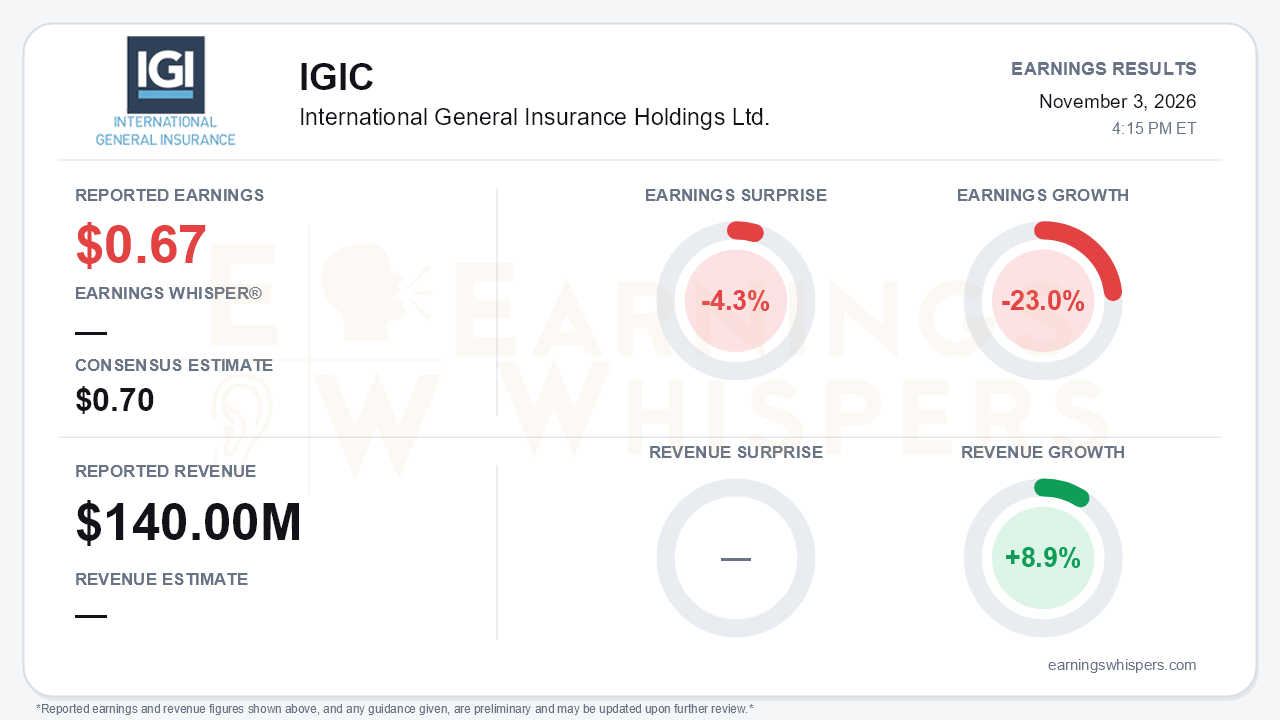
International General Insurance (NASDAQ: IGIC) posted a third quarter that looks much better against the prior quarter than against expectations or a year ago. Core operating earnings of $0.67 per share missed the $0.70 consensus by 4.3% and fell 23.0% year over year. GAAP diluted EPS was $0.66. Revenue rose 8.9% to $140.0 million, lifted by higher earned premiums and investment income. The real story, though, is the split between a sharp sequential recovery in underwriting and a top line that has turned negative just as management says the softening market is getting worse. Investors have to weigh that recovery against those warning signs.
The quality of the quarter deserves scrutiny. The combined ratio improved to 85.7% from 95.1% in the second quarter. Catastrophe losses fell to 6.9 points from 18.8 points as Middle East war losses faded, and prior-year reserves swung to 7.1 points of favorable development from adverse development in Q2. Those are real improvements, but they mostly reflect a normalizing loss environment rather than better core profitability. Compared with last year, the business is earning less:
- The combined ratio was 76.5% a year ago.
- The accident-year combined ratio excluding catastrophes worsened to 85.9% from 79.3%.
- The attritional loss ratio rose to 46.3% from 42.1%.
- The reported acquisition expense ratio jumped to 19.4% from 15.9%, driven by lower realized FX gains and higher commissions.
On the call, management put the FX-neutral acquisition ratio increase at 19.4% from 18.4%. That smaller rise is still a sign of rising commissions in a softer market. Underwriting income fell to $43.0 million from $51.4 million, and core operating ROAE dropped to 16.9% from 22.9%.
The premium trend is the clearest warning sign. Gross written premiums fell 8.9% to $119.6 million, a sharp reversal from 7.4% growth in Q2. The decline came mainly from Short-tail energy, where written premiums dropped to $63.8 million from $76.2 million. Net written premiums also declined. Today's 8.9% revenue growth reflects premiums earned from business written earlier, so lower writings will eventually feed into earned premiums. Management's tone darkened in line with the numbers. The Chairman moved from describing a rapid pace of decline in some areas last quarter to saying the pace of deterioration is accelerating amid unprecedented global uncertainty. Management cited:
- commercial property rates down about 15%;
- energy rates falling quickly;
- property-led pressure in reinsurance;
- no expected near-term turn in short-tail pricing.
There was no formal guidance change.
The call did preserve a credible diversification story. IGI appears to be shifting capital toward lines where pricing is still firm:
- **Long-tail:** Nine-month underwriting income reached $32.9 million versus $1.0 million a year ago, with earned premiums up 16.4%.
- **Reinsurance:** Third-quarter underwriting income rose 22% to $12.7 million.
- **Marine liability:** The direct book has tripled this year on post-Baltimore Bridge pricing.
- **Middle East political violence:** The book is up roughly 50% on sharply better terms, and management flagged possible broader hardening in political violence cover.
- **New initiatives:** IGI launched Cypher, a 60%-owned cyber treaty MGA where it is sole carrier, and its India GIFT City platform should be fully staffed by the end of January.
- **Ratings:** Management sees potential S&P upgrade opportunities in 2027 and beyond.
These initiatives are still small next to a short-tail segment that produced 56% of nine-month premiums.
Balance-sheet trends add to the caution. A $29 million mark-to-market loss on the bond portfolio pushed book value per share down to $15.99, from $16.04 at mid-year and $16.91 at year-end. Buybacks slowed to about 148,000 shares in Q3, compared with roughly 205,000 in Q2 and 545,000 in Q1. That slowdown comes even though the third-quarter repurchase price of $24.68 sits almost exactly at the current share price.
Investors had already moved to a more defensive stance. Earnings Whispers sentiment fell meaningfully, from roughly neutral at -0.08 to -0.45. Shares have dropped 11.1% since opening at $28.14 after the August report and now trade at $25.02, about 2.1% below the 200-day moving average of $25.57. The Earnings Whispers trend signals are mostly negative, with price, sequential growth and AVWAP readings all deteriorating and momentum neutral. The market has been pricing in the cycle turning before the quarterly numbers showed it.
The bottom line is that IGI proved it can still produce mid-teens returns once catastrophe losses normalize, but the quarter showed the cycle turning against its largest business. Core earnings missed, premiums are shrinking, underlying margins are thinner than a year ago, and management expects no near-term relief in short-tail pricing. Growth in long-tail, reinsurance, marine liability and political violence offers a real counterweight. For now, bears have legitimate ammunition, and the stock's slide below its 200-day average reflects a market that cares more about where pricing is heading than about the sequential rebound.
Read our earnings preview for International General Insurance Holdings Ltd.: https://www.earningswhispers.com/article/IGIC/21585
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Sep-29 | |
| Sep-01 | |
| Aug-07 | |
| Aug-05 | |
| Aug-04 | |
| Jul-07 | |
| Jun-09 | |
| Jun-08 | |
| May-14 | |
| May-05 | |
| Apr-22 | |
| Apr-16 |
