Mayville Engineering Must Prove Data Center Growth Can Pay Off After 54% Stock Collapse
Mayville Engineering heads into its third-quarter report with an odd mismatch. Last quarter management described a demand inflection, raised its sales outlook and called this a transformative chapter for the company. Since then the stock has lost more than half its value. The question for November 3 is no longer whether customers want more of what Mayville makes. It is whether the company can turn that demand into profit and cash before the costs of chasing it wear out investors' patience.
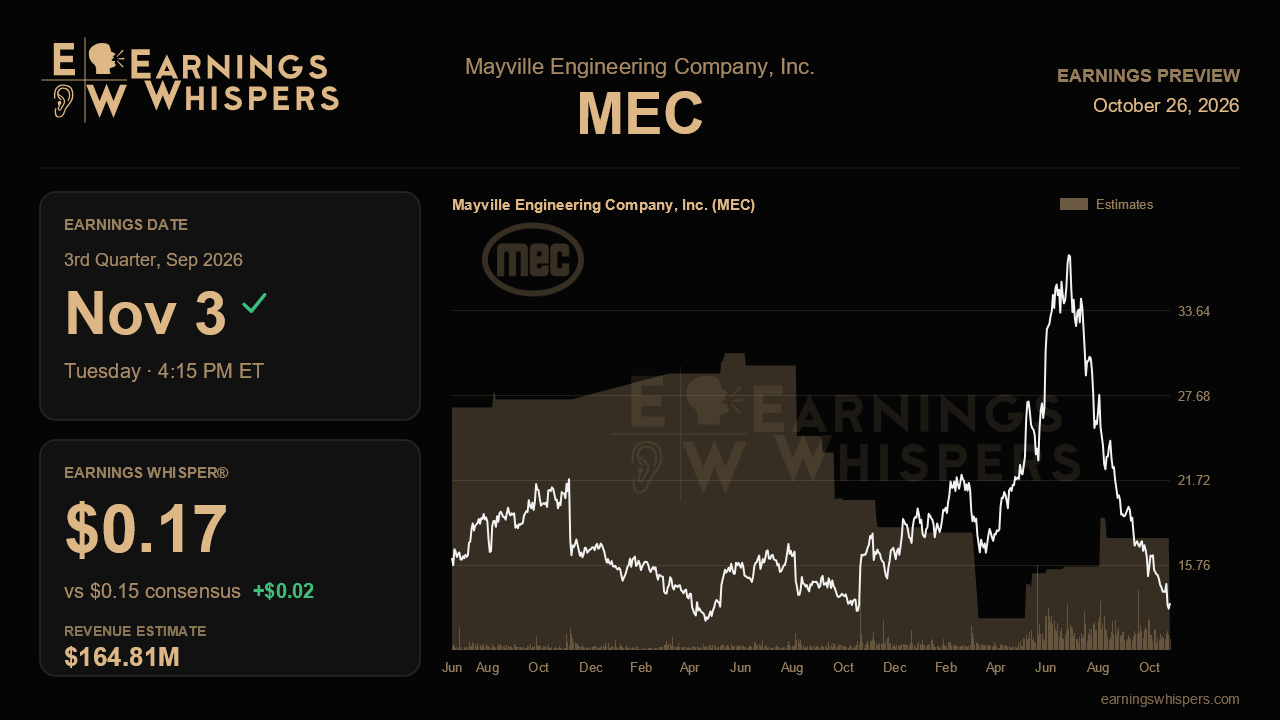
Wall Street expects earnings of $0.15 per share on revenue of $164.8 million, a 14.2% increase from the $144.3 million reported a year ago. That is solid growth, and the earnings line would mark a clear swing from the losses of $0.09 last quarter and $0.13 in the year-ago period. The whisper number of $0.17 sits slightly above consensus, so the informal bar is a bit higher than the published one, though not by enough to change the story. The revenue comparison matters more. Management guided to third-quarter sales of $165 million to $170 million and lifted its full-year range to $635 million to $650 million. Consensus revenue sits just under the bottom of the quarterly range, which suggests analysts are either building in some caution on execution or have not fully caught up with the latest guidance. If Mayville lands in the middle of its own range, revenue should beat comfortably. A result at or below the low end would raise doubts about a guide that has already been raised several times this year.
The growth driver is data center and critical power, where organic growth hit roughly 173% last quarter after about 71% in the first quarter. The segment is expected to make up about a fifth of 2026 revenue, and the company booked about $90 million of awards in the first half, including one new customer worth roughly $55 million. Confirmation this quarter would look like continued triple-digit growth in that business, new bookings that keep the company on track for more than $150 million for the year, and progress on capacity reservation contracts that could bring upfront fees and volume commitments. Legacy markets carry their own test. Commercial vehicle sales turned positive last quarter for the first time in a long while, helped by an industry forecast calling for a sharp jump in second-half Class 8 production. If that ramp shows up in the third-quarter numbers, the recovery case holds. If truck volumes stall, the company loses the second engine of its growth story.
The real fight is over margins and cash. Adjusted EBITDA margin dropped to 8.1% last quarter from 10.3% a year earlier, weighed down by $2.1 million of launch costs. Management warned of another $2 million to $3 million in outsourcing expenses in the second half, because new laser, press brake and paint equipment takes four to six months to arrive. Full-year free cash flow guidance was cut to $7 million to $15 million from $25 million to $35 million. With hiring needed in labor markets with unemployment below 3%, any sign that costs are running ahead of plan would hit a nerve. Lower interest expense following the equity raise and the expected August step-down should help, and that should be visible in this report.
Sentiment has soured sharply. Bearish readings are much deeper than heading into the last report, and the stock at $13.10 sits near the bottom of its post-earnings range of $12.42 to $28.63, far below last quarter's range of $21 to $38.76. Expectations, at least in the share price, are low. Revenue and bookings will likely look fine. What decides whether the transformation story survives is evidence that margins have found a floor, that outsourcing costs are temporary, and that the cash flow cut does not need to be cut again.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-21 | |
| Oct-01 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-22 | |
| Jun-02 | |
| May-21 | |
| May-19 | |
| May-19 | |
| May-05 | |
| Apr-22 | |
| Mar-04 | |
| Mar-04 |
