Mayville Engineering Misses The Whisper As Datacenter Demand Surges But Profit And Cash Guidance Slip Again
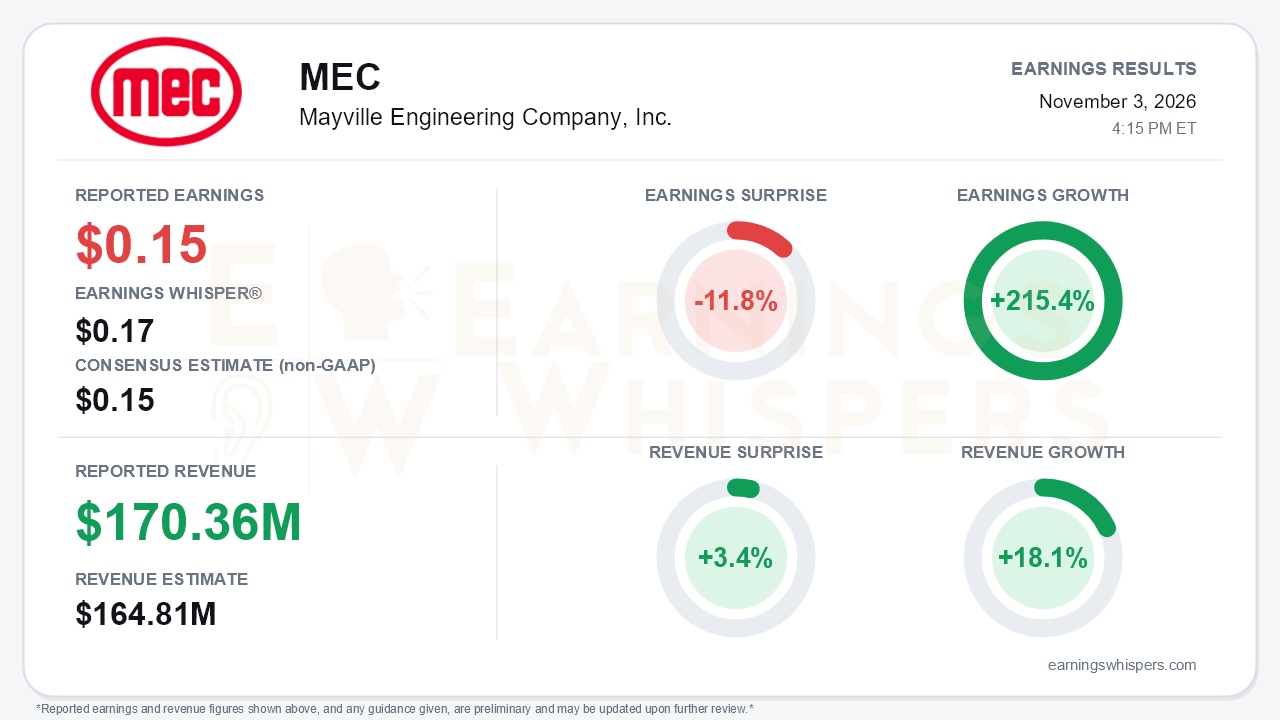
Mayville Engineering Company (NYSE: MEC) delivered a quarter that made the datacenter growth story bigger while pushing its profitability further out. Adjusted EPS of $0.15 matched the $0.15 consensus but fell short of the $0.17 Earnings Whisper number, an 11.8% miss against the whisper. Revenue of $170.36 million beat the $164.81 million consensus by 3.4% and grew 18.1% year over year. Earnings grew 215.4%. On a GAAP basis, MEC swung to net income of $0.4 million, or $0.02 per share, from a loss of $0.13 a year ago. That is the central tension. Demand is clearly running ahead of MEC's ability to convert it into margin and cash, and for the second straight quarter management lowered its profit expectations.
The quality of the quarter is mixed. Sequential margin progress was real. Adjusted EBITDA reached $17.0 million, a 10.0% margin, up from 8.1% in the second quarter and 4.5% in the first. Manufacturing margin, however, held flat year over year at 11.0% of sales. About $3.0 million of Datacenter & Critical Power (DCP) launch costs, outsourcing, and premium labor absorbed much of the volume leverage. Lower SG&A and interest expense did more for the bottom line than plant-level efficiency did, and CEO Jag Reddy acknowledged that operational efficiency "remained uneven." Cash is the bigger issue. Third-quarter free cash flow was negative $3.3 million, and the nine-month figure was negative $16.9 million, compared with positive $16.8 million a year earlier. Receivables and inventories together absorbed roughly $48 million of working capital year to date, while capex more than doubled.
The top-line mix strengthened considerably. DCP sales jumped 64.9% to $37.2 million, about 22% of revenue. Commercial Vehicle sales rose 34.7%, a sharp acceleration from the 3% growth in the second quarter. Construction & Access grew 9.3%. The weak spots deteriorated. Powersports fell 26.9%, compared with a 6% decline in the second quarter, and management expects offshoring to Asia to persist into 2027. Agriculture remains in a trough. Together, those two markets leave some plants underutilized just as DCP-focused facilities are short on labor. The company has 230-250 open positions, and welders are costing roughly $90 an hour plus per diem.
The forward-looking evidence pulls in two directions. On the positive side, the qualified DCP pipeline expanded to more than $200 million from more than $125 million, a level that had been flat for three calls. New customers, including a European switchgear OEM, drove most of the increase. MEC also booked $45 million of new DCP awards, bringing the total to more than $145 million over the past year. The company closed on the Thomson, Georgia facility, which together with planned equipment investment is expected to add about $50 million of annual revenue capacity by 2028. Management is also:
- negotiating capacity-reservation and customer-funded capex arrangements;
- beginning to charge DCP customers for delays and working capital;
- repricing industrial programs;
- planning $20-30 million of strategic exits in 2027 to free up capacity.
The guidance tells the less flattering story. Full-year adjusted EBITDA guidance fell to $48-52 million from $52-60 million. Free cash flow guidance moved to a use of $6-16 million, down from positive $7-15 million last quarter and positive $25-35 million at the start of the year. The revenue midpoint stayed at $635 million. About $20 million of roughly 20%-margin DCP revenue slipped into 2027 because of customer schedule changes. Management guided fourth-quarter margin below the third quarter's and framed the period as the trough. The path to a 15% margin, once expected at full run rate in the second half of 2026, now extends to late 2027 or 2028. Meanwhile, 2027 capex is guided to $40-50 million, and leverage remains at 2.9x even after an equity raise of about $94 million that lifted the diluted share count to 25.8 million from 20.4 million.
The market had already priced in much of this skepticism. Shares have fallen 43.7% since the open after the August report, to $16.06, and sit 28.9% below the 200-day moving average of $22.60. Investor sentiment moved further into negative territory, to -0.31 from -0.18, a meaningful but not extreme deterioration. The Earnings Whispers trend readings are mixed: price and AVWAP trends are negative, while momentum is positive.
The bottom line is that MEC's demand narrative has never looked stronger, but execution and cash conversion keep lagging it. The revenue beat and the expanded pipeline give bulls a credible multi-year story. Repeated guidance cuts, a timeline that keeps stretching, and rising capital needs give bears legitimate ammunition. Until margins inflect from the promised fourth-quarter trough and customer-funded capacity deals materialize, the stock is likely to be judged on delivery rather than demand.
Read our earnings preview for Mayville Engineering Company, Inc.: https://www.earningswhispers.com/article/MEC/21596
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-21 | |
| Oct-01 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-22 | |
| Jun-02 | |
| May-21 | |
| May-19 | |
| May-19 | |
| May-05 |
