LTC Properties Tests Whether Its Accelerated SHOP Pivot Can Lift Per-Share Earnings
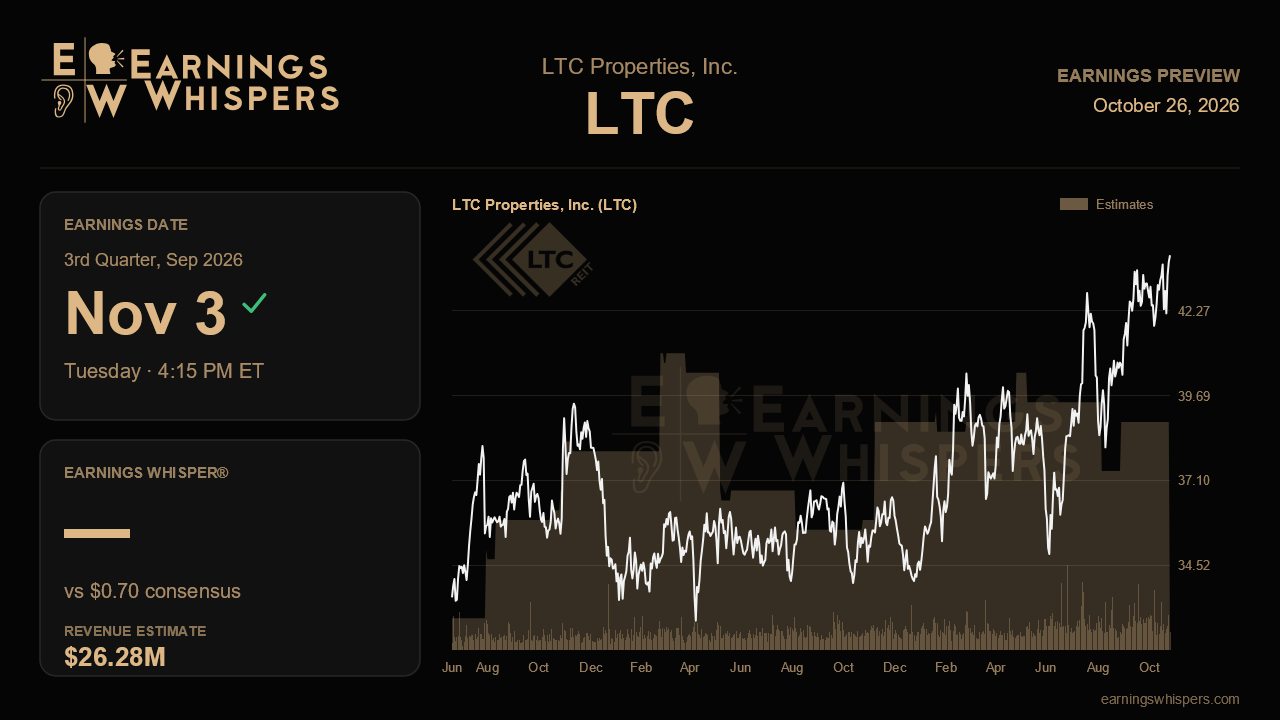
LTC Properties has spent 2026 rebuilding itself in real time, swapping skilled nursing leases and loans for seniors housing it operates through partners, and the market has applauded. The harder question for the third-quarter report, due after the close on November 3, is whether that strategic momentum is starting to show up where income investors ultimately get paid: per-share cash flow. Management raised nearly every operational target last quarter while holding its earnings midpoint flat, and this release is the first real check on whether that gap begins to close.
The Street is looking for $0.70 per share, up about 1.5% from $0.69 a year ago and slightly above the $0.68 posted last quarter. That is essentially flat growth, consistent with management's framing of 2026 as a transition year. The revenue consensus of $26.3 million implies a 62% year-over-year decline, but that comparison looks distorted by how gross operating revenue from the senior housing portfolio is presented rather than a sign of collapsing business, given last quarter's reported $98.9 million. Per-share funds from operations is the cleaner yardstick. Here the setup is notable: management narrowed full-year FFO guidance to $2.76 to $2.78, trimming the top of its prior $2.75 to $2.79 range, yet full-year consensus sits at $2.80, above the company's own ceiling. Analysts are effectively betting the larger acquisition program pays off faster than management has promised.
That bet rests on the execution story from the last call. LTC lifted its 2026 acquisition target by half, to a $900 million midpoint, said it expected $700 million closed by the end of September and $1.3 billion of gross SHOP assets, and projected SHOP reaching 40% of annualized NOI a full quarter early. It also more than doubled expected disposition and loan payoff proceeds to $730 million at a blended 7.3% cap rate, expanded its credit facility, and introduced a goal of 75% SHOP NOI by 2028. Confirmation that the September closings happened on schedule, that skilled nursing exposure has fallen toward the low 20s as a share of NOI, and that leverage stayed near the comfortable 4.2x level would validate the narrative. Any slippage in deal timing would matter, because management already cited timing as one reason earnings did not rise with the larger pipeline.
The operating fundamentals are the softer spot. Core SHOP occupancy of 89.7% was flat year over year and roughly 90 basis points behind internal projections in the first half, prompting management to drop its earlier assumption of a 150 basis point occupancy gain and lean on pricing instead, with a higher RevPOR assumption. Continued growth in core SHOP NOI beyond last quarter's $13.3 million, driven by rate without further occupancy erosion, would support that pivot. A weaker quarter, particularly in standalone memory care, which makes up close to a third of core units and tends to swing, would challenge it. Dilution is the other headwind: ATM share issuance pushed core FAD per share down to $0.70 from $0.71 a year earlier, and a new ATM program was expected this quarter. Updates on the $180 million Prestige loan payoff, pushed to an October 1 assumption on HUD timing, will shape fourth-quarter math.
Expectations have climbed. Shares are up 14.3% since the last report, nearly 15 points better than the S&P 500, and at $43.96 the stock is testing its post-earnings high of $44.30, above the prior quarter's $43.00 peak. Sentiment has edged up to 17.8% bullish from 14.2%, more optimistic but hardly euphoric.
The central issue is whether LTC can show that its faster SHOP buildout is translating into per-share growth rather than simply a bigger, more dilutive balance sheet. With consensus already above guidance and the stock near its highs, reaffirming the range may not be enough; investors will want signs that 2027 per-share growth is accelerating.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-21 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-01 | |
| Oct-01 | |
| Sep-25 | |
| Sep-22 | |
| Sep-02 | |
| Aug-14 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 |
