LTC Properties Edges Past Estimates As SHOP Deal Pace Outruns Organic Growth, With Earnings Payoff Pushed Toward 2028
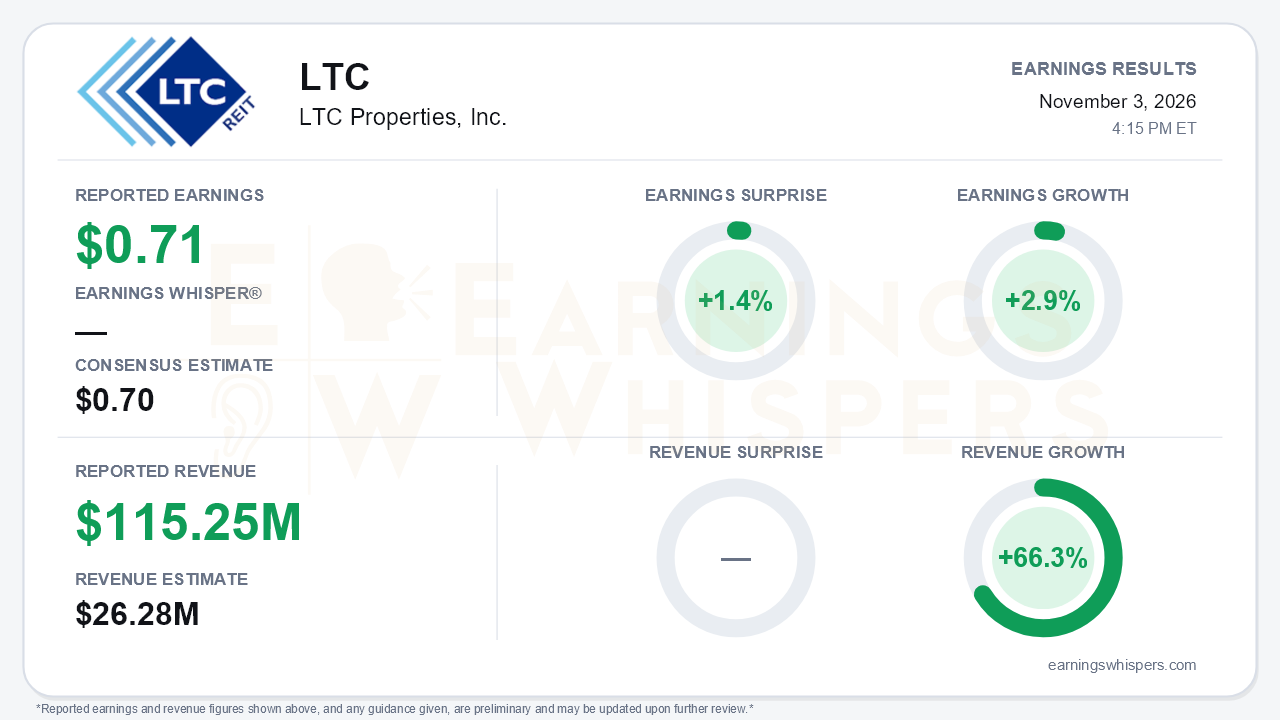
LTC Properties delivered a modest beat that matters more for its direction than its size. Core FFO of $0.71 per share topped the $0.70 consensus by 1.4% and rose 2.9% from a year ago. That is a real improvement over the second quarter, when Core FFO of $0.68 was flat year over year, so per-share growth has resumed, if slowly. Revenue of $115.25 million rose 66.3% and beat consensus by 338.5%. The size of that surprise says more about how the business has changed than about how far it outperformed. Resident fees from the seniors housing operating portfolio (SHOP) are now booked gross. They reached $70.5 million, compared with $22.2 million a year earlier, and the revenue consensus plainly did not reflect that structure. The central tension is that LTC's external growth engine keeps beating its own targets while organic SHOP performance and per-share guidance have not kept pace.
The headline GAAP figures need context. Diluted EPS of $6.39, compared with a $0.44 loss a year ago, came almost entirely from $324 million of gains on the sale of 34 triple-net properties for $464 million. The prior-year loss reflected a $41.5 million write-off of effective interest. Nareit FFO of $0.74 benefited from a $2.6 million lease termination fee, which management correctly stripped out of the core figures. Underneath, the portfolio is rotating quickly. SHOP NOI rose to $19.7 million from $4.8 million. Triple-net real estate NOI slipped to $42.2 million from $44.8 million as leased assets were sold. Diluted share count jumped to 54.2 million from 46.1 million. That roughly 17% dilution explains why 25% growth in total NOI turned into only a few cents of Core FFO growth. Core FAD rose just a penny to $0.73.
The call sharpened the contrast. Acquisition volume has run well ahead of plan. About $950 million has closed through October, and management now expects roughly $1 billion for 2026. Its guidance stood at $600 million earlier in the year and was raised to a $900 million midpoint in the second quarter. Another $200 million is slated for the first quarter of 2027, and management expects 2027 volume similar to 2026. SHOP should reach 50% of NOI by year-end, from 45% today. The organic side moved the other way. Core SHOP NOI guidance for the 27-property same-store pool was trimmed $0.5 million to a $54.5 million midpoint. That implies about 13% growth, below the 14% management had held all year. Slightly more than half of the cut came from a retroactive Medicaid rate cut at two standalone memory care communities. The rest came from a shift toward lower-rate care levels and unit types. This follows the second quarter, when the original occupancy-gain assumption had already proved too optimistic. Total SHOP NOI guidance also slipped about $0.5 million despite the larger acquisition pipeline.
The forward picture is where bears have legitimate ammunition. Management described new acquisitions as roughly earnings-neutral in year one when funded 70% with equity and 30% with debt. Entry cap rates are compressing toward about 6.5% from about 7%. The $180 million Prestige loan payoff has slipped three times: from July 1, to October 1, and now to November 24. That leaves an earnings drag that extends into 2027. Full-year Core FFO guidance of $2.76 to $2.78 and Core FAD guidance of $2.83 to $2.85 were reaffirmed, not raised, despite the extra deal volume. Management indicated that meaningful bottom-line growth is more of a 2028 story. One discrepancy also needs flagging. The release text cites reaffirmed GAAP EPS guidance of $8.08 to $8.10, while the guidance reconciliation table shows $7.80 to $7.82.
The offsets are substantive. Pro forma liquidity now exceeds $900 million, up from $648 million last quarter, aided by a new $500 million ATM program. Leverage stands at 4.4x and fixed charge coverage at 4.9x. Management reiterated expectations for mid-to-high single-digit private-pay rate growth into 2027, with moderate labor pressure. Additional funding sources are lined up: rent-reset property sales, a skilled nursing tenant's purchase option, and a large wave of senior housing loan maturities that should support deal flow.
The market has already rewarded the transformation narrative. Shares were at $45.80 heading into the report, up 19.1% from the open after the August release and about 15.7% above the 200-day moving average of $39.57. Price, momentum and AVWAP trend readings were all positive. Investor sentiment edged up from 0.14 to 0.17, a modest improvement that remains only mildly positive. That shows building but hardly euphoric expectations. With the stock extended, a report that trims organic guidance and defers earnings acceleration gives less room for disappointment than the surprise percentages suggest.
The bottom line is that LTC is executing its SHOP pivot faster and more aggressively than promised, and the quarter showed per-share growth finally re-emerging. However, scale is arriving ahead of profitability. Core SHOP guidance has softened, acquisitions are roughly neutral to earnings at first, and the Prestige delay pushes real FFO acceleration out toward 2028. After a nearly 20% run, investors are paying today for earnings growth that management itself places a year or more away.
Read our earnings preview for LTC Properties, Inc.: https://www.earningswhispers.com/article/LTC/21594
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Oct-21 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-01 | |
| Oct-01 | |
| Sep-25 | |
| Sep-22 | |
| Sep-02 |
