Limbach's Margin Reset Faces Its First Real Test As Street Eyes Sharp Earnings Rebound
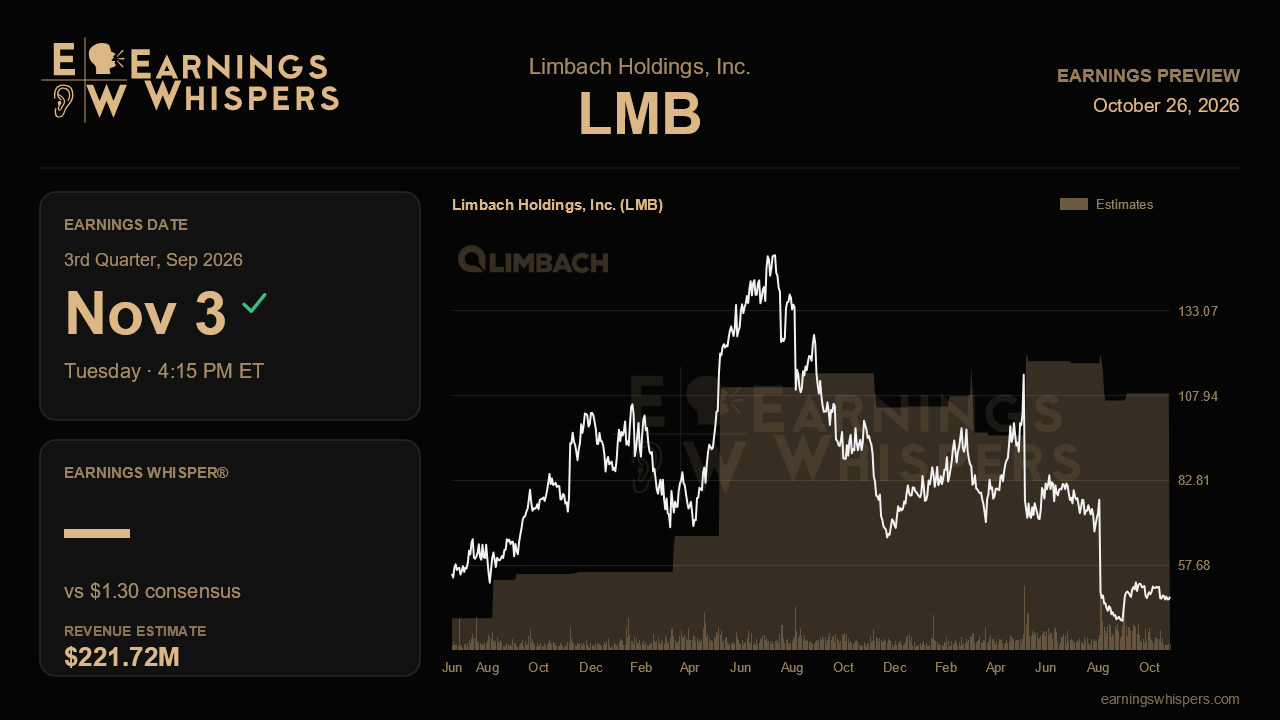
Limbach Holdings heads into its third-quarter report with an awkward split personality. Revenue keeps climbing, bookings keep arriving and management raised its full-year sales outlook last quarter. Yet the same call delivered a blunt profitability reset that sent the stock into a tailspin. The November 3 release, due after the close, is the first chance to see whether that reset was a one-time clearing of the decks or the start of a longer slide in the economics of the business.
The Street is asking for a lot. Consensus calls for earnings of $1.30 per share on revenue of $221.7 million, implying roughly 24% profit growth and 20% sales growth from a year ago. That is a steep climb from the second quarter's $0.64 in adjusted earnings on $173.5 million of revenue. Some seasonal lift is normal, since last year's third quarter produced $1.05 a share, but the estimate still assumes margins recover meaningfully from the 21.5% gross margin Limbach posted last quarter. Interestingly, the full-year revenue consensus of about $745 million sits below the low end of management's raised $760 million to $790 million range, suggesting analysts either have not fully updated their models or doubt the company can deliver the back-half volume it implied.
The margin story is where this report lives or dies. Management cut its full-year gross margin target to 23% to 24% from 26% to 27% and swapped its prior $90 million to $94 million earnings target for an adjusted EBITDA range of $78 million to $84 million. Hitting that new margin band requires the back half to run well above the second quarter's level. A third-quarter gross margin moving clearly toward 23% would validate the idea that the worst is behind the company. Another print stuck near 21% would raise uncomfortable questions about whether even the lowered guide is achievable, and whether the headwinds management flagged could bleed into 2027 as it warned.
The owner-direct business deserves equal scrutiny. That segment is supposed to be Limbach's higher-margin engine, but organic revenue fell 3.4% last quarter against earlier guidance for 9% to 12% growth, and management widened the mix target down to 70% to 80%. Healthcare and institutional customers are squeezing budgets and pushing back on price, partly because data center construction is inflating costs across the market. Any stabilization in organic owner-direct growth would go a long way toward restoring confidence. On the general contractor side, a thin $99 million backlog at midyear makes project timing a live risk, so updated backlog and bookings matter. Three straight strong bookings quarters totaling $616 million are the bull case's best evidence, and a fourth would help offset margin concerns.
The new growth vectors also need early proof points. The $30 million Simcor acquisition, a data center program management platform overseeing more than $8 billion of customer budgets, is meant to replicate the healthcare program model that turned about $3 million of advisory fees into roughly $60 million of bookings. Investors should want commentary on early pull-through opportunities, plus confirmation that Pioneer Power's roughly 150 basis points of margin improvement is holding. Continued strong cash generation, after last quarter's $18.7 million in operating cash flow, would reinforce balance sheet comfort.
The market has already passed judgment. Shares have fallen about 21% since the last report while the S&P 500 slipped only 1.4%, and the stock now trades around $48, in the lower half of its post-earnings range of roughly $41 to $62 and far below the prior quarter's $67 to $97 band. Sentiment has soured as well, with bearish readings rising from about 53% to 66%. That gloom lowers the bar on tone, but not on numbers given an ambitious consensus. Ultimately, the question is simple: can Limbach show that margins have bottomed and that the reset guidance is a floor rather than another ceiling waiting to be lowered.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Sep-23 | |
| Sep-03 | |
| Sep-01 | |
| Aug-21 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-14 | |
| May-27 | |
| May-18 | |
| May-05 | |
| May-05 |
