Limbach's Record Quarter Signals A Rebound, But Acquisitions Carry The Guidance And Skeptics Aren't Convinced
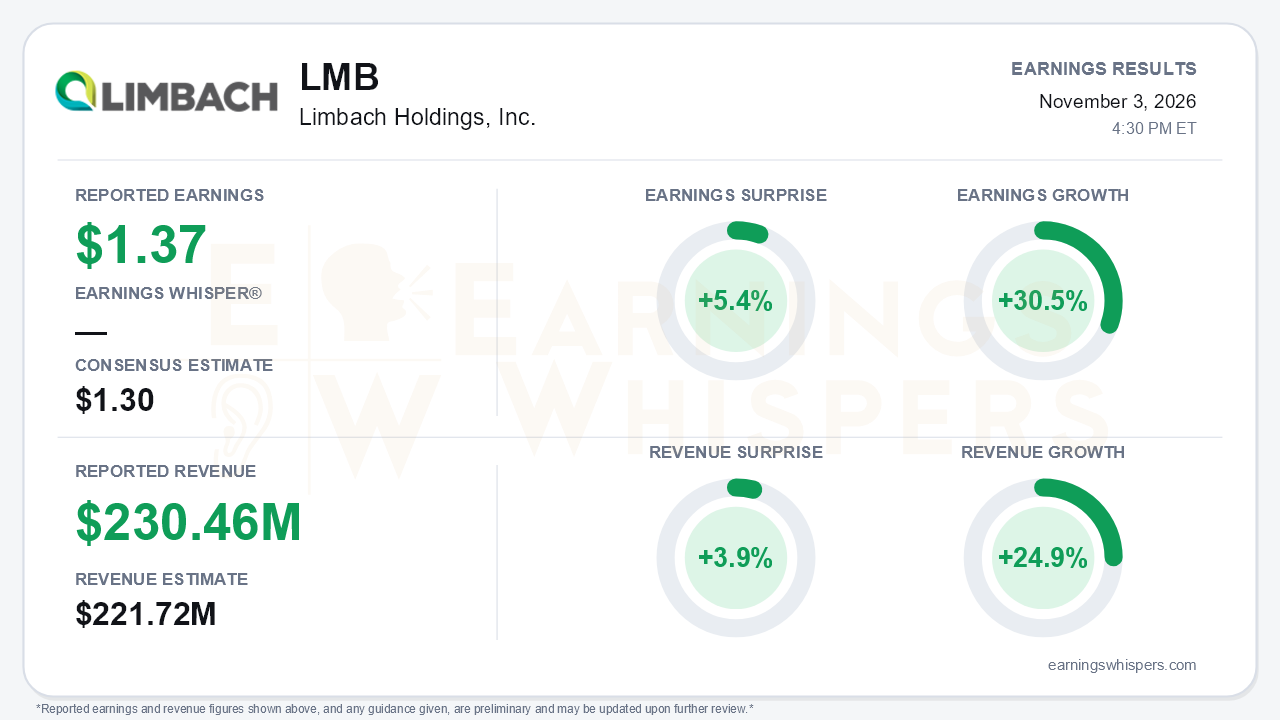
Limbach Holdings delivered the rebound quarter it needed after a bruising first half. Adjusted EPS came in at $1.37, beating the $1.30 consensus by 5.4% and rising 30.5% year over year. Revenue of $230.46 million topped the $221.72 million estimate by 3.9% and grew 24.9%. Revenue and adjusted EBITDA of $27.4 million were both company records, and the sequential improvement was stark: adjusted EBITDA nearly doubled from $13.9 million in the second quarter. The central tension is that the full-year ranges were held rather than raised. Management now expects to land "at or near the high end," but that positioning leans on two acquisitions the August ranges did not include. The quarter shows the business has stabilized. It does not yet show the core business outrunning its reset expectations.
The quality of the beat deserves scrutiny. GAAP diluted EPS rose only to $0.79 from $0.73, about 8%. The gap to the 30.5% adjusted growth comes mainly from add-backs: $3.3 million of acquisition and transaction costs, against just $0.1 million a year ago, and higher intangible amortization. Gross margin of 23.4% recovered sharply from 21.5% in the second quarter and 22.4% in the first, but it remained below last year's 24.2%. The driver was mix. Revenue from general contractor relationships (GCR), where Limbach works as a subcontractor and margins are typically lower, surged 84.7% and rose to 34.6% of revenue from 23.4%. The acquired businesses also carry thinner margins. Management targets closing that gap over two to three years. On a year-to-date basis, the damage from the first half is still visible: nine-month gross margin was 22.5% versus 26.4%, and adjusted EBITDA of $50.0 million trails last year's $54.6 million.
The organic picture improved but is uneven. The release shows total organic revenue up 14.4%, though nearly all of that came from GCR, where organic revenue rose 54.4%. Owner-direct relationship (ODR) revenue is the higher-margin work Limbach performs directly for building owners and the core of its strategy. ODR organic growth turned positive at just 2.2%, after declines of 3.4% in the second quarter and 5.4% in the first. The call analysis cited total organic growth of 6.6%, a figure that matches ODR's total reported growth rather than the release's organic disclosure. Investors should anchor on the release figures. Either way, the shift that matters is not a return to growth but where the growth came from. The higher-margin owner-direct franchise is only now inching back.
Demand indicators were the strongest part of the report. Bookings reached a record $311 million, a 1.4x book-to-bill ratio and the fourth straight quarter above 1.0x, up from $182 million in the second quarter. Management said the healthcare budget-timing problems flagged earlier in the year are easing. It expects work for two large national healthcare customers to convert to revenue in the fourth quarter. The tone moved from second-quarter contrition to what management framed as a message of progress. CYMCOR and 1901 add data center, electrical and Midwest exposure. Management acknowledged investor concern about the durability of AI and data center spending and said it is being selective.
The forward risks are concrete. Hitting the $78-84 million adjusted EBITDA range requires roughly $28-34 million in the fourth quarter, at or above the record just posted. The 6-10% ODR organic growth assumption sits well above year-to-date performance, which implies a steep fourth-quarter ramp. The balance sheet has also changed character. Total debt rose to about $154 million from roughly $36 million at year-end, and net leverage climbed to about 1.6x from 0.3x after funding both deals and a $10 million buyback. On the positive side, operating cash flow rose to $20.3 million, and liquidity stands at $164.2 million.
Investors are not buying the recovery yet. Earnings Whispers sentiment was already negative at the prior report, and it weakened further, from -0.53 to -0.68. Shares at $49.92 are down 18.7% since the open after the August report and sit about 30% below the $71.38 200-day moving average. They are also trading below the $51.31 average price the company paid in its buyback. The trend readings are mixed: sequential growth and AVWAP are positive, while momentum remains negative.
The bottom line is that Limbach produced a credible operational rebound, with record results, recovering margins and strong bookings. That is the kind of quarter turnaround skeptics were not positioned for. Bears still have legitimate ammunition, though. The guidance was held rather than raised, the core business is likely tracking nearer mid-range once acquisitions are stripped out, owner-direct organic growth is barely positive, and leverage has risen meaningfully. The fourth quarter will determine whether this was an inflection or simply a strong quarter flattered by deals.
Read our earnings preview for Limbach Holdings, Inc.: https://www.earningswhispers.com/article/LMB/21593
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Sep-23 | |
| Sep-03 | |
| Sep-01 | |
| Aug-21 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-14 | |
| May-27 |
