Lime's Sold-Off Shares Face A Test Of Its $340 Million To $360 Million Quarterly Outlook
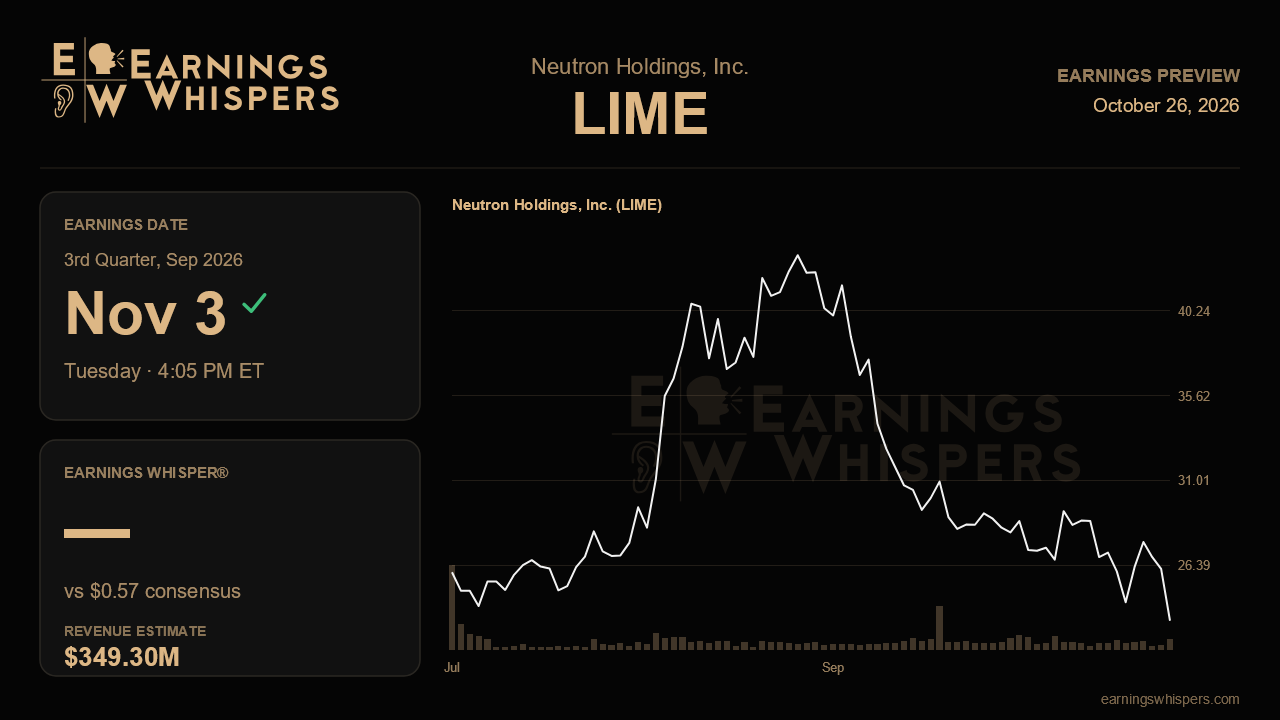
Few stocks head into earnings with a starker disconnect between what management has promised and what the market seems to believe. Neutron Holdings, which trades as Lime, has told investors to expect a meaningful step up in revenue this quarter. Yet the shares have lost roughly a quarter of their value since the last report, and sentiment has swung from almost uniformly upbeat to overwhelmingly negative. When the company reports after the close on November 3, the question is whether the numbers can close that gap or whether the market's skepticism was justified.
Wall Street is looking for earnings of $0.57 per share on revenue of $349.3 million. That revenue figure sits almost exactly at the midpoint of management's guidance of $340 million to $360 million. Analysts, in other words, have taken the company at its word for the quarter and are neither stretching for upside nor hedging for a shortfall. Reaching that level would mean roughly 15% sequential growth from the $304.2 million reported last quarter, which is a substantial jump in a single period. Delivering it would go a long way toward showing that the business has the momentum management described.
The earnings comparison needs more care. Last quarter's profit of $4.73 per share bears little resemblance to the current $0.57 estimate and is hard to treat as a recurring run rate. A drop of that size reflects a reset in expectations, not a collapse in the core business. The cleaner way to judge this report is on revenue conversion and on whether operating profit tracks the top line, not on the headline per-share change.
The more revealing tension lies in the full-year outlook. Management guided 2026 revenue to $1.04 billion to $1.10 billion, but the Street's annual estimate sits at the bottom of that range. Analysts accept the third-quarter target yet doubt the company will finish the year anywhere near the middle of its annual outlook. That makes the fourth-quarter commentary arguably more important than the quarter itself. A result near the top of the quarterly range, paired with a reaffirmed or narrowed annual outlook that lifts the low end, would challenge the bearish view directly. A quarterly number that merely meets guidance while the annual range is trimmed toward $1.04 billion would confirm what the market has already priced in, and possibly more.
The stock's behavior shows how little benefit of the doubt remains. At $23.36, the shares have fallen 25.7% since the last report while the S&P 500 slipped only 1.4%, an underperformance of more than 24 percentage points. The stock now trades below its post-earnings low of $23.96 and roughly 47% beneath the $44.38 high set after the last report. Selling on that scale, with no clear resolution, suggests investors are bracing for disappointment rather than positioning for a beat. Heavily bearish sentiment does not predict the outcome. It does mean a clean report could meet a market that is underexposed and quick to reprice, while a stumble would land on a stock already breaking down.
Ultimately, this report hinges on credibility. Management set a quarterly range that implies a sharp sequential acceleration and an annual range the Street only partly believes. If revenue lands squarely in or above the guided band and the full-year outlook holds, the growth narrative survives and the recent selloff looks overdone. If the quarter comes in light or the annual range moves lower, investors will conclude that the optimism of three months ago was misplaced.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-13 | |
| Aug-19 | |
| Aug-06 | |
| Aug-04 | |
| Jul-14 | |
| Jul-13 | |
| Apr-20 |
