Lime Tops Q3 Estimates, But Falling Revenue Per Vehicle And An EBITDA Guidance Cut Mark Its First Real Soft Spot Since The IPO
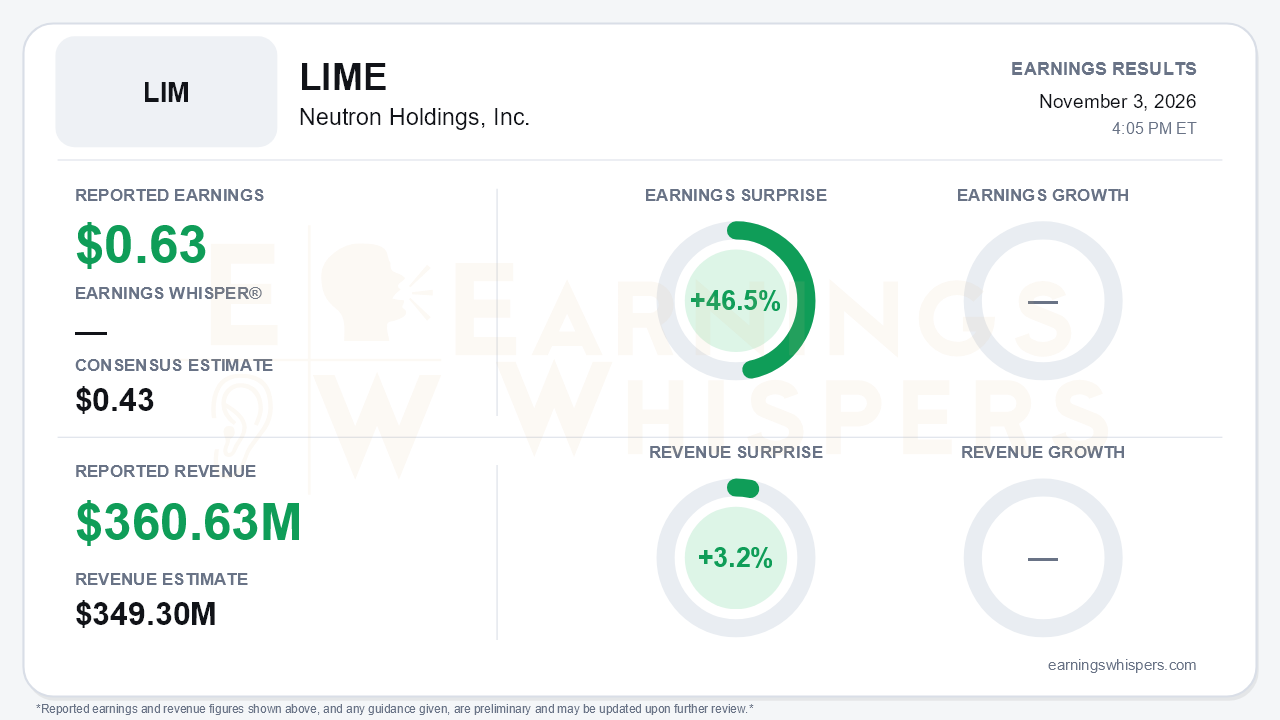
Neutron Holdings (Lime) cleared the consensus bar easily. Third-quarter EPS of $0.63 beat the $0.43 estimate by 46.5%, and revenue of $360.63 million beat consensus by 3.2%. Revenue rose 20% to a record and came in above the top of the company's own $340-360 million range. Trailing twelve-month revenue topped $1 billion for the first time. That is the headline. The more important story sits underneath it: Lime missed its own adjusted EBITDA guidance, revenue per vehicle turned negative, and management cut full-year profitability targets. This is the first clear softening since the company went public, and it arrived as investor confidence was already collapsing.
The quality of the beat deserves scrutiny. GAAP net income rose 41% to $44 million, but almost all of that improvement came below the operating line. Operating profit actually fell, from $68.9 million to $64.5 million. Gross margin compressed to 44.6% from 47.3%. Operating expenses grew about 31%, well ahead of revenue, with R&D up nearly 60% and stock-based compensation jumping to $15.7 million from $2.7 million. The year-ago quarter carried a $29 million loss tied to the fair value of the 2021 convertible notes. That charge is gone after the IPO recapitalization, which flatters the net income comparison. Diluted EPS of $0.63 also compares awkwardly with $1.01 a year ago because of the post-IPO share count, which is why a clean year-over-year EPS growth figure is not meaningful here. Adjusted EBITDA of $118 million rose 11% but fell short of the $120-130 million guide, and its margin slipped to 32.8% from 35.4% a year earlier. Free cash flow of $91 million remains solid. Still, it was lower year over year, and nine-month free cash flow is just $7 million after heavy fleet purchases.
The call shows where the pressure came from. Average operational fleet growth accelerated to 26%, or 447,000 vehicles, from 22% in Q2. Revenue per vehicle per day, however, fell 4.8% to $8.77, after rising 1.2% in Q2 and against management's plan of roughly flat. In plain terms, Lime is deploying vehicles faster than it is monetizing them. Monthly active user growth also slowed to 15.9% from 22.1%. Management blamed smaller, debt-funded competitors in Western Europe and the UK outside major cities, saying it chose not to match their pricing. It expects that pressure to persist through year-end. LimePrime adds a second source of price dilution through flat-rate pricing, even as it improves engagement. The tone shifted noticeably, from Q2's record-setting framing to a defensive "we've seen this movie before" discipline narrative.
The guidance picture contains a conflict worth flagging. The full-year revenue range of $1.04-1.1 billion was reiterated, and on that basis the outlook can be read as in line. Full-year adjusted EBITDA guidance, however, was cut to $253-255 million from $265-285 million. The Q4 outlook of $240-250 million in revenue and $43-45 million in EBITDA implies roughly 17% growth and only about an 18% margin, partly because of stepped-up reliability and city-tech spending in the off-season. Capex guidance fell to $172-177 million despite the larger fleet. The bull case rests on LimePrime, now backed by hard data. Subscribers take 8x the trips of pay-as-you-go riders, retain at about 3x the rate and generate about 2x the adjusted gross profit. Australia more than doubled, Canada is showing early traction, and the company has $453 million in cash with no debt. Lisbon's vote to ban shared e-scooters, however, is a reminder that regulatory risk is never far away.
The market had already moved against the stock before the print. Investor sentiment plunged from roughly neutral at -0.05 after the Q2 report to -0.95, close to the bottom of the scale. As of the pre-report snapshot, shares were down 28.2% from the open after the August report at $22.58. That is about 49% below the $44.38 high set on August 27 and just 2.3% above the $22.07 low reached on October 26. Both figures are also 52-week extremes. The stock still sits well above its 200-day average, but that average reflects limited post-IPO history and offers little reassurance. AVWAP trends remain negative.
The bottom line is that Lime delivered a headline beat with deteriorating economics underneath it. Fleet expansion and LimePrime are driving volume, but pricing, user growth and EBITDA execution all slipped, and full-year profit guidance came down. With sentiment already deeply negative and shares pinned near their lows, much of the disappointment may be priced in. A durable recovery, however, likely requires evidence that revenue per vehicle stabilizes once European competitive pressure eases.
Read our earnings preview for Neutron Holdings, Inc.: https://www.earningswhispers.com/article/LIME/21592
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-13 | |
| Aug-19 | |
| Aug-06 | |
| Aug-04 | |
| Jul-14 | |
| Jul-13 | |
| Apr-20 |
