Navitas Must Prove Its AI Data-Center Pivot As Stock Sinks Toward Post-Earnings Lows
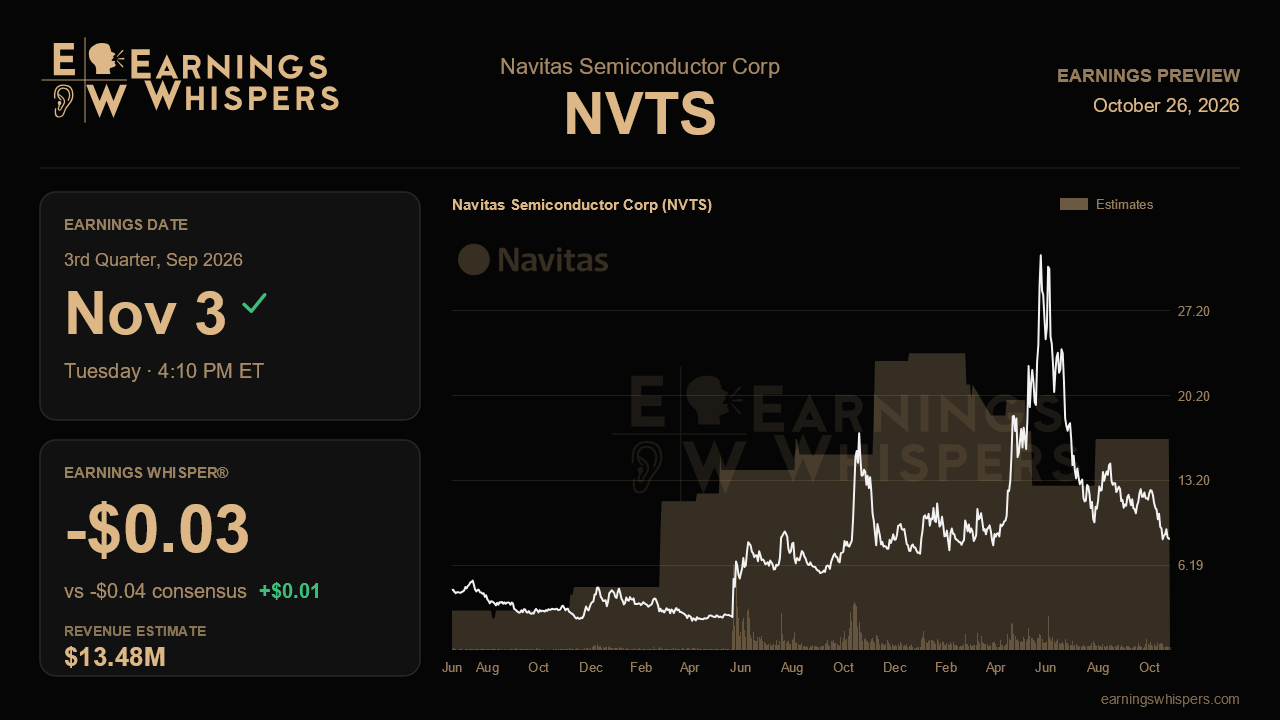
Navitas Semiconductor enters its third-quarter report with a striking disconnect. Management spent the last call describing a company whose transformation was running about a quarter ahead of schedule, with revenue guidance climbing call after call and AI infrastructure sales compounding at better than 50% a quarter. The stock, meanwhile, has fallen nearly 18% since that report while the S&P 500 gained 3.5%, and it now trades at $8.40, a fraction of the roughly $21.89 average price at which the company raised about $373 million. The upcoming numbers need to show that the operating story is real enough to close that gap.
The Street is looking for revenue of $13.5 million, which sits squarely at the midpoint of management's $13.0 million to $14.0 million guidance. That would be a 28% sequential jump from $10.5 million and roughly 33% growth from the $10.1 million posted a year ago, marking the return to year-over-year growth that management promised. Consensus calls for a non-GAAP loss of 4 cents a share, half the 8-cent loss of the prior quarter, while the whisper number of a 3-cent loss suggests a slightly better result is expected. The gap is a penny, so the earnings line is unlikely to drive the reaction. Because analysts have simply adopted the guidance midpoint, an in-line print offers little cushion; a result near the top of the range would do more to reinforce the claim that the company is ahead of plan.
The mix matters more than the headline. Management said AI infrastructure should exceed a third of revenue by year-end, while mobile and low-end consumer products are being deliberately allowed to fade toward insignificance. This quarter should show high-power and data-center sales growing fast enough to more than offset that shrinking base, and evidence that the multiple hyperscaler, merchant power and ODM programs slated to ramp in the second half are actually shipping. Gross margin, guided to 39.7% after stepping up from 38.7% to 39.5% over three quarters, is the cleanest check on whether the mix shift is working. A stall there would undercut the premise that the higher-power business is structurally more profitable.
Costs and new risks also deserve attention. Operating expenses were set to rise by $1.0 million to $1.5 million a quarter starting now after several flat periods, and management has said breakeven requires quarterly revenue in the high $30 million range, roughly triple the current guide. Updates on the MagnaChip silicon carbide licensing partnership, the new 1.2kV JFET line, the planned 6.5kV release and the GlobalFoundries 8-inch GaN transition will help show whether the expanded addressable market is turning into design activity. Investors will also want clarity on the Wolfspeed and Renesas patent suits and on timing of the 800V data-center architecture, which surfaced as a source of uncertainty on the last call.
The mood has soured noticeably. Sentiment readings have moved to 43% bearish from about 26% bearish ahead of the previous report, and the stock sits well below its 200-day moving average of $13.32, hovering just above its post-earnings low of $8.28 after failing to hold anywhere near the $14.95 high. The current trading range is also far lower than the prior quarter's $10.74 to $34.17 band, a sign that much of the earlier enthusiasm has been wrung out.
That pessimism lowers the bar for sentiment but not for execution. With $557 million in cash, survival is not the question; credibility is. If Navitas lands at or above the top of its range, holds margin near 40% and offers a fourth-quarter outlook that keeps the AI data-center ramp on track, the bearish drift could look overdone. If revenue arrives light or the data-center contribution keeps slipping toward 2027, the market will likely conclude that the transformation was further from finished than management suggested.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-21 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 | |
| Oct-02 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 |
