Navitas Matches The Whisper As AI-Driven Revenue Accelerates, But Claros Spending Pushes Breakeven Further Out
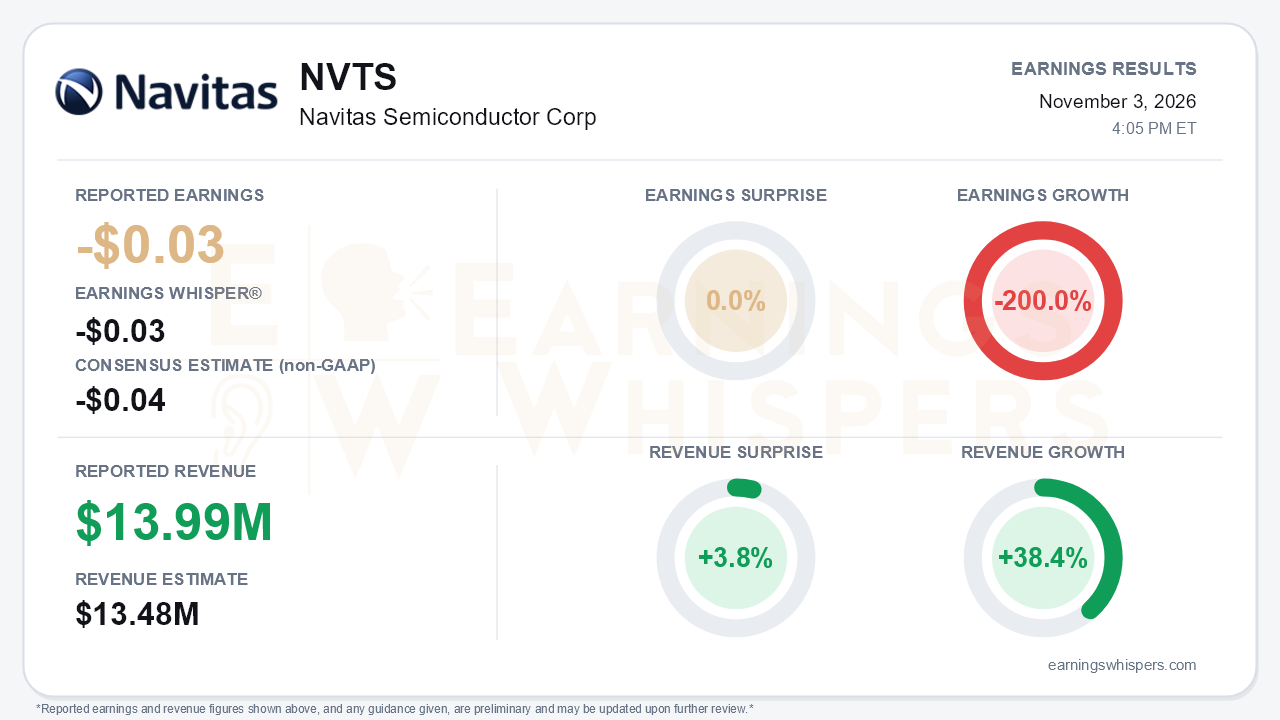
Navitas Semiconductor (NASDAQ: NVTS) reported a third-quarter non-GAAP loss of $0.03 per share. That matched the Earnings Whisper number and was a penny better than the -$0.04 consensus, an in-line result by Earnings Whispers' measure. Revenue was the stronger story. Sales of $13.99 million topped the $13.48 million consensus by 3.8% and grew 38.4% year over year, the company's first year-over-year growth since 2024. Management also guided fourth-quarter revenue above estimates. The quarter confirms that the high-power pivot is producing accelerating sales. It also shows that the cost of chasing the AI-power opportunity is rising faster than revenue. That is the central tension.
The growth trajectory is improving. Revenue rose 33% sequentially, up from 22% in the second quarter and 18% in the first. High-power revenue grew more than 50% from the prior quarter. Non-GAAP gross margin edged up to 40.0%, its fourth straight gain from 38.7% a year ago, and fourth-quarter guidance calls for 40.5%. GAAP gross margin jumped to 21.5% from 0.4% in the second quarter, but that improvement mainly reflects developed-technology intangibles becoming fully amortized, not a change in pricing.
The earnings comparison is less tidy. Earnings Whispers' normalized figures show earnings fell 200.0% year over year. The company's own reconciliation, however, shows the non-GAAP loss narrowing from $0.05 to $0.03 per share, a gap that likely reflects a different prior-year basis. On a GAAP basis, the net loss widened to $37.1 million from $19.2 million. Restructuring charges, $7.7 million of other expense, and higher stock compensation all contributed. The quality of the non-GAAP figure also deserves scrutiny. The non-GAAP operating loss was $10.9 million, and roughly $4.4 million of interest and dividend income from the cash pile closed much of the gap to the $6.9 million net loss. That cushion shrinks once the Claros payment is made.
The call kept a credible growth story intact and arguably strengthened it. Book-to-bill was roughly 2, and backlog now extends into mid-2027. Management raised its full-year growth outlook to about 7% from mid-single digits. Despite the near-total exit from mobile and low-end consumer, fourth-quarter revenue guidance of $16.0 million implies 119% year-over-year growth. AI infrastructure, spanning data centers and grid and energy, is expected to exceed 40% of fourth-quarter sales, up from more than one-third previously, and to more than triple in 2027.
Several catalysts support that outlook:
- a roughly one-million-unit GaN order for an 800V DC-DC brick;
- sidecar and 800V orders slated to ramp in the first half of 2027;
- an 800V-to-12V board collaboration with NVIDIA and a reference design with Microchip;
- a U.S. government 10kV SiC award.
Management's tone shifted from "transforming" to "transformed," and it guided to double-digit sequential growth through 2027.
Bears have legitimate ammunition on the cost side:
- **Operating expenses.** Non-GAAP opex is guided to $25 million in the fourth quarter, up from $16.5 million, largely because of Claros. Earlier commentary had framed a step-up of only $1 million to $1.5 million.
- **Breakeven.** The implied breakeven moved from quarterly revenue in the "high 30s" (millions) to the "low 60s," roughly four times the fourth-quarter guide.
- **Timing of the Claros payoff.** Claros roughly doubles the 2030 serviceable market estimate to more than $8 billion and supports a long-term blended gross margin target above 50%. But meaningful integrated voltage regulator (IVR) revenue is not expected until late 2028 or 2029, and that market already has competitors and long design cycles.
- **Cash and inventory.** Cash of $531.5 million falls to about $405 million pro forma. Inventory climbed to $32.4 million from $19.5 million on a TSMC buffer build.
- **Other risks.** Non-AI business is modeled flat for 2027, and the Wolfspeed/Renesas patent litigation remains unresolved.
The market has punished the stock ahead of the report. Shares closed at $7.93 on the eve of earnings, down 22.3% from the $10.20 open after the July report. That close was a hair above the inter-earnings low of $7.91 set the same day, 47% below the August 17 high of $14.95, and 40.3% below the 200-day moving average of $13.29. In effect, the stock round-tripped the entire summer AI-power enthusiasm. Investor sentiment remained negative but improved modestly, from -0.26 to -0.22, which suggests expectations were low rather than capitulating. Earnings Whispers trend readings are mostly negative on price and AVWAP, with momentum the lone positive reading.
The bottom line is that Navitas delivered what the bulls needed operationally: accelerating sequential growth, steady margin gains, a book-to-bill near 2, and a guide above estimates. The bill for that ambition is rising, however. A fourth-quarter opex jump of more than 50% and a breakeven now in the low-$60 million range per quarter push profitability well beyond the visible backlog. With cash shrinking to about $405 million after Claros, the investment case now rests on whether 800V and IVR adoption scales on management's timeline. A stock sitting at its quarterly low reflects that skepticism, not a verdict on the quarter itself.
Read our earnings preview for Navitas Semiconductor Corp: https://www.earningswhispers.com/article/NVTS/21604
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 4 hours | |
| 16 hours | |
| 17 hours | |
| Oct-26 | |
| Oct-21 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 |
