Navigator Faces Post-Hormuz Comedown As Earnings Expected To Fall By Half From Record
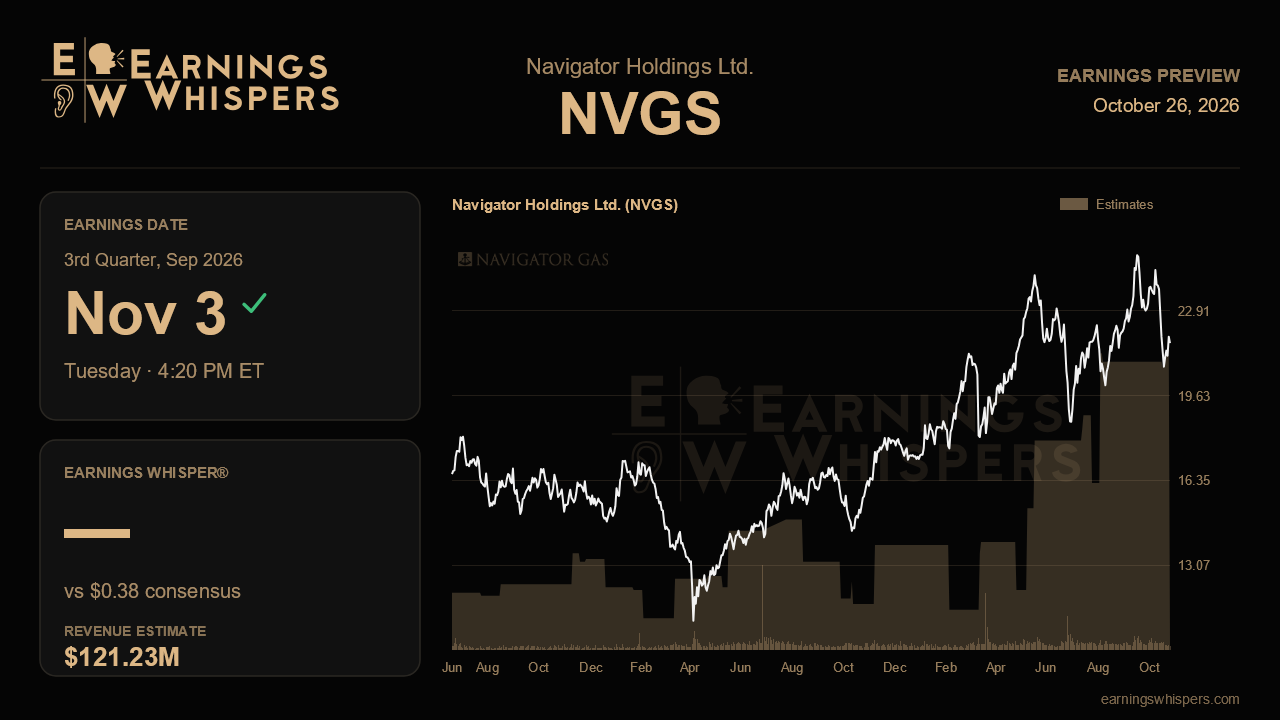
Navigator Holdings is coming off the best quarter in its history, and management has already said the next one will be softer. When the liquefied gas shipper reports after the close on November 3, the question is how much the third quarter normalizes after the Strait of Hormuz disruption pushed rates, terminal volumes and profits to all-time highs. Wall Street has priced in a steep comedown. The open question is whether the business settles on a higher plateau than it held before the spike.
Consensus calls for earnings of $0.38 per share on revenue of $121.2 million. That compares with $0.85 last quarter and is roughly 5.6% above the $0.36 earned a year ago. Revenue is expected to fall about 21% year over year. The drop likely reflects both rate normalization and the smaller fleet left after the sale of eight Unigas pool vessels. The earnings basis is not specified, which matters: management expected a book gain of roughly $65 million to $70 million from that divestment to land this quarter. If that gain shows up in reported results, the headline figure could look nothing like consensus. Investors should focus on underlying earnings power rather than the one-time boost.
Last quarter's call made the setup unusually clear. Time charter equivalent rates hit a record of about $33,900 per day, and utilization reached 90.8%. Ethylene terminal throughput jumped to roughly 374,000 tons as cargoes that would normally move through the Gulf were steered toward North America. Management then warned that rates and utilization would moderate, in line with seasonal patterns. It also said terminal volumes would ease. The ethylene arbitrage has narrowed and shifted from Europe to Asia, naphtha prices have fallen, inventories are being drawn down and European crackers are restarting. The 12-month charter rate benchmark had already slipped back to pre-Hormuz levels.
That gives investors specific yardsticks. A rate near or above the low $30,000s per day, compared with roughly $29,700 in the first quarter and $31,000 a year earlier, would suggest the moderation is orderly rather than a collapse. Terminal throughput holding well above last year's roughly 270,000 tons would support the view that higher US ethylene export demand is structural. The cost side needs watching too. All-in cash break-even rose to about $22,000 per day, and vessel operating costs climbed as fixed expenses were spread across fewer ships. A further rise would squeeze margins just as rates retreat. On the commercial front, progress beyond the fourth new terminal off-take contract would help. So would any sign that customers are moving past the short-term, keep-the-lights-on deals management described toward longer charters.
The balance sheet offers a steadier story. Net debt fell to 2.2 times EBITDA, all six newbuilds are financed, and the Unigas sale should bring in about $129 million of net cash. Repaying the $91 million precautionary revolver draw would be a sensible signal of confidence. With the payout policy now at 35% of net income and the fixed dividend stepping up to $0.08, the size of this quarter's capital return is itself a catalyst.
Sentiment has cooled. It has moved from slightly bullish before the last report to modestly bearish now, suggesting the market has accepted a weaker quarter. The shares are down 0.6% since the last report, slightly ahead of the S&P 500. At $21.66, the stock sits just above its 200-day moving average of $21.11. That leaves it in the lower middle of its post-earnings range of $19.72 to $25.48, well short of a breakout.
Ultimately, the report needs to show that Navigator's normalized earnings power, after the Hormuz premium fades and with a leaner fleet, sits meaningfully above where it stood a year ago. Stable rates, resilient terminal volumes and contained costs would support that case, while a sharp slide in any of them would suggest last quarter was mostly a one-off.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-20 | |
| Oct-16 | |
| Oct-09 | |
| Aug-07 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-31 | |
| Jul-22 | |
| Jul-14 | |
| Jul-03 | |
| Jun-18 | |
| Jun-15 |
