Navigator Gas Beats On A Soft Operating Quarter As Unigas Gains Inflate GAAP Profit And A September Rebound Sets Up Q4
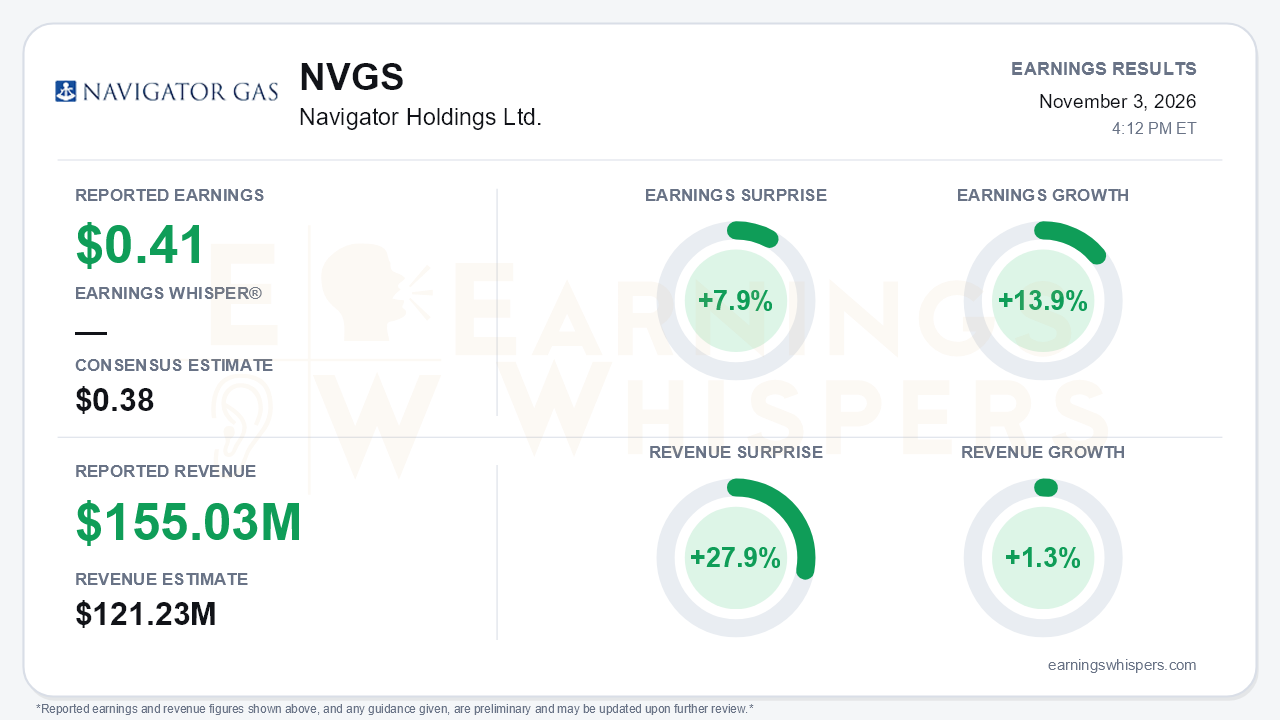
Navigator Holdings (NYSE: NVGS) beat third-quarter expectations, but the operating business behind the beat was weaker than in the second quarter. Adjusted EPS of $0.41 topped the $0.38 consensus by 7.9% and grew 13.9% year over year. Revenue of $155.03 million beat the $121.23 million consensus by 27.9%, yet it rose only 1.3% from a year earlier. GAAP net income attributable to stockholders more than doubled to $78.3 million, or $1.27 per diluted share, almost entirely because of $48.0 million in gains from the Unigas vessel sales. The central tension is that the third quarter was a genuine sequential step down. The quarter's exit rate and management's fourth-quarter outlook argue the dip was temporary.
The quality of the numbers deserves scrutiny on two fronts. First, the revenue beat owes much to pass-through costs. Voyage expenses jumped 74% to $35.0 million on higher bunker prices, which inflated gross revenue. Revenue net of voyage costs actually fell to $108.7 million from $121.8 million a year ago. Fewer available days after vessel sales cost about $9.0 million, and lower rates and utilization subtracted another $4.1 million. Second, the company reverted its adjusted-earnings definition to exclude vessel-sale profits. That change is the right one for judging the core business, and it shows a less flattering picture. Adjusted EBITDA fell to $67.8 million from $76.5 million a year ago and from a record $86.4 million in the second quarter. Year-over-year adjusted EPS growth leaned on a share count that shrank to 61.2 million from 65.8 million. Lower depreciation and capitalized interest also helped.
Operationally, every key metric slipped from the second quarter:
- Average TCE fell to $30,314 per day from a record $33,946.
- Utilization fell to 87.9% from 90.8%.
- Ethylene terminal throughput dropped to 264 kt from a record 374 kt, and Navigator's equity income from the terminal fell to $2.2 million from $7.1 million.
Management tied the weakness to customers pausing purchases in July and August as US-Iran diplomatic headlines circulated, which pushed utilization to roughly 85%. That pause reversed once Hormuz conditions failed to improve. Utilization recovered to 94% in September and held into October. On the call, management said ethylene spot rates had nearly doubled from June/July lows and that LPG semi-refrigerated rates were also firming. Ethylene flows shifted heavily toward Asia, reaching about 75% of cargoes by September versus essentially none in the second quarter, which more than doubled voyage time per cargo. Management guided fourth-quarter utilization, TCE and terminal volumes higher sequentially. That outlook is the core reason to look through the third-quarter dip.
The balance-sheet transformation may matter more than any single quarter's earnings:
- Debt fell $157.8 million in the quarter to $762.6 million.
- Net leverage dropped to 1.7x from 2.2x in the second quarter.
- Quarter-end liquidity reached $425.8 million.
- The 2026 all-in cash breakeven was trimmed to $21,720 per day.
- Another roughly $22 million in Unigas gains will land in the fourth quarter.
- The fixed dividend rose to $0.08, and the fourth-quarter capital return is set at $27.4 million versus $18.5 million in the third quarter.
- The first of six newbuilds delivers in December on a one-year charter at what management called "very healthy rates."
Bears still have legitimate ammunition. Management admitted visibility is "not super great" and is deliberately running a more conservative balance sheet. Much of the ton-mile tailwind depends on continued Hormuz disruption, and normalization would reverse it. Charterers are avoiding long-term commitments, leaving only about 34% of forward days covered by time charters. The 12-month assessment for ethylene-capable vessels fell $100,000 per month, and a smaller fleet means less cost absorption per vessel.
The market had already turned cautious before the report. Earnings Whispers investor sentiment slipped from roughly neutral (0.017) to modestly negative (-0.127). Shares at $20.23 are down 7.2% since the opening after the August report and sit about 4.5% below the 200-day moving average of $21.19. The company repurchased stock at an average of $21.50 during the quarter, above where shares now trade. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP negative, which fits a stock that has not yet resolved its direction.
The bottom line is that Navigator delivered a clean consensus beat on a quarter that was operationally soft and flattered by asset-sale gains and pass-through revenue. The investment setup has nonetheless improved: September and October activity, firming spot rates, lower leverage and rising capital returns all point to a stronger fourth quarter. Whether that holds depends heavily on a geopolitical backdrop management itself says it cannot see clearly, and investor sentiment and the share price reflect that uncertainty.
Read our earnings preview for Navigator Holdings Ltd.: https://www.earningswhispers.com/article/NVGS/21603
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-23 | |
| Oct-20 | |
| Oct-16 | |
| Oct-09 | |
| Aug-07 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-31 | |
| Jul-22 | |
| Jul-14 |
