Manitowoc's Record Backlog Faces Its Seasonal Test After Raised Guidance And A 30% Rally
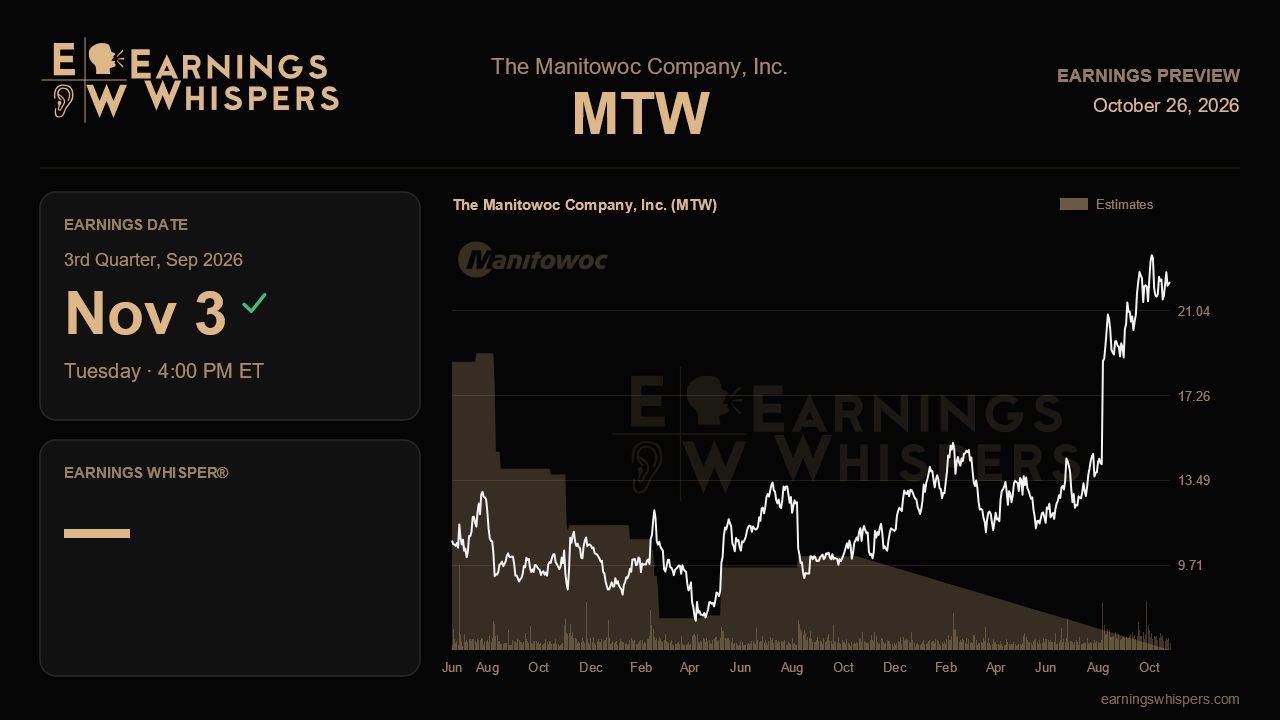
Manitowoc heads into its third-quarter report on November 3 with something it has not had for much of this cycle: momentum that management is willing to put a number on. After two straight quarters of simply reaffirming its outlook, the crane maker raised full-year guidance in the summer, pointed to record orders and backlog, and celebrated a trade ruling that slaps 12% to 20% tariffs on Japanese crawler cranes. The stock has rallied about 30% since then while the S&P 500 went nowhere. The question now is whether a seasonally soft quarter can keep that story intact.
The company now expects 2026 earnings of $0.80 to $1.20 per share on revenue of $2.30 billion to $2.40 billion, up from $0.45 to $0.90 and $2.25 billion to $2.35 billion. Adjusted EBITDA guidance moved to $150 million to $170 million from $125 million to $150 million, and free cash flow guidance edged up to $50 million to $70 million. Notably, the full-year consensus of $0.68 per share on $2.22 billion in revenue sits below the bottom of management's new ranges, suggesting either stale estimates or genuine doubt about the second half. Either way, the Street is not leaning on management's numbers, which leaves room for upside if the quarter lands cleanly. The year-ago comparison is modest: $0.14 per share on $553.4 million in revenue.
The math on the second half deserves attention. First-half adjusted EBITDA totaled roughly $69 million, with a weak $20 million first quarter followed by $49 million in the second. Hitting the $160 million midpoint implies about $91 million across the back half, or roughly $45 million a quarter, well above last year's $34 million third quarter. That is a demanding pace in a period when European summer holidays typically weigh on production. Investors should also remember that the second quarter included $12 million of a tariff refund in operating income, with only about $4 million more expected in the third quarter. Underlying margin progress, not one-time gains, needs to carry the result.
The backlog is what makes management's confidence plausible. It climbed from $667 million a year ago to $1.05 billion at midyear, and orders of $709 million rose 56% from the prior year, with July alone topping $200 million. Validation this quarter would look like orders holding near that level despite seasonality, backlog staying above $1 billion, and early signs that the crawler crane tariffs are translating into pricing or share gains in the U.S. A record in non-new machine sales, which reached $706 million on a trailing basis, would also reinforce the idea that higher-margin aftermarket work is cushioning cyclical swings. Challenges would come from a sharp backlog drawdown without replenishment, further softness in European self-erecting tower cranes tied to the EN standard transition, or freight and cost inflation linked to the Iran conflict and Strait of Hormuz disruptions.
Sentiment has cooled even as the stock has surged, with the bearish reading deepening to 28.9% from 21.6% ahead of the last report. Shares at $22.32 sit far above the 200-day average of $15.35 and comfortably inside a post-earnings range of $17.14 to $24.00, a dramatic step up from the prior quarter's $11.28 to $14.83 band. That rally means some of the good news is already priced, even if published estimates have not caught up.
With net leverage down to 2.6 times, below its 3 times target, Manitowoc also has fresh flexibility for buybacks or acquisitions, and any update on capital deployment could matter. Ultimately, though, the report hinges on whether third-quarter margins show the doubled profitability of the spring was a new baseline rather than a peak flattered by tariff refunds. If backlog conversion keeps EBITDA on the path toward $160 million, the raised outlook stands; if not, the 30% run could prove ahead of the fundamentals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Aug-19 | |
| Aug-07 | |
| Aug-06 | |
| Jul-23 | |
| Jul-23 | |
| May-26 | |
| May-05 | |
| Apr-21 | |
| Mar-31 | |
| Feb-11 | |
| Feb-10 | |
| Feb-09 | |
| Feb-09 |
