Manitowoc Raises Guidance Again On A $1.1 Billion Backlog, But Cash Burn Tempers A Strong Quarter
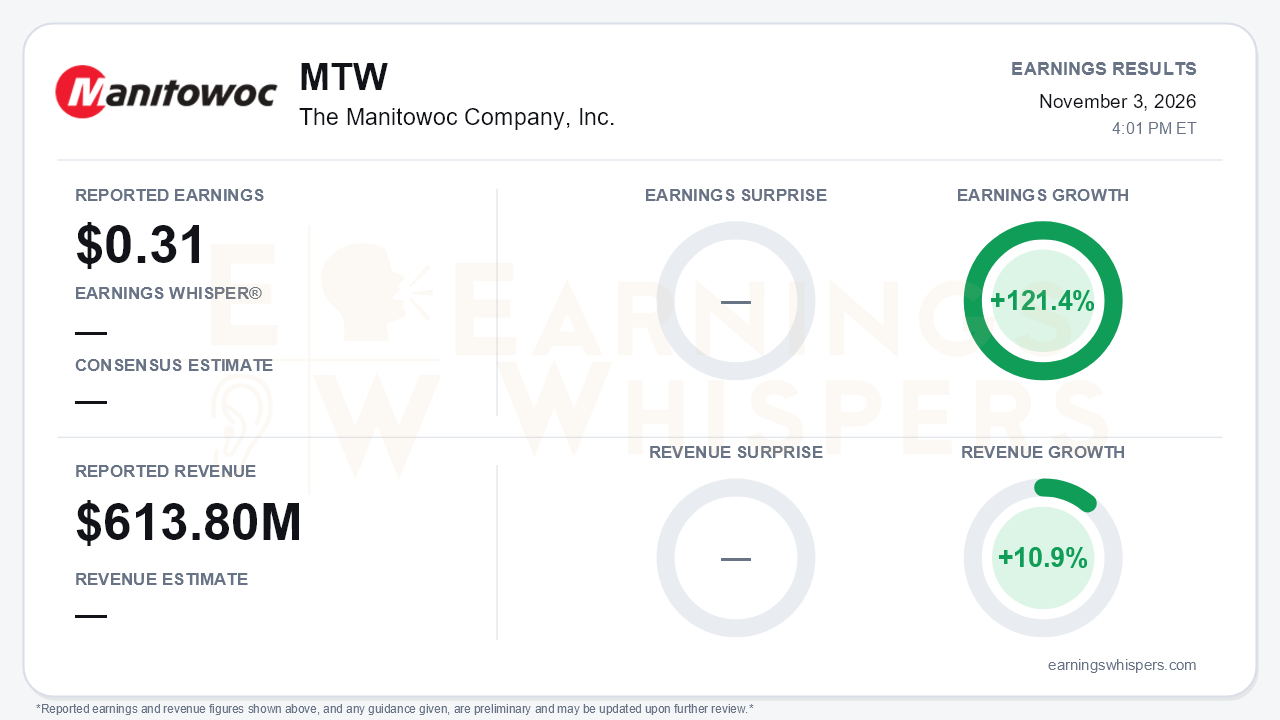
Manitowoc delivered the kind of quarter that crane-cycle bulls have been waiting for, though the cash flow statement tells a less tidy story than the income statement. Adjusted earnings came in at $0.31 per share, up 121.4% from a year ago, on revenue of $613.8 million, up 10.9%. GAAP EPS was $0.30 versus $0.14, so the adjustments were minimal. Orders rose 37.6% to $676.4 million, lifting backlog to $1,110.9 million, and management raised full-year adjusted EBITDA and EPS guidance for the second straight quarter. No consensus comparison was available. Earnings Whispers characterized the new outlook as a raise that remains in line with estimates, which suggests the Street had already credited much of this momentum. That is the central tension: demand and profitability are clearly improving, while free cash flow and the aftermarket business moved the wrong way.
The operating improvement looks genuine. Gross profit rose to $121.8 million from $102.6 million on an 11% sales gain. Engineering, selling and administrative expense grew only modestly, so operating income jumped to $31.8 million from $18.5 million. Adjusted EBITDA climbed 39.0% to $47.4 million, and the margin widened to 7.7% from 6.2%. The quality of the beat still deserves scrutiny. Roughly $4 million of the quarter's EBITDA came from a non-recurring IEEPA tariff refund. The margin also slipped from the above-8% level posted in the second quarter. All of the top-line growth came from new machines, because non-new machine sales fell 1.9% to $174.1 million. Management called aftermarket results lighter than hoped and blamed lumpy used-equipment sales, saying parts and service still grew. Even so, trailing aftermarket growth has slowed to 5% from 8% earlier in the year. That is a notable softening for the segment at the heart of the CRANES+50 strategy.
The demand picture is where the call was most convincing.
- **Regional orders:** Americas orders rose 60% and Middle East orders jumped 72%.
- **Europe:** European tower crane orders swung to a 20% gain after declining modestly in the second quarter.
- **Backlog:** Backlog has now expanded for four straight quarters, from $794 million at the end of 2025 to more than $1.1 billion.
- **Recent orders:** October orders of about $250 million topped the monthly readings cited on prior calls.
- **Capacity:** North American 2027 production of large crawlers and large rough-terrain cranes is sold out, with customers already inquiring about 2028 build slots.
Management's tone was its most confident of the year. The company laid out a path toward aspirational targets of $3 billion in revenue, a 12% EBITDA margin and a 15% return on invested capital. That bridge leans on recovering European tower crane earnings, about $50 million of price still to recapture, and a nuclear construction pipeline in Europe and the US.
Bears have legitimate ammunition on the balance sheet. Third-quarter free cash flow was negative $42.1 million, worse than negative $22.0 million a year ago and negative $6 million in the second quarter. Inventories have risen to $813.4 million from $683.9 million at year-end. Cash fell to $64.7 million, and net leverage edged up to 2.7x. The company left its $50 million to $70 million free cash flow guide unchanged on paper. On the call, however, management only described having line of sight to it, and hitting the midpoint requires roughly $90 million in the fourth quarter while inventory is being built for first-quarter deliveries. Other risks:
- European mobile crane orders fell sharply, reversing second-quarter strength.
- France was flagged as fragile.
- More than $30 million of tariff and inflation costs remain unrecovered.
- The fourth quarter faces a tough comparison.
The wide EPS range, $0.90 to $1.25 against nine-month adjusted EPS of $0.65, leaves room for meaningful variance.
The market had already moved well ahead of this report. Shares have rallied 38.9% since the open following the August release, to $23.80, and sit about 52% above the 200-day moving average. Price, momentum and AVWAP trend readings are all positive. Investor sentiment moved the other way, slipping further into negative territory to -0.40 from -0.22. That suggests growing skepticism that the stock's run has outpaced the fundamentals, even as the operating data improved.
The bottom line is that Manitowoc's order book, sold-out 2027 capacity and second guidance raise strengthen the case that the crane upcycle is real and broadening. The quarter was not clean, however. The EBITDA gain was flattered by a one-time tariff refund, aftermarket growth is slowing, and cash generation has deteriorated just as the company leans on working capital to fill its backlog. With the stock extended well above its long-term average and sentiment souring, the fourth quarter's cash conversion matters more than the earnings raise. Converting backlog into cash is now the test investors will apply.
Read our earnings preview for The Manitowoc Company, Inc.: https://www.earningswhispers.com/article/MTW/21602
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Oct-26 | |
| Oct-20 | |
| Aug-19 | |
| Aug-07 | |
| Aug-06 | |
| Jul-23 | |
| Jul-23 | |
| May-26 | |
| May-05 | |
| Apr-21 | |
| Mar-31 | |
| Feb-11 | |
| Feb-10 |
