Matador's Q3 Must Show Its Acquisition Spree Can Fund Both Growth And Debt Paydown
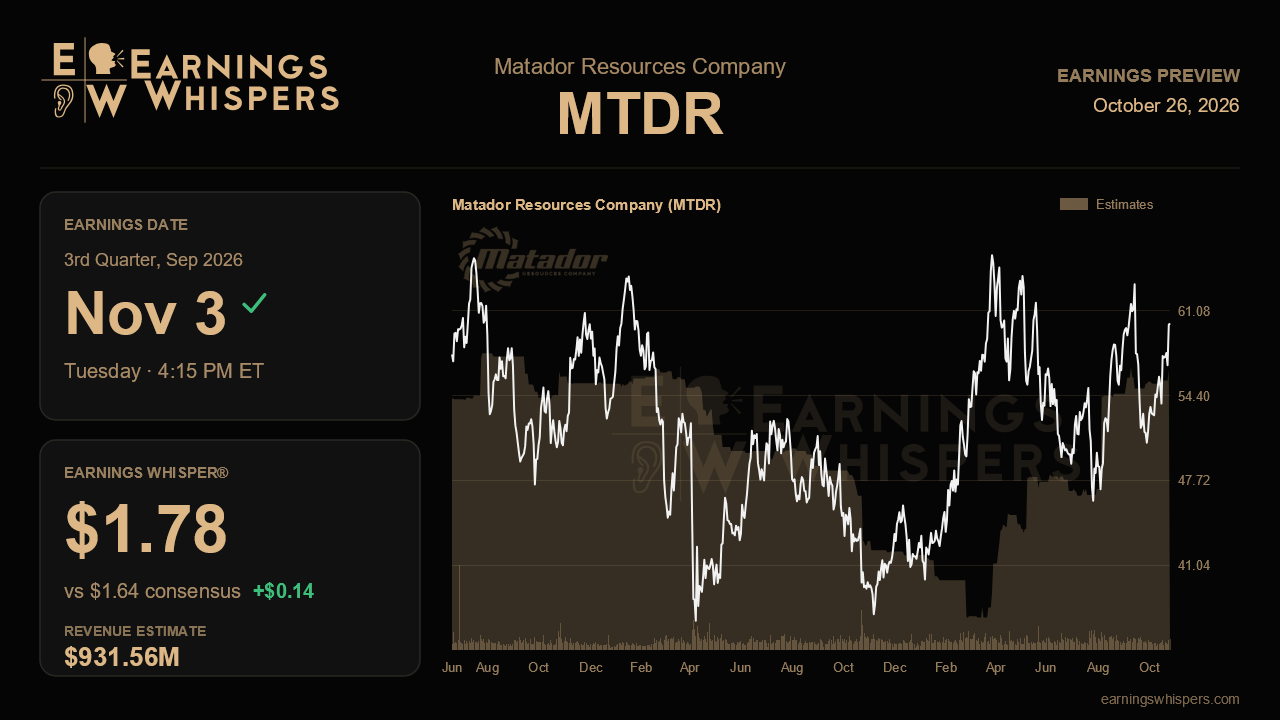
Matador Resources enters its third-quarter report with a stock that has already bought into management's new swagger. Last quarter the company traded its cautious, capital-discipline script for something closer to an offensive game plan, raising its 2026 oil growth target while trimming spending after a string of acquisitions. Shares have climbed about 21% since then while the S&P 500 slipped slightly. The question now is whether the numbers can keep pace with the story, and whether the debt that paid for it is shrinking as quickly as promised.
The Street's bar looks oddly modest on the surface. Consensus calls for earnings of $1.64 a share on revenue of roughly $931.6 million. That would be about 21% EPS growth from the $1.36 earned a year ago, on essentially flat revenue, down less than 1%. It would also mark a steep sequential retreat from the $2.61 and $1.19 billion posted last quarter. The Earnings Whisper sits higher at $1.78, a meaningful premium of about 8% over consensus, suggesting the more engaged crowd expects Matador to clear the published estimate with room to spare. Flat revenue paired with rising per-share profit puts the spotlight squarely on costs and margins rather than top-line expansion.
That is where last quarter's claims get tested. Management lifted full-year oil growth guidance to 4% to 7%, up from roughly 3% in its original plan and a 2% to 3% soft guide before that, and did so with about 1% less capital. It also pointed to roughly $900 million of free cash flow for the year after a near-record $303 million in the second quarter. Validation this time would look like production volumes tracking toward the upper half of that oil range, another strong free cash flow figure that keeps the annual target intact, and evidence that drilling costs are falling. The company has targeted around $600 per foot on its new federal acreage, well below the $795 midpoint in its 2026 plan. Any sign that well costs are drifting back up, or that oil growth is settling at the low end, would undercut the idea that Matador is growing more efficiently rather than simply growing bigger.
The balance sheet is the counterweight. The Cardinal midstream deal and the federal lease purchases were funded on the credit facility, which peaked near $1.25 billion before being paid down below $1 billion. Management framed the next 12 to 15 months as a period of digestion and deleveraging. A further meaningful drop in borrowings would confirm that free cash flow is doing the heavy lifting; a stalled paydown would raise doubts about how much of that cash is truly free. Smooth integration of Cardinal, where all field staff were retained, matters here too, since midstream ownership is central to the company's argument that it can manage regional gas bottlenecks.
Gas remains the swing factor. With roughly 100 rigs operating nearby, takeaway capacity is tight, and negative Waha pricing has been a persistent drag. The Hugh Brinson pipeline was expected online early with an uplift of about 50 cents per Mcf in gas realizations, so any update on timing and early pricing benefits could move estimates. Investors will also want progress on the Race Creek discovery, whose first well flowed more than 2,200 barrels a day but sits outside booked inventory.
Sentiment has edged slightly more bearish than before the last report, an interesting contrast with the stock's rally. Shares sit comfortably above their 200-day average near $54 but about 6% below the post-earnings high of $63.82, so this is not yet a breakout setup. Ultimately, the report hinges on one thing: proof that Matador's new assets are generating enough cash to sustain higher growth and cut debt at the same time. Deliver both, and the confident narrative holds. Deliver only one, and the rally may need to catch its breath.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-21 | |
| Oct-14 | |
| Oct-12 | |
| Oct-08 | |
| Oct-01 | |
| Sep-19 | |
| Sep-02 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-24 |
