Matador Resources Beats Handily As Gas Realizations Turn Positive, But Acquisition Debt And Falling Oil Prices Weigh On The Setup
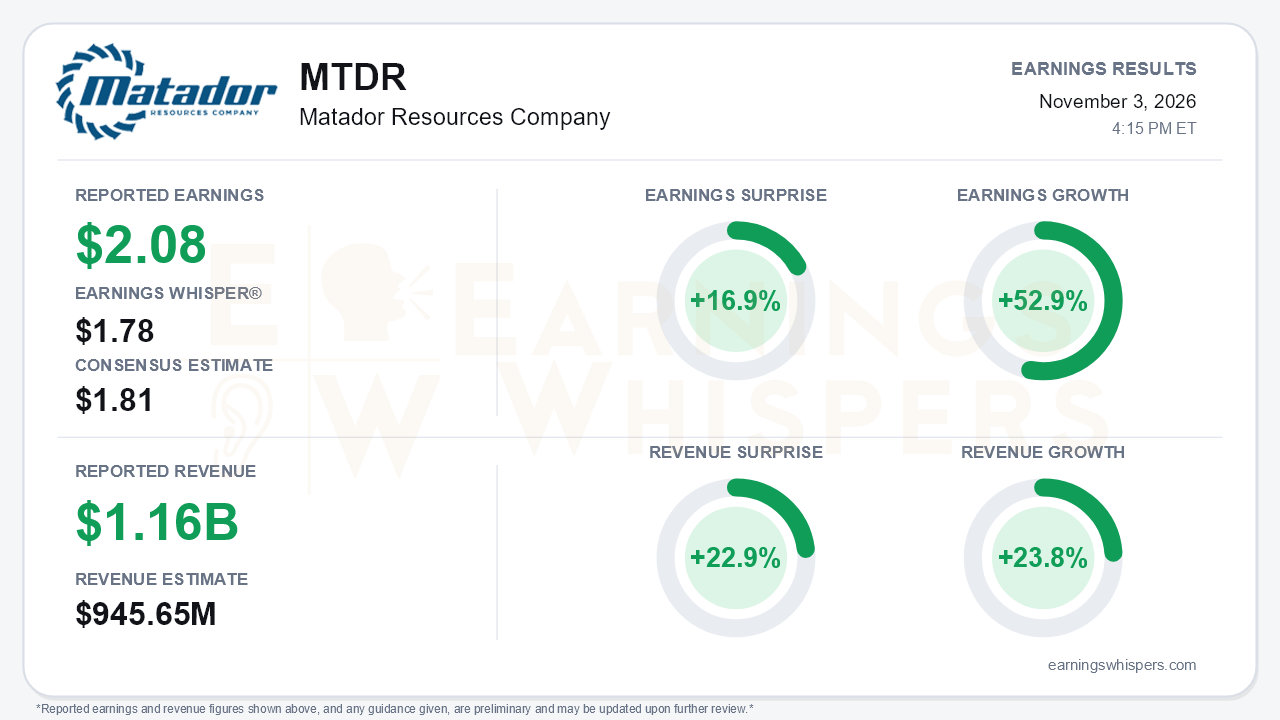
Matador Resources delivered a clean beat on the headline numbers. Adjusted earnings of $2.08 per share topped the $1.81 consensus by 16.9% and cleared the $1.78 Earnings Whisper number. Revenue of $1.163 billion beat the $945.65 million consensus by 22.9%. Earnings grew 52.9% year over year and revenue grew 23.8%. The most important development, though, was a pipeline rather than a price. Hugh Brinson came into service on September 1. It moved Matador's gas off the Waha hub and lifted realizations from negative $0.79 per Mcf in the second quarter to $2.99. Natural gas revenue swung from negative $39 million to $162 million. That is the operating shift the bull case has waited for, and it landed alongside record production. The central tension is that it also arrived alongside a heavier balance sheet and an oil tape that turned sharply against the company right before the call.
The quality of the beat deserves some scrutiny. Year over year, the comparison is flattering. Sequentially, adjusted EPS fell from $2.61 in the second quarter, and adjusted EBITDA slipped from $781 million to $738 million. Realized oil prices dropped 11% from the prior quarter to $87.25 per barrel. Hedges cut that to $74.84 after a $160 million realized derivative loss. GAAP EPS of $1.39 was below both the year-ago $1.42 and the second quarter's $3.15, reflecting a $67.7 million unrealized derivative loss and interest expense that rose to $80 million from $51 million. Operating expenses of $33.67 per BOE ran above the guidance midpoint, driven by Cardinal-related midstream costs. The $381 million capital spend, 10% below the guidance midpoint, partly reflects timing: roughly $28 million to $35 million is expected to slip into the fourth quarter.
Operationally, the trajectory improved on nearly every axis management controls. Production of 230,470 BOE per day was up 10% year over year and 3% above the guidance midpoint. Management attributed the outperformance to strong new-well results and an early twelve-well batch in the Ranger area. Full-year production guidance was raised to 223,000 to 224,000 BOE per day, the top of the prior range. Fourth-quarter guidance of 238,000 to 242,000 BOE per day includes about 10,000 BOE per day from the Paloma and Ridge Runner acquisitions. Well costs fell to $804 per lateral foot, and management cited about $640 per foot on wells near the federal and Paloma acreage. On the midstream side, combined Adjusted EBITDA reached a record $101.4 million. San Mateo added nine third-party customers through Cardinal and signed a new agreement to underwrite a 300 MMcfd processing plant at the Marlan complex. Adjusted free cash flow of $287.6 million was more than triple the year-ago $93.4 million.
The forward catalysts are substantial. Management offered a preliminary 2027 outlook of mid-single-digit growth or better. Gulf Coast LNG-linked gas contracts begin in early 2027. The Woodford discovery well has produced more than 140 MBO in about five months, beating the original high case. The dividend was raised 17% to $1.75. Bears still have legitimate ammunition:
- **Woodford** remains a single-well data point.
- **Midstream capex guidance** rose to $170 million to $190 million, with a multi-year Marlan build ahead.
- **San Mateo monetization** remains undefined.
- **Service-cost inflation** was acknowledged on the call.
- **Leverage** has risen. Credit-facility borrowings climbed to $951 million from $398 million at year-end, and a $647 million San Mateo term loan now sits in current liabilities.
The debt messaging is not entirely consistent. The release reiterates a $350 million to $400 million paydown target by year-end, notes $150 million already repaid, $50 million more than previously announced, and says leverage should approach 1.5x by year-end. The call analysis characterizes the pace as slower than the roughly $100 million per month implied last quarter, with full paydown pushed toward 2027.
The market setup is more complicated than the surprise implies. Investor sentiment entered the report negative and weakened slightly, from -0.40 to -0.43. That is a modest change, but it shows the beat has not won over skeptics. Shares closed at $54.31, up 9.0% from the $49.81 open after the August report. That leaves the stock essentially on its 200-day moving average of $54.54. The company's own release referenced a $60.88 close on October 30, and the call noted shares fell toward $50 as oil slid. The stock has therefore surrendered much of its recent run on macro grounds rather than company-specific ones. The Earnings Whispers trend signals are mostly positive on price, momentum and AVWAP, though sequential growth is only neutral, which fits the softer quarter-over-quarter earnings.
The bottom line is that Matador executed well: record production, structurally better gas pricing, falling well costs, a growing midstream franchise and raised guidance. The quarter marks a credible transition from acquiring to harvesting. However, sequential earnings declined, the balance sheet is more levered, and the stock's sensitivity to oil prices remains high. Investors need deleveraging to stay on pace and crude to stabilize before the operational gains can fully show up in the share price.
Read our earnings preview for Matador Resources Company: https://www.earningswhispers.com/article/MTDR/21601
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Oct-21 | |
| Oct-14 | |
| Oct-12 | |
| Oct-08 | |
| Oct-01 | |
| Sep-19 | |
| Sep-02 | |
| Aug-10 | |
| Aug-06 |
