Marqeta's Profit Machine Faces Its First Real Test As Cash App Drag Hits Gross Profit
For a year, Marqeta's investors have enjoyed a reliable formula: revenue grows at a respectable clip, costs grow more slowly, and profit guidance goes up every quarter. The third-quarter report, due after the close on November 3, is the first in which that formula has to work against a top line that management itself expects to slow sharply. The question is whether cost discipline can keep the earnings story intact while the Cash App and buy-now-pay-later headwinds that surfaced last quarter take their full toll.
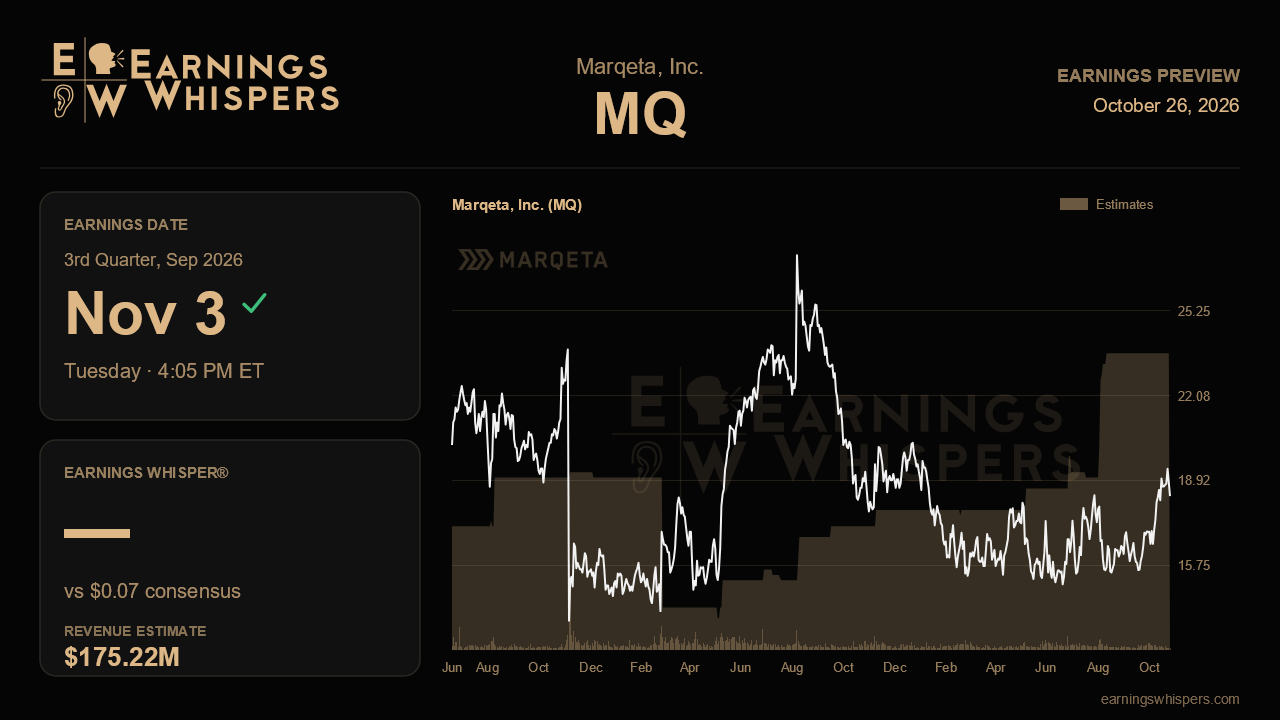
The Street is looking for earnings of $0.07 a share, matching the second quarter, on revenue of $175.2 million. The year-over-year comparison looks spectacular on earnings, since the company lost a penny a share a year ago, but revenue growth of about 7% is a sharp comedown and implies a slight sequential dip from the $176.0 million posted last quarter. Management guided third-quarter revenue to $173.1 million to $176.4 million, and consensus sits a touch above the midpoint, comfortably inside the range. That matters because analysts were modeling closer to $180 million before the guidance arrived, so the Street has already marked its numbers down to management's view. The company also trimmed the top of its full-year revenue range to $706.1 million while leaving the bottom untouched, a signal that the upside scenarios have narrowed even if the floor has not moved.
The more telling figure is gross profit, which management guided to grow just 5% to 7% in the third quarter, roughly ten points slower than in the second. Two forces explain the step-down. Block's long-discussed effort to diversify Cash App card issuance finally began showing up late in the second quarter and was set to accelerate in July, with management expecting little to no new issuance by year end. Separately, a BNPL customer began routing single-use virtual card volume to other providers, a development management admitted it had not anticipated. This report should show whether those drags are tracking to plan or spreading. Any sign that the BNPL load-balancing is broadening, or that on-demand delivery mix is eroding take rate beyond last quarter's roughly 10 basis points, would challenge the view that these are contained, idiosyncratic issues.
The offset is profitability. Adjusted EBITDA margin climbed to 21% last quarter, and full-year GAAP net income guidance has marched from about $10 million to the high-$20 million range across three calls. Operating expenses grew only around 12% in the second quarter, helped by vendor renegotiations and AI-driven headcount efficiency. Having raised profit targets so consistently, Marqeta has set a high bar: a quarter that merely holds guidance could read as the end of the upward revisions. Total processing volume, which has grown above 30% for four straight quarters, will show whether underlying demand remains healthy, while early traction from stablecoin card partnerships, European expansion through Banking Circle, and the three upcoming credit programs would support the argument that 2027 growth can recover once the Cash App comparison fades.
Sentiment has warmed, though it remains on the bearish side, with the reading improving to 28.8% bearish from 42.5% before the last report. The stock has slipped less than 1% since then, a hair better than the S&P 500, and at $18.33 trades in the upper part of its post-earnings range of $15.28 to $19.40, though not close enough to that high to call it a breakout setup. The market, in other words, has absorbed the slowdown without panic.
That calm rests on one premise: that Marqeta can keep expanding margins and lifting profit guidance even as gross profit growth bottoms out. If the company holds the line on expenses, reiterates its earnings outlook and quantifies the Cash App and BNPL drags without new surprises, the narrative survives. If those headwinds widen, the profitability story loses the cushion it has been leaning on.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Sep-25 | |
| Sep-11 | |
| Sep-09 | |
| Sep-09 | |
| Aug-27 | |
| Aug-25 |
