Marqeta's Profit Beat Comes With A Trimmed Revenue Guide And A Cash App Warning For 2027
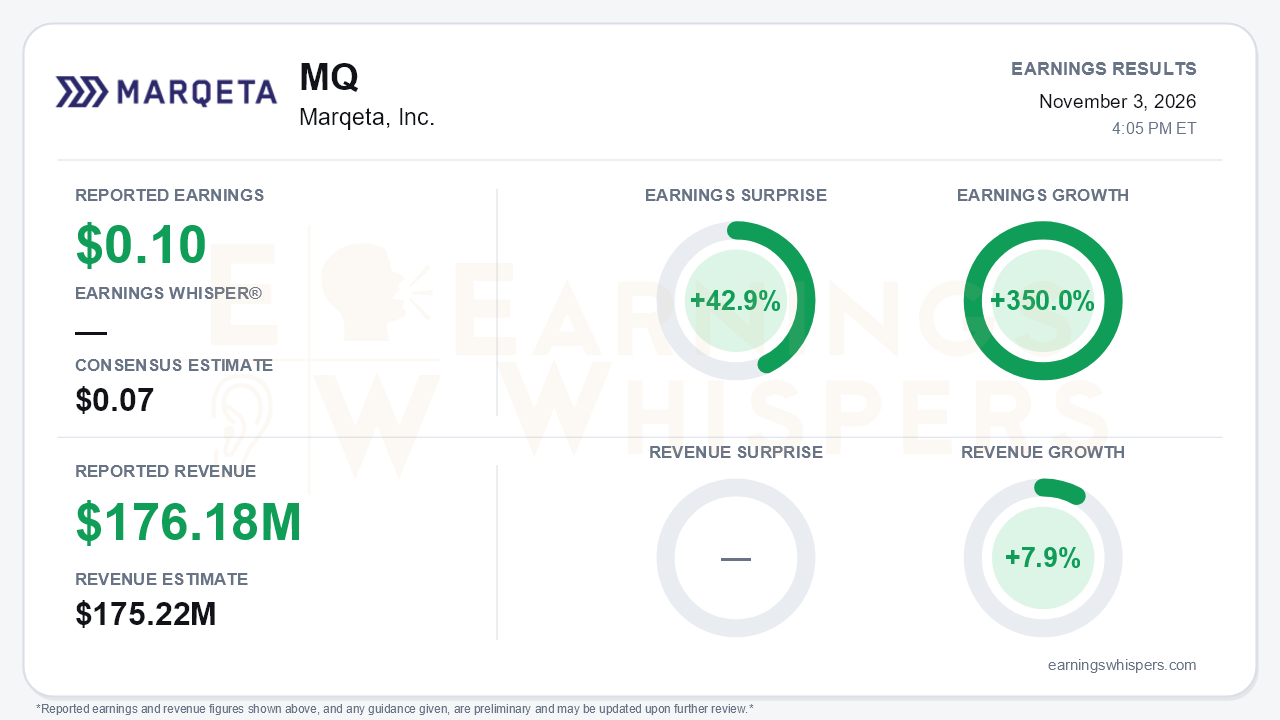
Marqeta (NASDAQ: MQ) delivered another profitability beat in the third quarter, but the top line kept slowing and management lowered its revenue outlook. Earnings came in at $0.10 per share, ahead of the $0.07 consensus by 42.9%, and up 350.0% from a year ago, when the company posted a loss of $0.03 per share. Revenue of $176.18 million edged past the $175.22 million consensus by 0.5% and grew 7.9% year over year. That is the central tension: the earnings engine is improving quickly, while the growth engine that justifies the platform story is losing speed, and the call offered little reassurance about 2027.
The quality of the quarter needs some unpacking. GAAP net income was $115 million, or $1.09 per diluted share, but that includes a $107 million non-cash tax benefit from releasing valuation allowances on deferred tax assets. The tax benefit is not operating income. It does signal that management and the auditors now consider sustained profitability more likely than not. Underneath it, the operating improvement is real. Operating income was $6.3 million, compared with a $10.4 million loss a year ago. Adjusted EBITDA rose 28% to $38.8 million, above the 20-25% growth management had guided. Adjusted EBITDA margin reached 22% of revenue and a record 32% of gross profit. Most of that leverage came from expense discipline rather than revenue. Total operating expenses fell 7%, compensation dropped 9%, and adjusted operating expenses held near $83 million. Gross margin slipped to 69% from 70%, and other income fell 34% as the cash pile shrank after $105 million of year-to-date buybacks.
The deceleration is broad. Total processing volume grew 29% to $126 billion and crossed a $500 billion annualized run rate. That is still impressive, but growth has slowed steadily, from 36% in the fourth quarter of 2025 to 33%, 32%, and now 29%. Gross profit growth fell to 7% from 17% in the second quarter and 19% in the first. This was within the guided range, but the drop is steep. Two verticals also cooled: lending/BNPL growth eased to about 40% from roughly 60% earlier in the year, and on-demand delivery slowed to high single digits. Expense management was the clear bright spot, accelerating for a fifth straight quarter to growth in the high 50s.
Guidance moved in two directions. Management cut fiscal 2026 net revenue growth to 11-12% from 12-13% and guided fourth-quarter revenue growth to just 3-5%. It attributed part of the cut to a customer contracting directly with its issuing bank, which removes pass-through revenue without affecting gross profit. Full-year gross profit growth was held at 11-12%, with fourth-quarter growth guided to 5-7%. Profit guidance rose again. Adjusted EBITDA growth is now expected in the low-to-mid 30s, and GAAP net income is projected at $135-140 million including the tax benefit, or roughly $28-33 million excluding it. That figure has risen every quarter this year. The bigger risk sits further out. New Cash App card issuance is expected to fall to little or nothing by the end of December, and management said the drag will be larger in 2027. It also declined to frame 2027 growth.
The new business wins give bulls something to point to. Marqeta migrated Square's credit card onto its platform, its first program on the American Express network and its fourth portfolio migration in 24 months, with more signed. It also launched Google Wallet for kids and Satispay's debit card in Italy, and expanded a stablecoin-card partnership with Coinbase. These wins diversify the customer base, but they are not yet large enough to offset the Cash App concentration risk.
Investor sentiment remained negative ahead of the report but improved meaningfully, rising from -0.42 to -0.28. The stock has made little net progress, up just 0.8% since the open after the prior report at $18.62. The path was volatile, though. Shares fell to $15.28 in mid-August, rallied nearly 22% off that low, and entered the report about 4% below the October 22 high of $19.40 and roughly 12% above the 200-day moving average. Most of the Earnings Whispers trend signals were positive going in, with momentum neutral. That means a recovered stock now meets a report pairing a profit raise with a revenue cut.
The bottom line is that Marqeta is becoming a credibly profitable company faster than expected, but it is doing so on a shrinking growth base. The margin story, rising profit guidance, and the tax-allowance release support the view that the business can sustain profits. The 3-5% fourth-quarter revenue guide, the steady slowdown in volume and gross profit growth, and an explicit warning about a larger Cash App drag in 2027 give bears legitimate ammunition. Until new programs like Square credit show they can restore gross profit growth, the stock's recovery rests more on cost discipline than on renewed demand.
Read our earnings preview for Marqeta, Inc.: https://www.earningswhispers.com/article/MQ/21600
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 5 hours | |
| Oct-26 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Sep-25 | |
| Sep-11 | |
| Sep-09 |
