Ovintiv Tests Its Permian Run-Rate Promise As Stock Presses Against Post-Earnings High
Ovintiv enters its third-quarter report with something energy investors rarely get: a story that improved on nearly every axis last quarter. Management lifted oil and condensate guidance, raised its Permian run rate, pushed leverage to its lowest level in over a decade and firmed up its buyback commitment. The stock has responded accordingly. The question now is whether the September quarter shows that this momentum is durable, or whether last quarter's beat came largely from one-off help that will be hard to repeat.
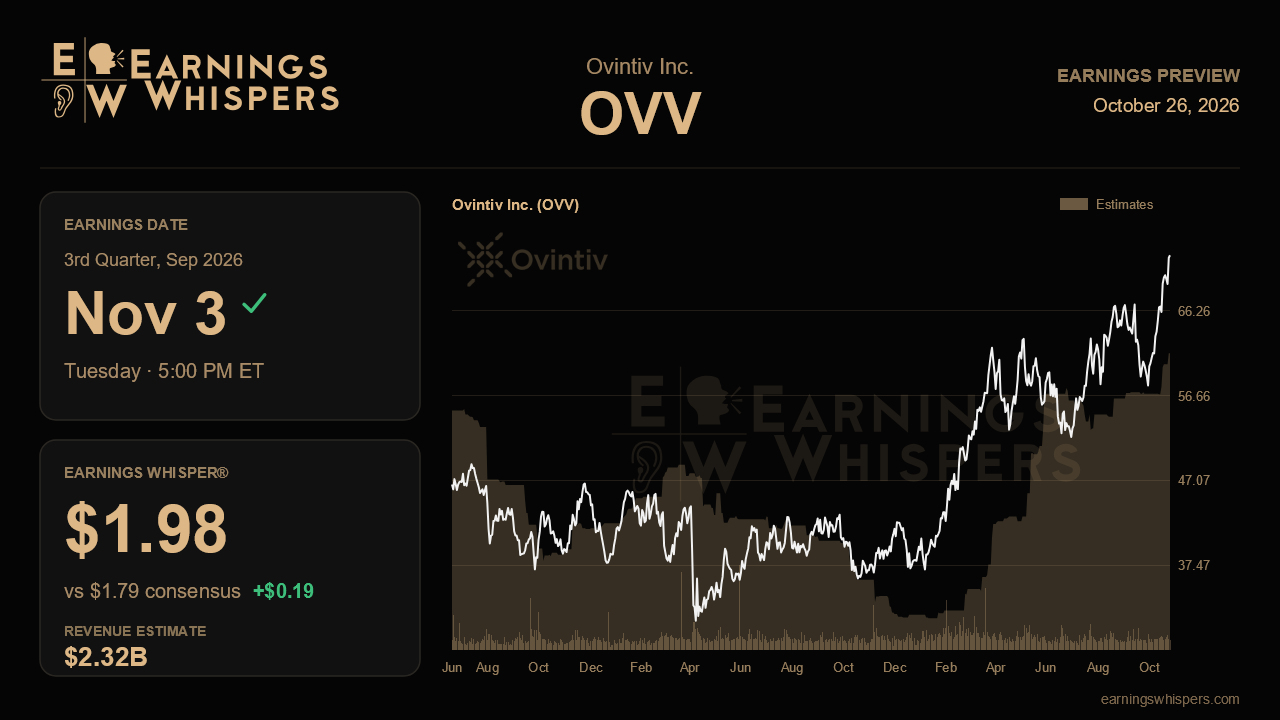
Wall Street expects earnings of $1.79 per share on revenue of about $2.32 billion. That EPS figure would be up roughly 74% from the $1.03 earned a year ago, with revenue up about 12%, which is strong growth by any standard. Consensus also sits slightly above last quarter's $1.74, even though projected revenue is well below the $3.01 billion reported then. The whisper number of $1.98 is meaningfully above consensus, suggesting the informal bar is closer to $2 than to the published estimate. A result that merely matches $1.79 could feel like a letdown.
The operational scorecard starts in the Permian. Management formally raised the go-forward run rate to 125,000 barrels per day after delivering 127,000 in the second quarter, crediting surfactant use on nearly all wells and base production running about 3% ahead of plan. Holding at or above 125,000 would validate that the productivity gains are structural rather than a quarterly spike. Anything that slips back toward the old 120,000 barrel framing would undercut the main reason guidance went up. Company-wide, oil and condensate volumes need to track the raised 210,000 to 212,000 barrel range, and NGLs should land near 84,000 barrels per day.
Montney is the second test. Gas volumes fell below the low end of guidance last quarter because of five stacked plant turnarounds that management says are now complete, so a clean rebound toward the 2.05 Bcf per day full-year gas target is the expectation. If volumes stay soft without a maintenance excuse, the explanation loses credibility. Condensate is a subtler story: higher prices trigger higher sliding-scale royalties, which shrink reported net volumes even as revenue rises. Readers should judge Montney on cash generation rather than barrel counts. Sulfur sales, which added about $40 million last quarter and were expected to stay strong, offer upside, while weak AECO and Waha gas pricing and persistent diesel inflation remain the cost and realization swing factors.
The financial narrative may matter most for the stock. Free cash flow of $682 million last quarter beat expectations, and with capital guidance held flat, another strong print would support the pledge to return more than 60% of free cash flow this year. Net debt below $3 billion and a Fitch upgrade to BBB give management room to lean harder on repurchases. Updates on potential S&P/TSX index inclusion, the roughly 100,000 Barnett acres that effectively replace a year of Permian drilling inventory, and early Western Canadian data center gas demand could extend the story, though management has deferred any 2027 growth decision amid caution about Chinese demand and OPEC supply.
Expectations have clearly risen. Shares are up about 18% since the last report, beating the S&P 500 by more than 14 points, and at $72.55 the stock sits well above its 200-day average and within a hair of its $73 post-earnings high, effectively testing a breakout. Sentiment is still slightly bearish but less so than a quarter ago. With the whisper above consensus and the stock at its highs, Ovintiv likely needs to show that Permian productivity is holding at the new run rate and that free cash flow is funding a growing buyback. If both hold, the improving narrative stays intact; if either wobbles, a crowded trade has little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 |
Energy Stock Vaults 78% As Middle East Outlook Turns Grim; Hovers In Buy Zone
OVV
Investor's Business Daily
|
| Oct-09 | |
| Oct-01 | |
| Sep-15 | |
| Aug-26 | |
| Aug-07 | |
| Aug-03 | |
| Jul-24 | |
| Jul-23 |
