Ovintiv Narrowly Misses On EPS As An Oil-Price Revenue Surge Meets Montney Volume Slippage, While The Logan Deal Shifts The Growth Story
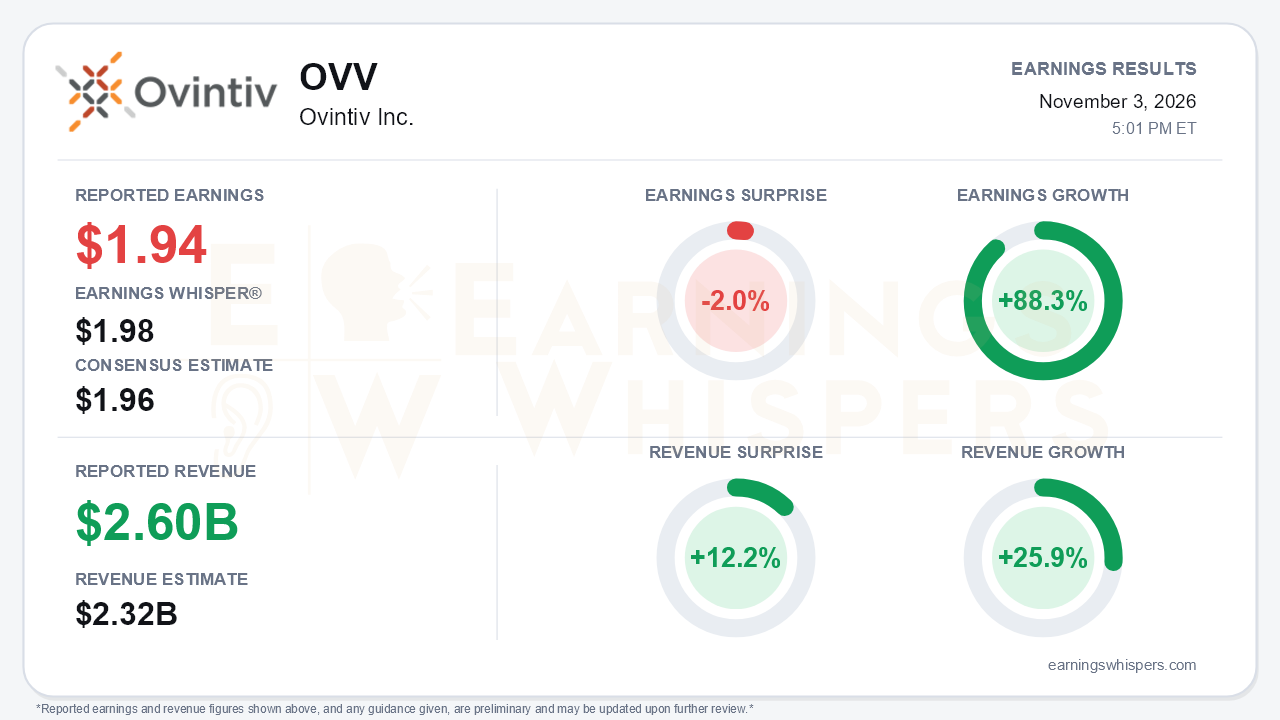
Ovintiv's third quarter looked strong on revenue and slightly soft on earnings. Earnings of $1.94 per share missed the $1.96 consensus by 2.0% and fell further short of the $1.98 Earnings Whisper number. Revenue of $2.602 billion beat the $2.32 billion consensus by 12.2%. Year over year, earnings grew 88.3% and revenue rose 25.9%, so the miss came against a backdrop of sharply higher profitability. The central tension is how that growth was produced. Nearly all of it came from commodity prices, not volumes. Meanwhile, the operating story is moving toward a larger, acquisition-fed Montney oil platform, even as current Montney execution falls short.
The quality of the quarter deserves scrutiny. Total production was 630.6 MBOE/d, essentially flat with 630.4 MBOE/d a year ago, and the liquids mix weakened:
- Crude oil fell to 121.2 Mbbls/d from 137.6 Mbbls/d.
- Other NGLs dropped to 83.2 Mbbls/d from 97.7 Mbbls/d.
- Plant condensate and natural gas rose.
The top line was instead driven by WTI averaging $85.79, against $64.93 a year earlier. Hedged oil and condensate realizations climbed to $80.69 per barrel from $64.49. Hedging cost Ovintiv some upside, with oil realizations at 94% of WTI including hedges versus 99% unhedged. Cash generation was the clear positive. Non-GAAP Free Cash Flow nearly doubled to $680 million from $351 million, and capital spending of $563 million came in below the guidance midpoint. GAAP net earnings were $549 million, or $1.99 per diluted share, modestly flattered by a $59 million unrealized hedging gain. Non-GAAP Adjusted Earnings were $536 million.
The call exposed the operational soft spot behind the earnings shortfall:
- **Montney shortfall:** Montney oil and condensate averaged 77 Mbbls/d, below the 80 to 85 Mbbls/d guide. Higher price-linked royalties and the third-party Albright gas plant outage, offline since July, were the causes. The outage alone cost roughly 3,000 bbl/d.
- **Company total:** Oil and condensate of 204 Mbbls/d landed just under the low end of guidance, a reversal from the second quarter's beat.
- **Fourth-quarter guide:** The Montney condensate outlook was lowered to 75 to 80 Mbbls/d, with the outage assumed to last through year-end. Total fourth-quarter oil and condensate is pegged near 205 Mbbls/d.
Against that, the Permian delivered 127 Mbbls/d against a 125 Mbbls/d guide. Management shifted $50 million of capital there to support a 125 to 130 Mbbls/d fourth-quarter target. Full-year guidance was maintained, with only NGL volumes nudged higher. Sulfur sales added roughly $75 million, up from about $40 million in the second quarter, though management expects that premium to moderate.
The forward-looking development that matters most is the roughly $890 million Logan Energy acquisition. It brings about 420 net locations, including 220 premium locations at roughly $1.5 million each, plus 20,000 BOE/d of production. Management expects about $60 million in annualized synergies, along with owned oil batteries and gas processing. A seventh Montney rig follows at close, and a possible eighth in 2027 would turn a stay-flat Montney program into an oil-growth program. That marks a clear departure from earlier sustainment-focused messaging. Combined with roughly 1,600 locations added in 2026 and $457 million of ground-game acreage purchases, the inventory story has strengthened materially.
The balance sheet is the trade-off. Net debt of $3.4 billion is well below the $5.2 billion at the end of 2025, but it is up from about $3.0 billion at mid-year. Management expects it to stay under $4 billion after Logan closes, without reinstating a formal target. Bears also have legitimate ammunition in the repeated warnings about 2027 service-cost inflation, with management referencing 2022.
Shareholder returns are moving in the right direction:
- **Third-quarter payout:** $467 million returned, or 69% of free cash flow, up from 63% in the second quarter.
- **Full-year target:** Returns are expected to exceed 60% of free cash flow.
- **Per-share growth:** Oil growth is now framed at 8% to 9% per share, versus about 4% at the second-quarter call.
- **Dividend:** Management openly discussed a possible base dividend increase.
The market setup is more constructive than the EPS miss implies. Shares closed at $66.43, up 8.2% since the open after the July report and about 14.9% above the 200-day moving average of $57.83. The Earnings Whispers trend signals lean positive on price, momentum and AVWAP, while sequential growth is neutral. That fits a quarter in which pricing, not production, drove the gains. Investor sentiment barely moved, improving from -0.0787 to -0.0715 and remaining slightly negative. Investors appear to own the stock for its cash flow without fully embracing the story.
The bottom line is that Ovintiv delivered a price-driven quarter with record-pace free cash flow, rising buybacks and a meaningful inventory upgrade through Logan. However, the small EPS miss and Montney volume shortfalls show that execution has not kept pace with the bigger growth narrative. Investors should watch three things: whether the Albright outage resolves, whether Logan's integration lifts Montney oil volumes on schedule, and whether net debt stays contained as 2027 cost inflation arrives.
Read our earnings preview for Ovintiv Inc.: https://www.earningswhispers.com/article/OVV/21608
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 |
Energy Stock Vaults 78% As Middle East Outlook Turns Grim; Hovers In Buy Zone
OVV
Investor's Business Daily
|
| Oct-09 | |
| Oct-01 | |
| Sep-15 |
