Ouster's Rev8 Ramp Faces Its Proof Point As Shares Sit Near Post-Earnings Lows
Ouster heads into its third-quarter report with an odd disconnect. Three months ago management sounded more confident than at any point this year, describing its Rev8 sensor as moving from launch to volume production with several million-dollar-plus orders in hand. Since then the stock has lost more than a third of its value. The report, due after the close on November 3, has to show that the operating story still holds even though the share price has stopped giving it credit.
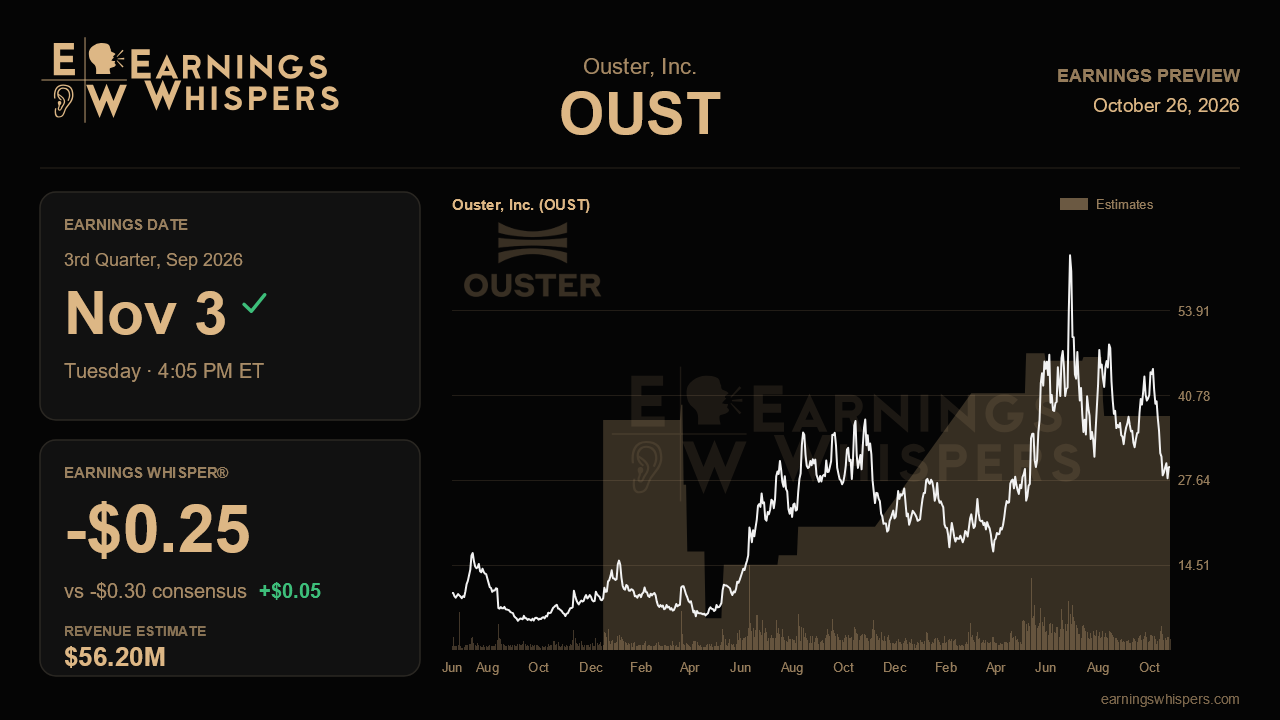
The Street expects revenue of $56.2 million, up about 42% from $39.5 million a year ago. That sits just above the $56 million midpoint of management's $54.5 million to $57.5 million guidance. When Ouster issued that range, it came in below the roughly $58.6 million analysts had been modeling, and estimates have since been pulled back to fit inside it. Consensus calls for a loss of 30 cents a share, an improvement from the 37-cent loss a year earlier but wider than last quarter's 26-cent loss. The whisper number of a 25-cent loss is somewhat less pessimistic. It suggests some investors think the margin reset and higher spending will hurt the bottom line less than published estimates assume.
Sequential growth is the first thing to check. Second-quarter revenue reached a record $54.6 million, so the guidance implies only modest growth from that level. Management also said volume production of Rev8 would not reach full scale until the end of the third quarter. That makes this the bridge quarter in a ramp weighted toward the back half of the year. Several results would support the story. Sensor shipments should keep climbing from the record 17,000 units last quarter, and LiDAR units should keep growing at a pace near the 70% rate reported in the second quarter. Management should also give a clear update on converting the orders from the heavy machinery maker, the autonomous agriculture developer and the AV provider into recurring production volume. Progress on the Utah and New Jersey transportation deployments, and any first revenue tied to Build America Buy America eligibility, would show that smart infrastructure is becoming a durable source of demand. On the other side, a result at the low end of guidance, flat shipments or vague language about when Rev8 reaches full rate would suggest the ramp is slipping.
Gross margin is the second key test, and it needs careful framing. Last quarter's 49% figure included roughly 10 points from a one-time refund. Management has already pointed back toward the high 30s and repeated its 35% to 40% long-term target. A print within that band should not be read as deterioration. A figure below 35% would raise harder questions about whether early Rev8 production carries a heavier cost burden. Operating expenses are expected to rise 5% to 8% year over year as Ouster adds capacity at Benchmark and Stereo Labs. Investors will want those costs to line up with real volume, not just capacity expansion past 100,000 units a year.
The balance sheet is no longer a worry after the July raise. However, about $290 million in combined ATM and follow-on funding expanded the share count to roughly 72 million, and that dilution likely explains part of the stock's slide. Sentiment has improved modestly, moving from slightly bearish before the last report to slightly bullish now. The chart tells a gloomier story. At $29.71, the shares are below their 200-day moving average of $32.31 and close to the $27.35 low of their post-earnings range, far from the $51.85 high.
That combination lowers the bar in one sense and raises the stakes in another. Management has not yet raised its full-year outlook, only kept it unchanged. The central question is whether Ouster can show that Rev8 has reached volume production on schedule, with shipments, conversions and fourth-quarter guidance all pointing higher. If it can, the recent selloff looks like a dilution hangover. If the ramp looks delayed, the market's skepticism will appear justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-13 | |
| Oct-07 | |
| Oct-01 | |
| Sep-14 | |
| Sep-09 | |
| Sep-02 | |
| Aug-26 | |
| Aug-26 | |
| Aug-20 | |
| Aug-18 | |
| Aug-11 | |
| Aug-07 |
