Ouster Beats On Record Revenue, But The Lidar Unit Dip During Rev8 Transition Is The Real Story
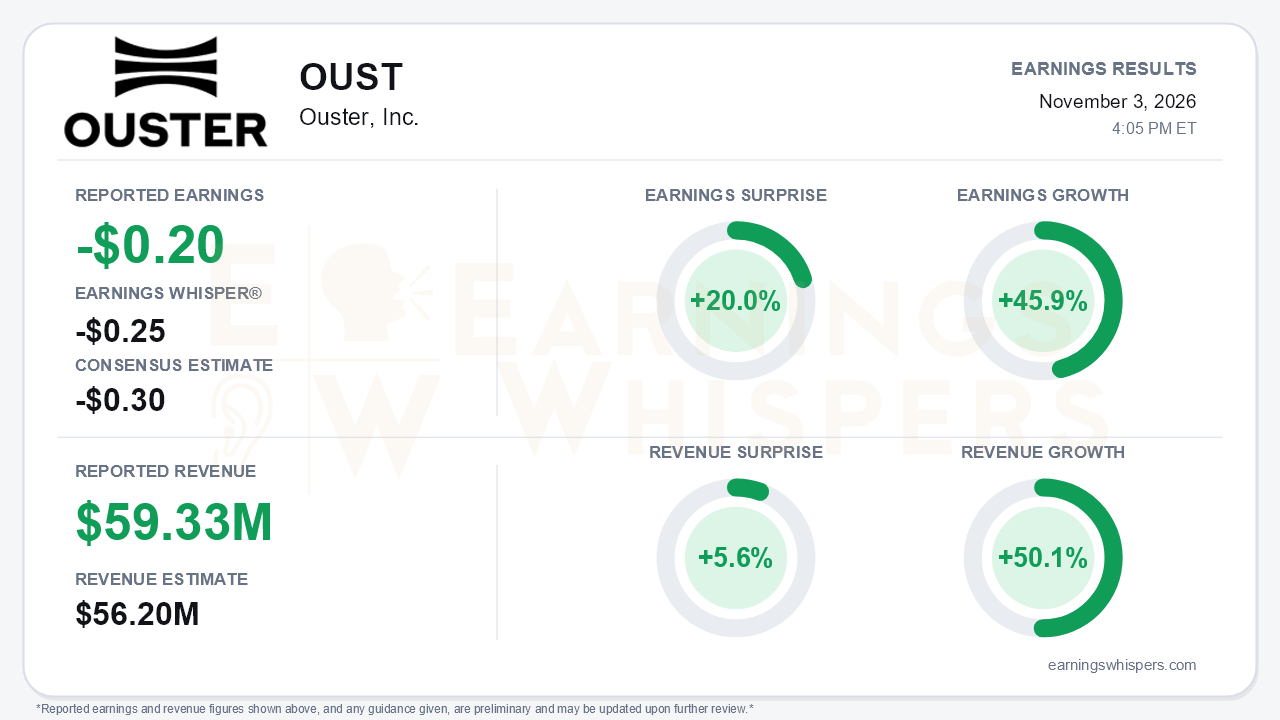
Ouster delivered a clean beat on both lines for the September quarter. The company posted a loss of $0.20 per share against a consensus estimate of -$0.30 and an Earnings Whisper of -$0.25, a 20.0% surprise. Revenue of $59.33 million topped the $56.2 million consensus by 5.6%, rose 50.1% year over year, and cleared the top of management's own $54.5-$57.5 million guide. Earnings improved 45.9% from a year ago as the net loss narrowed to $14.2 million from $21.7 million. The headline is strong, but it hides a less tidy picture. Ouster's core lidar volumes went backwards during the quarter while customers waited for Rev8, and cameras and royalties carried the growth. That is the central tension.
The quality of the beat deserves scrutiny. Product revenue grew 42% year over year to $56.0 million, and sequential product growth was a more modest 6%. Royalties jumped to $3.3 million from essentially nothing a year ago, which explains much of the gap between product and total growth. Management now expects about $8 million in royalties for 2026, up from roughly $5 million expected on the prior call. The per-share improvement also had help from below the operating line. Interest income nearly doubled to $4.2 million after the July equity raise, while the operating loss improved more modestly to $19.3 million from $24.3 million. Weighted shares rose to 71.5 million from 58.0 million, a reminder that the balance sheet was strengthened through dilution. Adjusted EBITDA continued its steady climb toward breakeven, at -$3.4 million versus -$4.5 million in Q2 and -$8.4 million a year ago.
Beneath the record 27,000 sensor shipments, the mix shifted sharply. Stereolabs cameras exceeded 20,000 units, more than double Q2, as robotics demand absorbed newly added capacity. Lidar units fell to roughly 7,000 from more than 9,000 in Q2, and lidar accounted for only about 27% of units. Management attributed the dip to customers migrating to Rev8 while production was still ramping, with only hundreds shipped. That ramp is slower than the Q2 framing implied. GAAP gross margin fell to 43% from 49%, but Q2 carried a one-time refund worth roughly 1,000 basis points, so the underlying trend is closer to flat. Management still holds a 35-40% long-term gross margin target, an implicit signal that today's levels are not expected to persist as volumes scale and competition intensifies.
The forward story is built on Rev8 conversion and capacity:
- **Backlog and ramp path:** Management cited a backlog of "many thousands" of Rev8 sensors and laid out a path from hundreds of units in Q3 to thousands in Q4 to tens of thousands by the end of 2027.
- **Capacity:** Benchmark's expansion to more than 100,000 annual lidar units is now dated to the end of 2027.
- **New wins:** These include an expanded defense partnership with Fortera, a Rev8 integration with John Deere subsidiary GUS Automation, drone payload deals, a 100-intersection Blue City expansion with a state DOT, and the ZBOX2 edge-compute launch on NVIDIA Jetson.
Fourth-quarter revenue guidance of $61-$64 million, including about $3 million of royalties, implies roughly 48% full-year growth excluding royalties, at the top of the 30-50% framework. That is a step up from the prior guide but lands in line with Street expectations rather than above them. The cost is cash. Operating cash burn reached $49.4 million through nine months, double last year's pace, as inventory and capex rose. Management also offered no specific Q4 outlook for Stereolabs. The $421 million cash position removes financing risk for now, which management emphasized.
The market setup is more complicated than the surprise implies. Shares opened at $45.84 after the August report, spiked to $51.85 within days, then collapsed 38.4% to $28.22 ahead of this release. That left them just 3.2% above the October 23 inter-earnings low and 12.9% below the $32.40 200-day moving average. Investor sentiment nonetheless moved from slightly negative (-0.05) to modestly positive (+0.15), a meaningful but not euphoric shift. In other words, expectations reset hard on price while the fundamental narrative was improving. The Earnings Whispers trend readings are mixed, with sequential growth and momentum positive but AVWAP still negative, consistent with a stock that has not yet repaired the damage from its post-August reversal.
The bottom line is that Ouster's quarter was better than the stock's recent trajectory suggests. Revenue topped guidance, losses narrowed, adjusted EBITDA approached breakeven, and the platform story gained credibility through Stereolabs. Bears still have legitimate ammunition. Lidar units declined, margins are expected to drift lower, cash burn is rising, and the Q4 guide merely matched expectations. Whether shares can reclaim lost ground likely depends less on this beat than on visible proof that the Rev8 backlog converts into thousands of shipped units in the coming quarter.
Read our earnings preview for Ouster, Inc.: https://www.earningswhispers.com/article/OUST/21607
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-26 | |
| Oct-21 | |
| Oct-13 | |
| Oct-07 | |
| Oct-01 | |
| Sep-14 | |
| Sep-09 | |
| Sep-02 | |
| Aug-26 | |
| Aug-26 |
