Safehold Must Prove Its Origination Rebound Is Real After A 32% Stock Slide
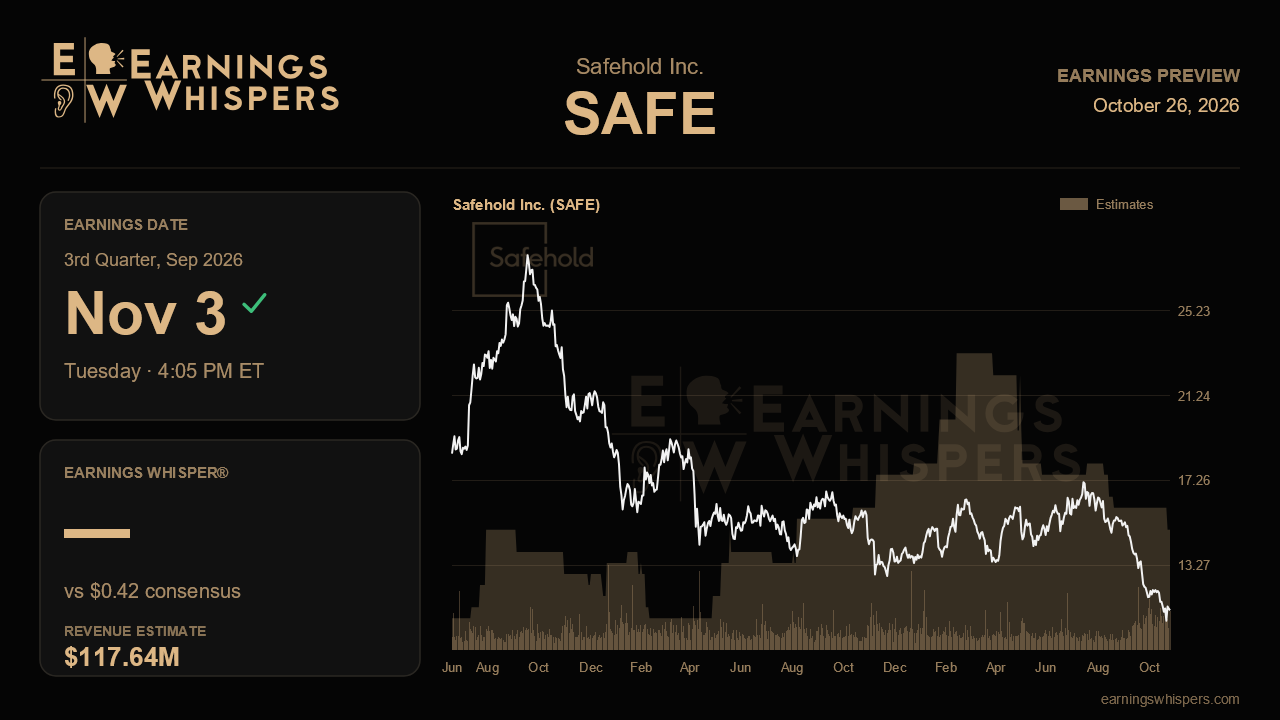
Three months ago Safehold delivered its most upbeat quarter in years: the busiest origination stretch since 2022, a Brookfield joint venture that put a private-market price on its ground leases, cheaper long-dated debt and a sharply smaller revolver balance. The stock has since fallen 32.3% while the S&P 500 gained 2.8%. That gap between the company's improving story and the market's verdict makes the November 3 report, due after the close, less about hitting a number and more about whether the momentum management described is still building.
The Street's bar looks modest on earnings. Consensus calls for EPS of $0.42, matching last quarter and up only 2.4% from $0.41 a year ago. Revenue is expected to reach $117.6 million, a 22.3% jump from $96.2 million but only about 2.6% above last quarter's $114.6 million. The mismatch between strong top-line growth and nearly flat per-share profit is the key structural point. Ground lease rent compounds steadily, but financing costs absorb much of that gain, so earnings depend heavily on how cheaply Safehold funds new deals. Safehold does not issue EPS guidance, so there is no management range to measure consensus against. The prior call's operating claims will serve as the yardstick instead.
Originations are the first test. Volume swung from about $46 million to $167 million, then $68 million, then $150 million over the past four quarters, so one strong quarter does not yet make a trend. Management said its pipeline was active and spoke of expanding the affordable housing platform beyond California into Texas, the Southeast, the Sunbelt and the Mid-Atlantic. Another quarter near or above $150 million, with evidence of new geographies, would support the turnaround case. A drop back toward Q1 levels would suggest that rising long-term rates, which management named as the main friction for sponsors assembling capital stacks, are winning out. The Unrealized Capital Appreciation figure, which climbed to $9.8 billion and is up roughly $1 billion from its 2025 trough, needs to keep rising to support the argument that the portfolio's embedded value is recovering.
The balance sheet is the second test. The Brookfield deal and the 30-year notes cut the revolver to $621 million from $890 million, lifted liquidity to about $1.4 billion and allowed management to say no new equity would be needed in the near future. Investors should check whether new investments are pulling the revolver back up, how the $30 million treasury lock gain continues to offset interest expense, and whether buybacks continue. The roughly 850,000 shares repurchased last quarter cost an average of $15.17, well above today's $11.15, so how management treats repurchases at these lower prices will indicate its confidence. Smaller watch items include multifamily rent coverage, which slipped to 3.4x as development deals ramp, the fully loaded yield drifting to 7.4%, the costs of the Park Hotels litigation, and any update on the 50th Street tenant's unpaid property taxes, which went unmentioned last time.
Sentiment has clearly soured. Readings moved from near neutral before the last report to 28.2% bearish now. The stock sits well below its 200-day moving average of $14.77 and only about 5% above its post-report low of $10.61, far beneath the $14.13 to $17.45 range of the prior quarter. That combination lowers the bar for reassurance, but it also means skeptics have little patience for another uneven quarter.
The central question is whether Q2 marked the start of a sustained recovery or a strong quarter between weaker ones. If originations hold up, UCA keeps rising and the balance sheet stays near its improved level, the market's sharp sell-off will look disconnected from the business. If deal volume stalls under rate pressure, the bears will have a fundamental case to match the stock's slide.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Sep-15 | |
| Sep-08 | |
| Aug-19 | |
| Aug-14 | |
| Aug-07 | |
| Jul-30 | |
| Jul-30 | |
| Jul-17 | |
| Jul-14 | |
| Jun-25 | |
| Jun-23 | |
| Jun-15 | |
| Jun-15 |
