RYAM's Cellulose Pricing Momentum Faces A Test As Stock Slumps Ahead Of Strategic Review
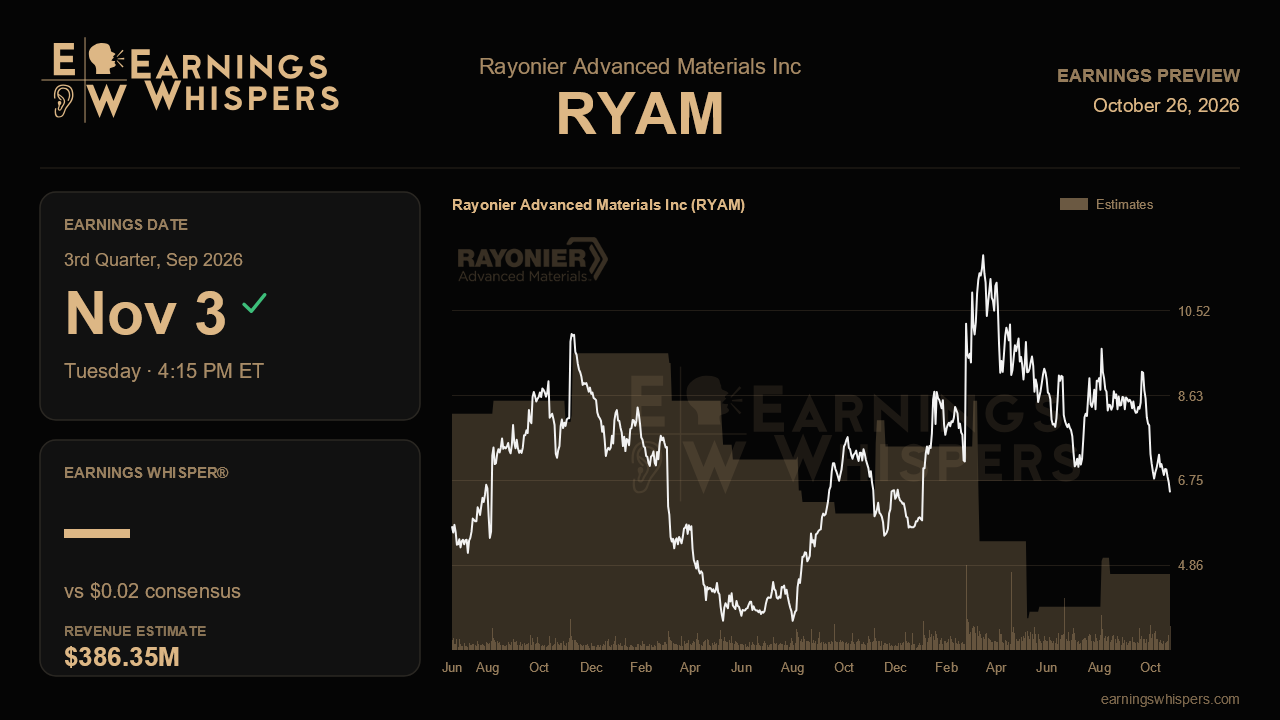
Rayonier Advanced Materials heads into its third-quarter report with a striking disconnect. The core cellulose specialties franchise has been delivering exactly what management promised, with higher prices, wider margins and better cash flow, yet the stock has fallen 29.3% since the last report while the S&P 500 slipped just 1.4%. At $6.48, shares sit below the $6.55 low of the post-earnings range and well under the 200-day moving average of $8.69. The market is clearly weighing something other than the improving pricing story, and this report needs to show whether that skepticism is warranted.
The Street is looking for earnings of $0.02 per share on revenue of $386.4 million. That would be a swing to a small profit from a loss of $0.07 a year ago, which accounts for the 128.6% expected EPS growth, alongside revenue growth of about 9.5%. The bar is modest in absolute terms but meaningful in direction. A penny or two of profit would mark a clear turn from the $0.30 loss last quarter, which included a $13 million non-cash impairment on high-yield pulp. Management did not lay out a fresh numerical outlook, saying only that results were tracking with prior expectations, so the consensus is effectively the Street's own read on whether the second-quarter rebound can carry forward.
That rebound was substantial. Total adjusted EBITDA jumped to $40 million from $8 million in the first quarter, and the high purity cellulose segment posted $57 million with margins of 19%, up from 9%. Cellulose specialties prices rose 21% from a year earlier and 8% sequentially, and management guided second-half volumes up 10% to 15%. The key validation this quarter is whether those volumes show up without giving back price. The company has chosen value over volume, and that strategy carries a real risk: customers could walk as 2027 contracts are negotiated. Any commentary suggesting pricing pushback or churn would undercut the main pillar of the bull case. Finalized Section 301 tariffs of 37.5% on Brazilian and 12.5% on Norwegian dissolving wood pulp, plus pending antidumping and countervailing duty decisions, should help, and investors will want evidence that the protection is translating into share or pricing power.
The weak link is paperboard and high-yield pulp, where adjusted EBITDA worsened to negative $10 million. New Section 338 tariffs on Canadian-origin paperboard threaten roughly three-quarters of the segment's US shipments. If losses there deepen, they could absorb much of the cellulose gains and keep the company stuck near breakeven. Balance sheet details matter too. Liquidity fell to $145 million, and net secured leverage of 4.2 times leaves little cushion against a 4.75 times covenant. Management has said it expects positive free cash flow for 2026, and year-to-date adjusted free cash flow of negative $8 million means the second half has to do the heavy lifting.
Sentiment has softened its bearish tilt, moving to 9.9% bearish from 15.3% before the last report, but the share price suggests that investors remain unconvinced. Part of that likely reflects how the narrative has changed. The $300 million-plus 2027 EBITDA run-rate target that once anchored the story has faded in favor of vaguer language about a stronger earnings base, while new CEO Dan Krawczyk, who has a background in transactions and restructuring, oversees a strategic review slated to finish in the fourth quarter. Any update on timing or direction, along with the nitrocellulose and defense supply angle he has emphasized, could matter as much as the quarterly figures.
In the end, the report has to answer one question: can cellulose specialties pricing and volume momentum outrun paperboard tariff damage while leverage stays below the covenant? If HPC margins hold near 19% and cash flow turns positive, the selloff looks overdone heading into the review. If not, the market's caution will appear well founded.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-21 | |
| Oct-09 | |
| Sep-30 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-21 | |
| Jun-25 | |
| Jun-24 | |
| Jun-22 | |
| Jun-17 | |
| May-14 | |
| May-05 | |
| May-05 |
