RYAM Misses As Temiscaming Tariff Shock And Review Delay Overshadow A Real HPC Recovery
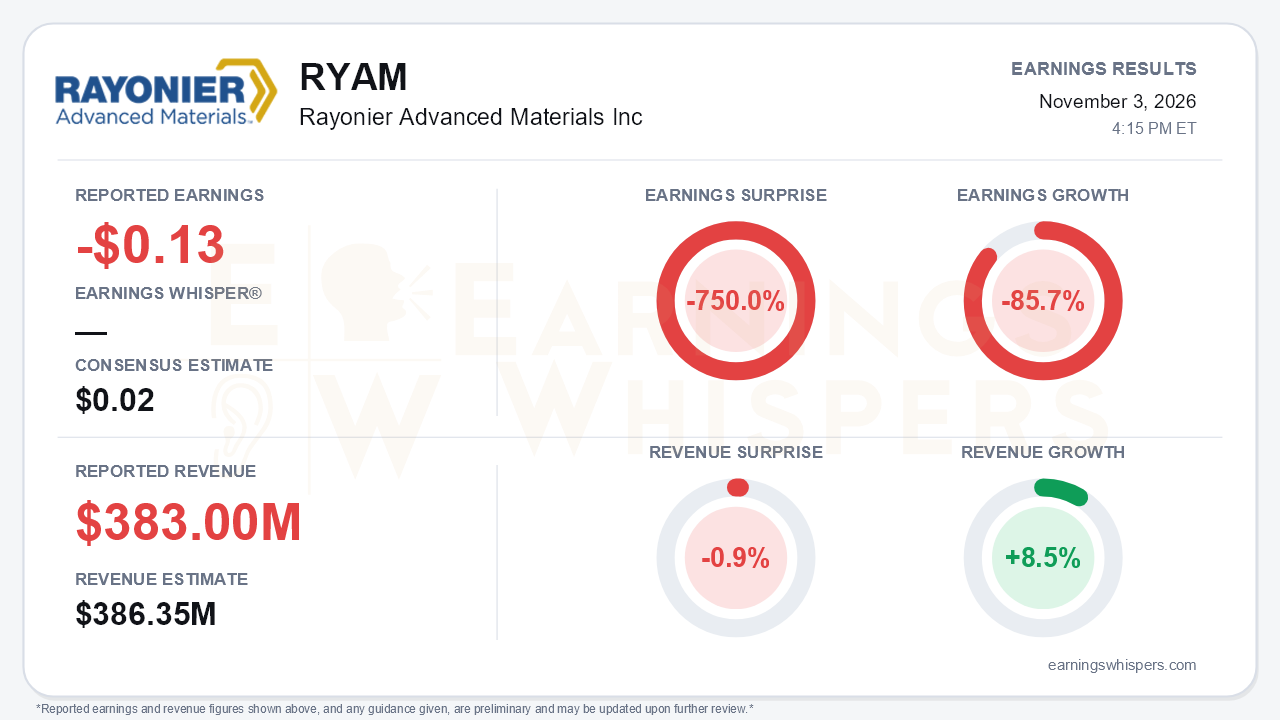
Rayonier Advanced Materials (NYSE: RYAM) delivered a quarter with two distinct stories. The adjusted result was a loss of $0.13 per share, against a consensus estimate calling for a $0.02 profit. That is a 750.0% miss, and earnings fell 85.7% from a year ago. Revenue of $383.0 million rose 8.5% year over year but slipped 0.9% short of the $386.35 million consensus. On a GAAP basis the damage was far larger: a $229 million net loss, or $(3.40) per share, driven by $221 million of non-cash impairments tied mainly to the Canadian Temiscaming site. Beneath that wreckage, however, the core High Purity Cellulose (HPC) business kept improving. That is the central tension: the operating engine is gaining traction just as the company's strategic optionality is narrowing.
The quality of the improvement in HPC is genuine.
- **Profitability:** HPC Adjusted EBITDA reached $73 million at a 23% margin, up from $57 million (19%) in Q2 and $24 million (9%) in Q1.
- **Consolidated results:** Adjusted EBITDA rose 30% sequentially to $52 million, from $40 million in Q2 and just $8 million in Q1.
- **Drivers:** Higher Cellulose Specialties (CS) pricing, lower wood and logistics costs, and a $3 million insurance recovery from the 2024 Jesup fire all contributed.
- **Cash flow:** Year-to-date adjusted free cash flow turned positive at $2 million, compared with -$8 million at mid-year.
The sequential progress is real. Year over year, however, the adjusted loss still widened, so this is a recovering business, not a recovered one.
The mix problem explains why the new CEO is pushing so hard on strategy. CS average pricing rose 19% year over year to $2,227 per metric ton, but CS volume fell 18%, from 105,000 tons to 86,000. The company backfilled with commodity cellulose, where volume jumped 42% even as pricing dropped 8% to just $825 per ton. CEO Dan Krawczyk said plainly that the commodity mix "masks the full value" of the CS franchise. Management laid out a sharper plan:
- shift production toward CS;
- exit structurally disadvantaged viscose and paper-pulp grades, potentially through plant-by-plant actions;
- open 2027 CS contract talks early, seeking longer-term commitments.
The call also carried a subtle retreat. Management signaled a "more measured" CS pricing approach in some markets after testing demand elasticity. That is a softer posture than the aggressive double-digit increases pursued a year ago. Full-year CS volumes remain below 2025, though management still expects to exit the year near 100,000 tons per quarter. Bears have legitimate ammunition in the possibility that the pricing gains have hit a demand ceiling.
The forward picture deteriorated on several fronts.
- **Temiscaming idling:** The 50% U.S. tariff on Canadian paperboard, effective August 22, made production uneconomic, and the site was idled on October 3.
- **Ongoing costs:** The idled site carries an estimated $2 million to $3 million per month in carrying costs, on top of $2 million in tariff costs absorbed in Q3. That segment was already EBITDA-negative, so the idling removes operating losses but replaces them with carrying costs and an unresolved asset.
- **Strategic review delay:** The review, previously targeted for Q4, slipped to Q1 2027 as interested parties seek clarity on the site. Management acknowledged management-buyout interest in Temiscaming.
- **Cash-flow language:** The goal of positive 2026 free cash flow softened from "on track" to something the company will "work towards," subject to tariff and site impacts.
- **Balance sheet:** Liquidity edged down to $143 million from $145 million in Q2 and $160 million in Q1. Net secured leverage stands at 4.0 times covenant EBITDA, and stockholders' equity swung to a $35 million deficit from $317 million at year-end.
On the positive side, there are tangible catalysts. Final antidumping and countervailing duty rates on Brazilian and Norwegian imports have been issued, with a U.S. International Trade Commission injury decision expected mid-November. Construction has also begun on the Altamaha Green Energy project at Jesup.
Investors were already leaning bearish heading into the report, and that tilt intensified. Earnings Whispers sentiment moved from -0.15 to -0.32, a meaningful deterioration rather than noise. The shares fell 24.6% from the $9.17 open following the August report to $6.91, leaving them about 20% below the 200-day moving average of $8.66. The trend readings are mixed: momentum is positive, while price and AVWAP trends remain negative. In other words, the market has been pricing the Temiscaming and review risks well ahead of the call.
The bottom line is that RYAM's HPC turnaround is producing measurable margin and cash-flow gains, but the quarter's headline miss reflects a company whose strategic path just got longer and more expensive. The idled Canadian site, a delayed review, softer cash-flow language, and a moderating CS pricing stance offset much of the operating progress. Until the mix shift shows up in CS volumes and the strategic review produces a concrete outcome, the improving EBITDA trend may struggle to overcome the balance-sheet and execution questions.
Read our earnings preview for Rayonier Advanced Materials Inc: https://www.earningswhispers.com/article/RYAM/21621
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-21 | |
| Oct-09 | |
| Sep-30 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-21 | |
| Jun-25 | |
| Jun-24 | |
| Jun-22 | |
| Jun-17 |
