Postal Realty Seeks A Fourth Straight Raise As Its Stock Drifts Toward Range Lows
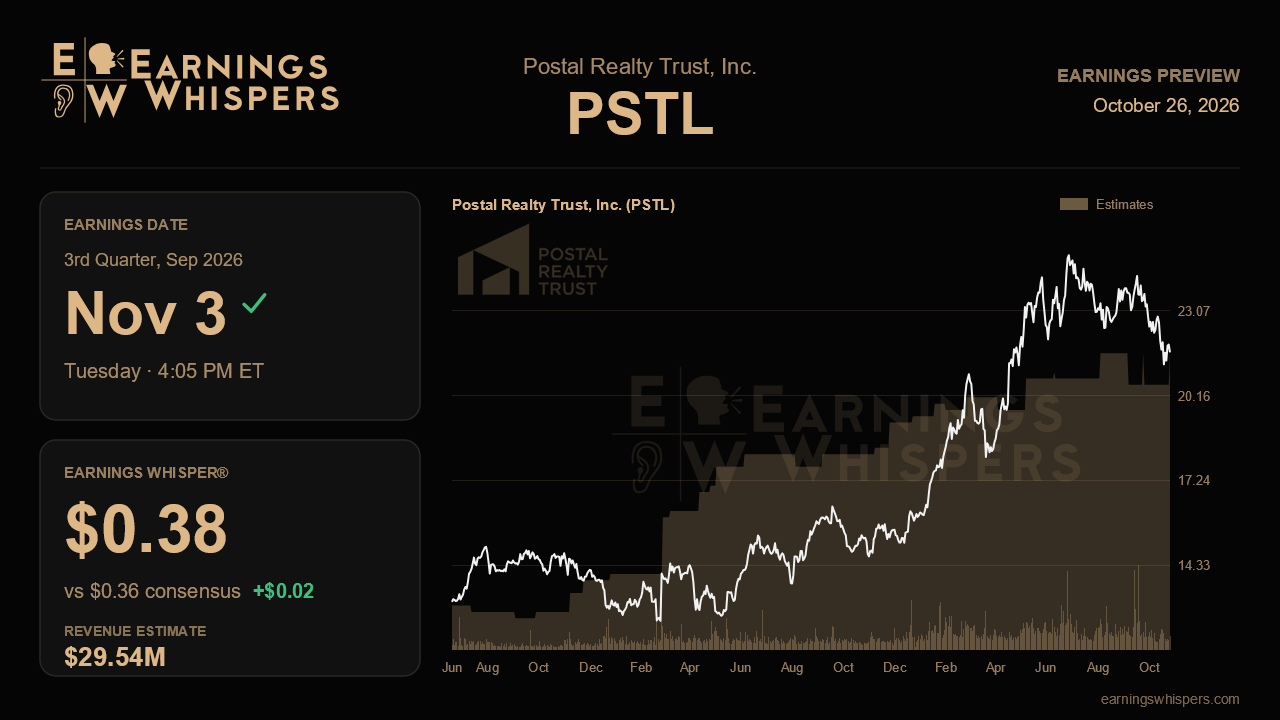
Postal Realty Trust heads into its third-quarter report with an odd disconnect. Management has raised its full-year outlook three times running, lifted acquisition targets by roughly 30% this year and described its confidence as the highest it has ever been. Yet the stock has fallen 7% since the last report, trailing the S&P 500 by more than five percentage points. When the company reports after the close on November 3, the question is whether the operating story can close that gap or whether the market has spotted something the guidance has not yet captured.
The Street expects non-GAAP earnings of $0.36 per share on revenue of about $29.5 million. That would mark a 21.4% jump in revenue from the year-ago quarter's $24.3 million, strong growth for a landlord whose tenant base is a single federal agency, and a modest step up from last quarter's $28.6 million. The per-share consensus also sits comfortably above the $0.31 reported last quarter and the $0.33 posted a year ago. The Earnings Whisper of $0.38 is a couple of cents higher, a small but real signal that some investors expect the company to clear the published bar.
Full-year guidance calls for $1.41 to $1.43 per share, and consensus sits at $1.41, the very bottom of that range. That positioning matters. Analysts have not fully bought into the most recent raise, which leaves room for upside if the third quarter confirms management's trajectory. It also means another increase, which would be the fourth consecutive one, would carry real weight rather than simply catching guidance up to Street numbers.
The acquisition pipeline is the most important operating test. Through July the company had closed $88 million of deals at an average 7.4% cap rate, against a full-year target of $150 million to $160 million. Hitting that goal requires a busy second half, so third-quarter volume and the commentary on the fourth-quarter pipeline will show whether the target was realistic or aspirational. Pricing deserves equal scrutiny. Going-in cap rates have slid from 7.7% last year to 7.3% in the second quarter as the company chases larger assets and portfolios. Management argues that a 6.0% cost of capital leaves a spread of roughly 130 basis points, generating several times the accretion per deal it earned a year ago. Further cap rate compression would test that argument, and the stock's decline nibbles at the equity side of the cost of capital calculation. The good news is that $110 million of equity raised through July already funds the pipeline, and pro forma leverage of about 4.0x sits well below the newly lowered 5.5x ceiling.
Internal growth is the quieter but arguably more durable pillar. Management said same-store cash NOI is tracking 6% to 7% this year, guided to about 6.5% same-store cash revenue growth in 2027, and noted that 10-year leases now make up 54% of the portfolio, with escalators covering a rapidly rising share of rent. Evidence that lease conversions and escalators are flowing through as promised, along with G&A continuing to run below plan and the benefit of July's cheaper credit facility, would validate the view that growth no longer depends on deal-making alone.
Sentiment has cooled noticeably, swinging from solidly bullish before the last report to mildly bearish now. The shares, at $21.64, sit just under their 200-day moving average and only about 2.5% above the post-earnings low of $21.10, with the entire trading range having shifted lower than the prior quarter's. That sets a lower bar for an emotional reaction. The central issue is whether Postal Realty can show that its acquisition engine is meeting volume targets without giving up too much yield, while internal growth keeps compounding. If both hold and guidance edges higher again, the narrative stays intact and the stock's slide looks more like sentiment than substance.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-08 | |
| Aug-31 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-24 | |
| Jul-06 | |
| Jun-01 | |
| May-26 | |
| May-05 | |
| May-05 | |
| May-05 | |
| May-04 | |
| Apr-23 |
