Postal Realty Trust Falls Short Of The Whisper As Record Buying, Lower Leverage And A Third Guidance Raise Collide With Cap-Rate Compression
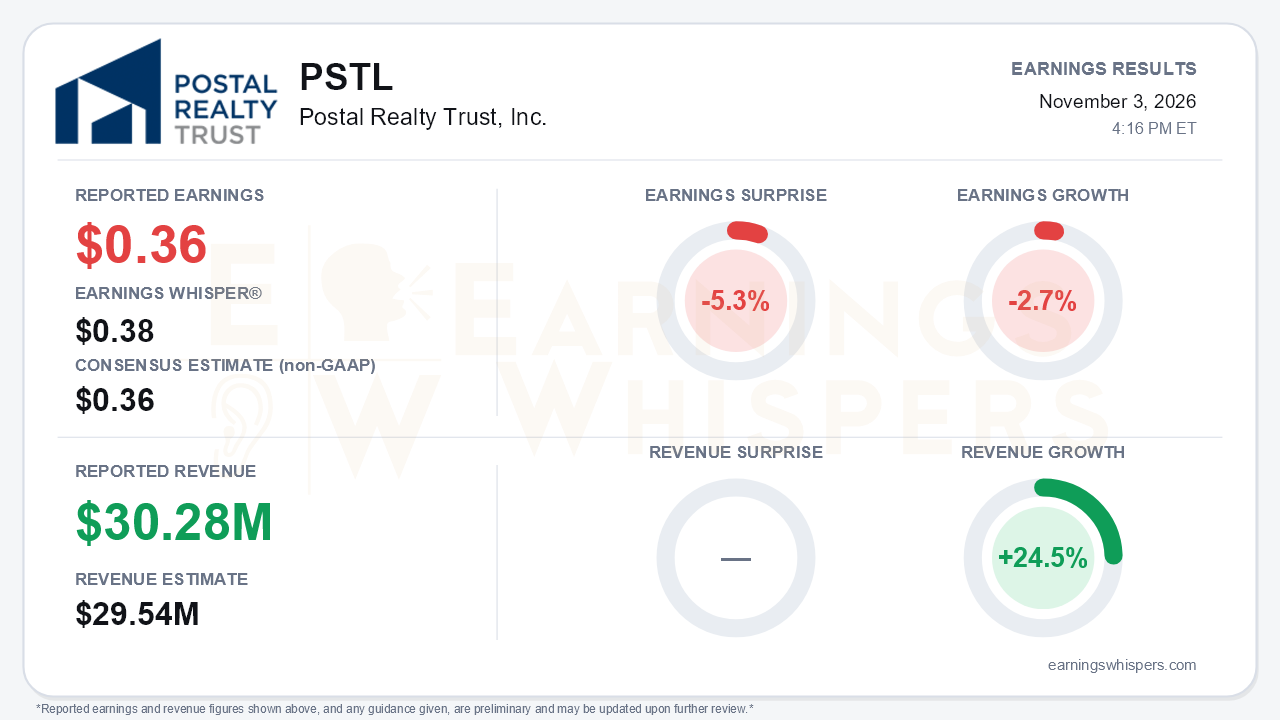
Postal Realty Trust (NYSE: PSTL) reported third-quarter AFFO of $0.36 per share. That matched the $0.36 consensus but fell short of the $0.38 Earnings Whisper number, a 5.3% miss against the bar investors were actually watching. Revenue of $30.28 million beat the $29.54 million consensus by 2.5% and grew 24.5% year over year, driven by rental income that rose 25.2% on acquisitions and internal growth. Earnings Whispers' normalized comparison shows earnings down 2.7% from a year ago, which sits awkwardly beside the company's headline claim of 9.1% AFFO per share growth. Investors should recognize the gap rather than accept either framing uncritically. That is the central tension: the operating platform is scaling quickly, but rapid growth in the share count and rising costs are keeping per-share results from fully reflecting it.
The quality of the quarter deserves scrutiny on per-share economics. AFFO per share was flat sequentially at $0.36, which management attributed to seasonal operating expenses and about $250,000 of one-time G&A. GAAP general and administrative expense rose to $5.1 million from $3.8 million a year earlier. Diluted weighted average common shares rose to roughly 30.6 million from 24.6 million, and the company has raised $116.9 million of net equity through its ATM program since the second quarter. GAAP net income attributable to common shareholders rose to $5.6 million, or $0.16 per diluted share, from $3.8 million, or $0.13. Dollar growth is clearly strong. The open question is how much of it survives the dilution.
The call preserved a credible growth story. PSTL acquired a record 145 properties for $82.0 million, nearly double second quarter's $45 million, and raised 2026 acquisition guidance for the third time to $185-$200 million. AFFO guidance moved up a penny to $1.42-$1.44, the third consecutive increase, with the midpoint now implying 8.3% growth. However, the raise only brings guidance in line with estimates rather than ahead of them. Leasing fundamentals remain excellent:
- Occupancy is 99.8% and retention is 99.6%.
- Leases with escalators rose to 60% and 10-year terms to 55%.
- Management reaffirmed 6.5% same-store cash revenue growth for 2027.
- 2026 same-store cash NOI is tracking to the midpoint of its 6%-7% range.
Management also cited roughly 200 basis points of yield expansion on its 2020-22 acquisitions as evidence that mark-to-market rents reward patience.
Bears have legitimate ammunition on deployment returns. The acquisition cap rate slid to 6.9% in the third quarter from 7.5% in the fourth quarter of 2025, 7.4% in Q1 and 7.3% in Q2, and guidance was trimmed to the "low 7%" range from the mid-7s. PSTL is increasingly relying on future rent resets rather than day-one yield to justify its purchases. The widened acquisition range also implies only about $23-$38 million of fourth-quarter volume, which management tied to market volatility and cost-of-capital sensitivity. The tenant backdrop adds risk: the USPS reported a $2.5 billion quarterly loss, and the Postmaster General warned of a severe liquidity crisis, although management said lease negotiations, including talks on 2028 expirations, are unchanged.
The balance sheet is a genuine bright spot. Pro forma net debt to run-rate adjusted EBITDA fell to 3.5x from 4.6x at the end of 2025. Fitch's BBB rating joins KBRA's and triggers investment-grade pricing on the recast $615 million credit facility. Liquidity exceeds $340 million, 93% of debt is fixed, and nothing matures until 2028. CEO Andrew Spodek said he had "never been more confident."
The market has not shared that confidence. Investor sentiment swung sharply from a solidly positive 0.42 to a slightly negative -0.07, a meaningful reversal of expectations. Shares are down 7.2% since opening at $23.26 after the prior report and now trade at $21.59, about 1% below the 200-day moving average. Notably, that price sits below the $23.27 weighted average initial gross price on PSTL's unsettled forward equity. Any future equity raises would therefore come at a less favorable cost of capital, the very input management says drives acquisition volume. Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative.
The bottom line is that PSTL delivered a fundamentally solid quarter with record acquisitions, a stronger balance sheet, an investment-grade upgrade and a third guidance raise. It still fell short of the whisper, its per-share growth looks far less impressive on a normalized basis, and it is paying more for each dollar of acquired rent. With the stock drifting below its forward-sale price and sentiment turning negative, the next leg depends on whether falling cap rates and a softer fourth-quarter pipeline can still produce per-share growth that outruns dilution.
Read our earnings preview for Postal Realty Trust, Inc.: https://www.earningswhispers.com/article/PSTL/21614
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Oct-08 | |
| Aug-31 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-24 | |
| Jul-06 | |
| Jun-01 | |
| May-26 | |
| May-05 |
