SLR Investment Must Show Its Origination Surge Can Protect A Freshly Cut Dividend
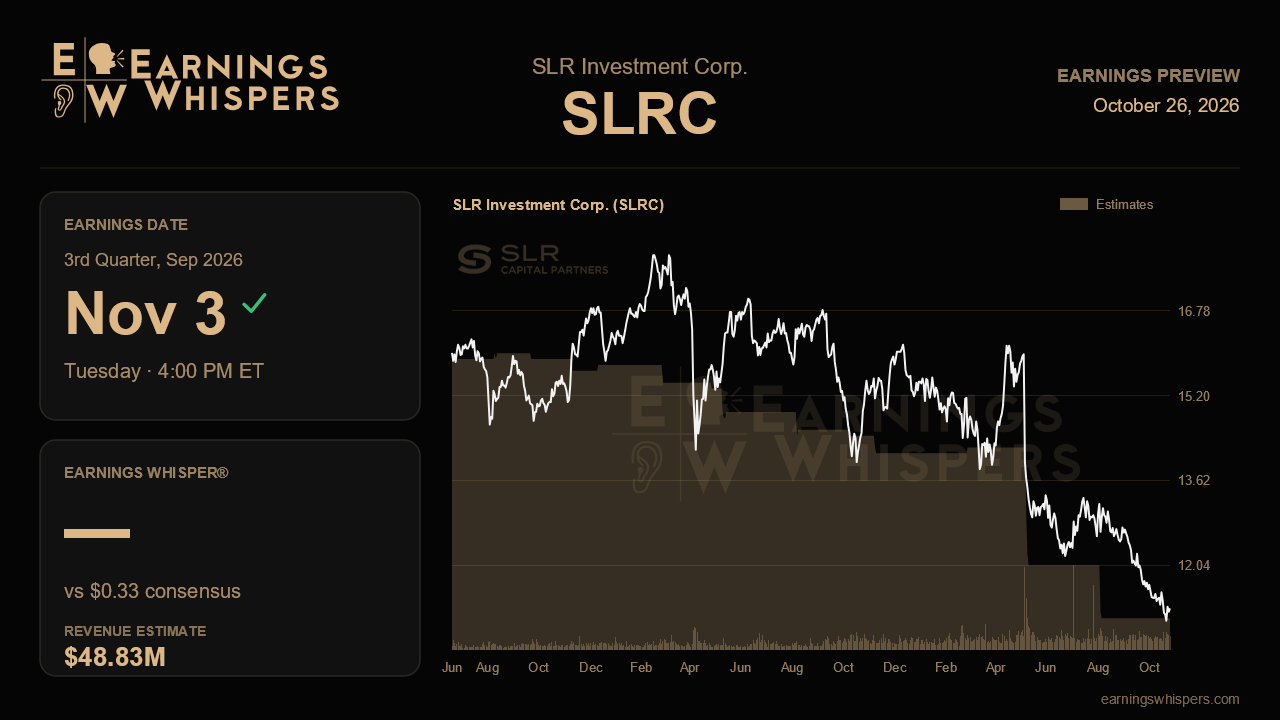
SLR Investment Corp. heads into its third-quarter report with a puzzle that the market has so far refused to give it credit for solving. Last quarter the business development company booked $471 million of gross originations, roughly 60% above its post-2018 average, yet it also cut its dividend to $0.31, placed its first loans on non-accrual in about two years and reported a third straight decline in net asset value. The upcoming release, due after the close on November 3, should begin to show which of those two stories carries more weight.
The Street is not asking for much. Consensus calls for net investment income of $0.33 per share on revenue of $48.8 million, both identical to the prior quarter. That flat sequential line masks a meaningful year-over-year contraction, with earnings expected to fall 17.5% from $0.40 and revenue down 14.3% from $57.0 million. Management did not offer formal guidance, but the dividend reset is effectively its own forecast. At $0.33, earnings would cover the new $0.31 payout with only a thin cushion, so even a penny or two of slippage would revive questions about whether the cut went far enough.
The most important test is whether the second-quarter origination burst finally converts into income. Deals closed late in a quarter often contribute little until the following period, so a portfolio that grew meaningfully should produce rising interest income now. If revenue merely matches consensus, it suggests new loans are only replacing repayments and lower-yielding assets, not expanding the earning base. Yield is the related swing factor. The weighted average portfolio yield slid from 12.2% to 11.1% over several quarters, with asset-based lending dipping to 12.0% and cash flow loans to 9.6%. Stabilization at those levels would support management's view that specialty finance can hold up returns; another leg lower would indicate that competitive pricing is eating the benefit of volume.
Credit is the other half of the verdict. The non-accruals on RQM, a contract research firm hit by regulatory-driven demand delays, and OmniGuide, a surgical laser maker struggling with operational and supply chain problems, together represent about $60 million of par value and pushed unrealized losses to $9.5 million. Investors will want to see those positions contained rather than joined by new names, especially since management flagged pressure on borrowers with declining cash flows. A steady NAV near $18.00 would be reassuring; a fourth consecutive drop would undermine confidence that last quarter's markdowns were isolated. Interest coverage of 2.25x and a portfolio described as 97.5% healthy provide a baseline to measure against.
The growth catalysts introduced last quarter also deserve early evidence. Management leaned into a recovering life sciences market, citing a pipeline up 20% year over year, and set up an asset-based lending sourcing partnership with a large U.S. commercial bank. Any sign that these channels are producing funded loans, plus progress on specialty finance tuck-in acquisitions, would give the bull case something tangible beyond more than $900 million of available capital.
The market has already rendered a harsh preliminary judgment. Shares have fallen 12.7% since the last report, trailing the S&P 500 by more than 11 points, and at $11.23 they sit well below the 200-day moving average of $13.51 and just above the post-earnings low of $10.96. That price is only about 62% of last reported NAV, a discount that implies deep skepticism about credit. Sentiment remains bearish, though marginally less so than a quarter ago. Ultimately the report hinges on one question: can the fresh loan volume lift earnings enough to cover the $0.31 dividend comfortably while credit losses stay contained? A clear yes could narrow that discount; another quarter of shrinking NAV and fragile coverage would confirm the market's doubts.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-01 | |
| Aug-04 | |
| Aug-04 | |
| Jul-01 | |
| May-05 | |
| May-05 | |
| Apr-08 | |
| Mar-10 | |
| Feb-26 | |
| Feb-25 | |
| Feb-24 | |
| Feb-24 | |
| Feb-24 | |
| Feb-17 |
