SLR Investment Holds NII At $0.33 On Record Originations, But NAV Erosion And A Darker Credit Outlook Dominate
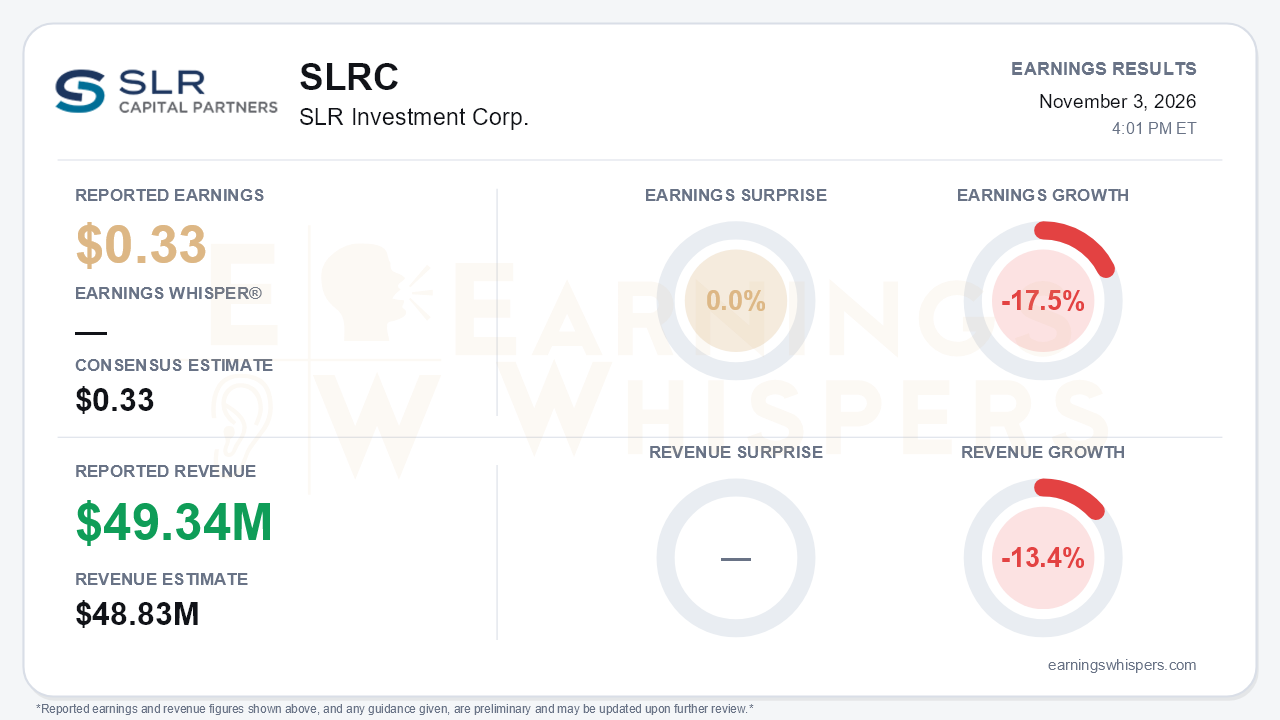
SLR Investment Corp. (NASDAQ: SLRC) delivered exactly what the Street expected on the income line: net investment income of $0.33 per share matched consensus, and total investment income of $49.34 million topped the $48.83 million estimate by 1.0%. But the in-line print is not the story. NII fell 17.5% year over year and revenue dropped 13.4%. Net asset value slipped again, to $17.83 from $18.00. Management's view of the credit cycle also turned noticeably more cautious. The central tension is that SLRC is finally growing its book after a year of shrinkage, while at the same time warning that the credit environment it is lending into is getting worse.
The quality of the quarter deserves scrutiny beneath the matched NII figure. Net realized and unrealized losses of $10.2 million, or $0.19 per share, cut GAAP earnings to $0.14 per share from $0.43 a year ago. Most of the damage came from a $15.4 million unrealized loss in non-controlled holdings, which the call tied mainly to the OmniGuide non-accrual markdown. NAV has now fallen in three straight quarters, from $18.26 at year-end 2025 to $17.83. The last two declines each ran roughly 90 basis points.
The year-over-year income decline reflects a smaller average income-producing portfolio, not lower yields. NII has now sat at $0.33 for three consecutive quarters, down from $0.40 in the fourth quarter of 2025. The distribution, already reset to $0.31 from $0.41, is covered, but with little cushion.
The operating trends are better than the headline suggests. Gross originations reached a record $575.1 million, up from $471 million in Q2 and $242 million in Q1, and 95% were in specialty finance. Net originations jumped to $146 million from $40 million in Q2, a sharp reversal from net repayments of $118 million in Q1. The comprehensive portfolio grew to roughly $3.4 billion, and yields moved in the right direction:
- The asset-based lending yield rose to 12.6% from 12.0%.
- The cash flow yield improved to about 10% from 9.6%.
- The weighted average asset yield edged up to 11.2%.
Equipment finance grew to $1.2 billion. The super-regional bank partnership is now producing referrals. Funding costs are also coming down, helped by a $250 million equipment finance ABS at a fixed 5.6%.
The weak spots were smaller but notable. Life science originations fell to just $5 million from $24 million, despite upbeat commentary last quarter. The SSLP yield also eased to 11.0% from 11.8%.
The forward-looking risk picture has shifted. Management now explicitly expects defaults and liability management exercises to rise through next year, and warned that loss-given-default could be higher than many expect. It cited record trailing default rates across the industry and public BDC NAVs down more than 5% year to date. That is a meaningful step from the "middle stages of the cycle" language used earlier in the year.
Just as telling is what management did not say. It made no reference to the earlier path back to $0.40 in NII, and dropped last quarter's claim that growth initiatives would lift earnings. It also noted that higher financing costs and credit losses are offsetting the floating-rate tailwind.
On the positive side, the reported credit metrics remain contained. Non-accruals are limited to two names, at 1.2% of fair value and 2.9% of cost. The watchlist fell to 2% from 2.5%, and software exposure is under 1%. On the balance sheet, $260 million of unsecured notes mature between December and March. The $135 million private placement at 6.76% due 2030 addresses a large portion of that.
The market had already priced in plenty of skepticism. Shares at $11.80 are down 8.2% since the open after the August report and sit 11.9% below the 200-day moving average of $13.40. That leaves the stock trading at roughly two-thirds of NAV. Management is leaning into that discount: it repurchased $10 million of stock at about $11.31 in October, a move it expects to be accretive.
Investor sentiment remained negative but improved, rising from -0.16 to -0.08. That suggests expectations had become less pessimistic heading into the print, not that investors had turned bullish. The Earnings Whispers trend signals remain mostly negative, with price, momentum and AVWAP readings all weak.
The bottom line is that SLRC is executing on growth. Record originations, rising yields and cheaper funding give it a credible route to stabilizing NII. But the report did nothing to stop the NAV erosion, and management itself is now forecasting a tougher default cycle. Until the book value slide halts and the larger portfolio begins lifting NII above $0.33, the deep discount to NAV looks more like a reasonable reaction to credit uncertainty than an obvious mispricing.
Read our earnings preview for SLR Investment Corp.: https://www.earningswhispers.com/article/SLRC/21628
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-01 | |
| Aug-04 | |
| Aug-04 | |
| Jul-01 | |
| May-05 | |
| May-05 | |
| Apr-08 | |
| Mar-10 | |
| Feb-26 | |
| Feb-25 | |
| Feb-24 |
