Seadrill Faces A Sequential Step Down As Idle Rigs Test Its Twice-Raised Outlook
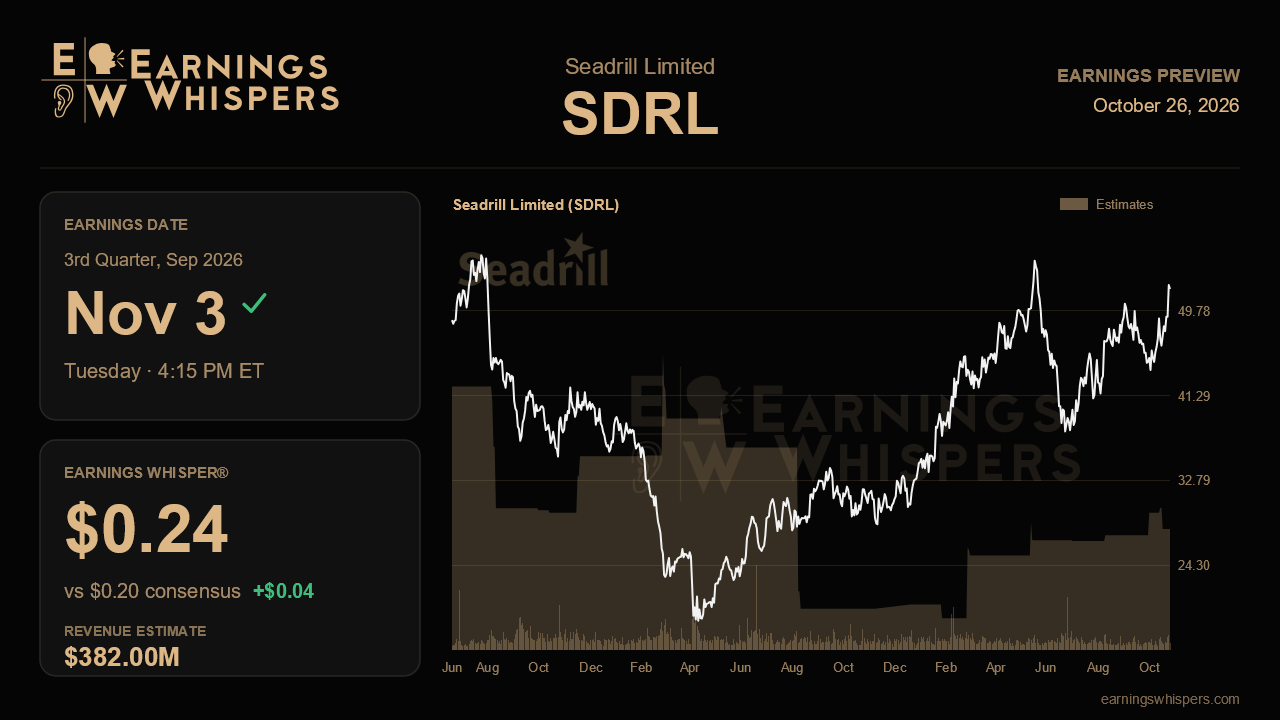
Seadrill heads into its third-quarter report with a two-sided setup. Management has raised its full-year outlook twice this year, legacy contracts are finally repricing higher, and buybacks have resumed. Yet the company's own numbers point to a noticeably smaller quarter than the blowout it just posted. When Seadrill reports after the close on November 3, the question is whether the dip is the orderly, already-flagged pause that management described, or the first sign that rig gaps and maintenance costs are eating into the recovery story.
Wall Street expects earnings of $0.20 a share on revenue of about $382 million. That would be a sharp turnaround from the $0.17 loss a year ago and roughly 5% revenue growth, but it is also well below the $0.47 and $449 million delivered last quarter. The whisper number of $0.24 sits modestly above consensus, suggesting the more engaged crowd expects Seadrill to clear the published bar, though not by a dramatic margin. The sequential drop is consistent with guidance. Full-year revenue guidance of $1.50 billion to $1.55 billion, set against roughly $804 million booked in the first half, implies second-half revenue of about $348 million to $373 million per quarter. On that math the $382 million consensus already leans to the optimistic side. EBITDA guidance of $420 million to $450 million tells a similar story: after $241 million in the first half, the second half implies something like $90 million to $105 million per quarter, a long way from the $144 million just reported.
That gap is where the real analysis lies. Management attributed the softer back half to identifiable pressures rather than weaker demand. Repair and maintenance spending is weighted toward the second half, West Carina left its Petrobras contract at the end of June and was moved to Walvis Bay without confirmed work until early 2027, West Gemini rolls off later this year while still being marketed in West Africa, and the Savan Louisiana has little visibility. A quarter that lands in line while repricing on West Jupiter and West Telus, worth roughly $400,000 a day combined over their old contracts, holds margins together would validate the view that these are temporary holes. A quarter where maintenance overruns or idle time pushes EBITDA toward the bottom of the implied range would challenge it, especially after two upward revisions have raised the stakes.
The commercial update may matter as much as the income statement. Last quarter's West Vela award, a one-year US Gulf contract at leading-edge rates in the mid-$400,000s, marked a step up from the low-$400,000s that had prevailed. Fresh fixtures at or above that level, and especially follow-on work for Carina or Gemini, would support management's forecast of mid-90s drillship utilization by 2027. Silence on those rigs, or weaker pricing amid the near-term US Gulf oversupply management acknowledged, would make the 2027 thesis harder to defend. Progress on the $208 million buyback authorization, which runs through year-end, will also signal how confident the board is about cash generation.
The market has already rewarded the narrative. Shares have climbed 11.5% since the last report while the S&P 500 slipped, and at about $52 the stock sits well above its 200-day average and within 2% of its post-earnings high of $52.80, effectively testing a breakout. Sentiment has cooled, however, with bullish readings roughly halving from the prior quarter, a sign that enthusiasm has not kept pace with the share price.
Ultimately, this report is less about the headline beat and more about whether Seadrill can reaffirm or nudge up its full-year range while showing the contract gaps are closing. If repricing gains outweigh idle-rig drag and new work fills the calendar, the second-half lull looks like a pause. If not, the twice-raised outlook may start to look like its peak.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-16 | |
| Oct-12 | |
| Oct-06 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-14 | |
| Jul-09 | |
| Jun-22 | |
| Jun-15 | |
| Jun-15 | |
| Jun-03 | |
| May-12 |
