Seadrill Misses The Whisper As Sequential Earnings Soften, But A Third Guidance Raise And A $179 Million Cash Inflection Lock Up 2027
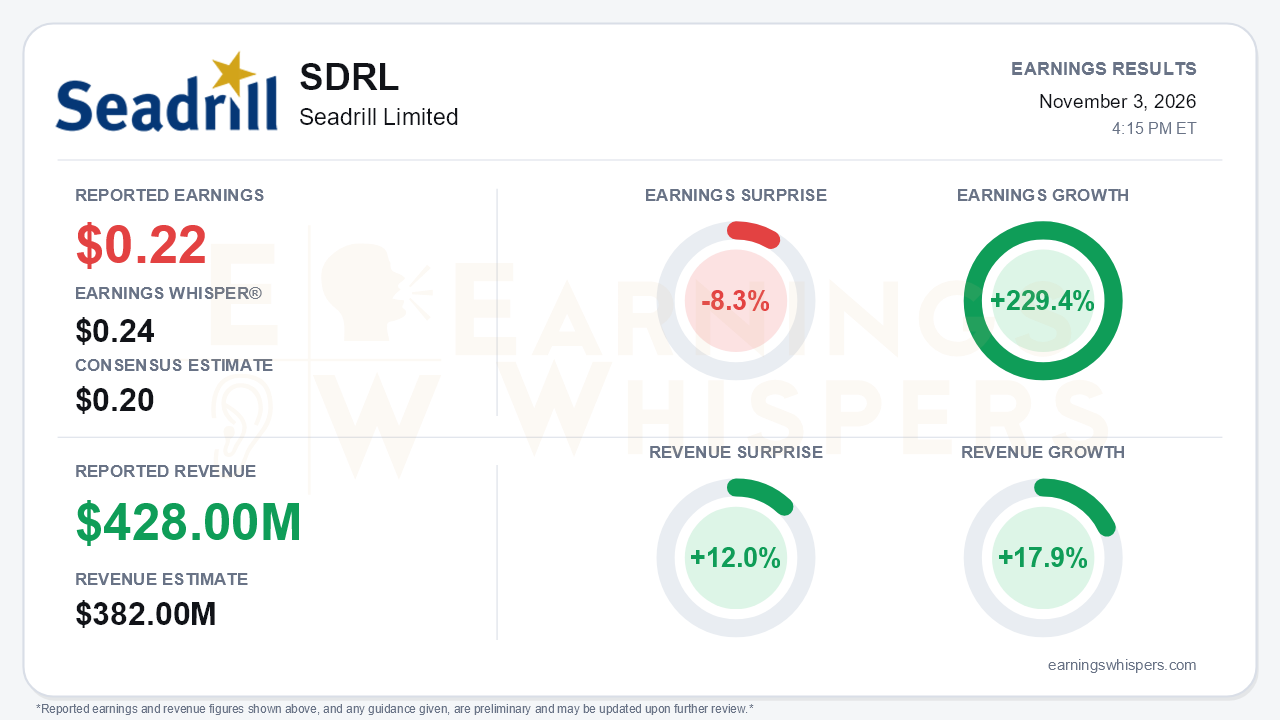
Seadrill delivered a quarter that looked weaker on the income statement than in its commercial and cash-flow story. Earnings Whispers adjusted EPS of $0.22 topped the $0.20 consensus but missed the $0.24 Earnings Whisper number by 8.3%. Revenue of $428.0 million beat the $382.0 million consensus by 12.0%. Year over year, earnings grew 229.4% and revenue rose 17.9%. The GAAP picture was harsher: a net loss of $30 million, or $0.49 per diluted share, compared with net income of $29 million in the second quarter. Management attributed part of that loss to a legal provision. The central tension is that near-term earnings are rolling over sequentially while the forward book has strengthened considerably.
The sequential numbers show why the beat deserves scrutiny. Total operating revenue fell from $449 million in the second quarter to $428 million. Contract revenue dropped from $355 million to $329 million as the West Carina came off contract and the West Vela, West Elara and Sevan Louisiana sat idle between jobs. Adjusted EBITDA slid to $121 million from $144 million. Margin excluding reimbursables compressed to 29.7% from 33.5%, and economic utilization dipped to 94.5% from 95.5%. Below the operating line, other financial and non-operating items swung to a $48 million charge. Combined with higher depreciation and a $19 million tax bill, that pushed the GAAP result into the red. The one clear positive inside the quarter was pricing: average contractual dayrates rose to $376,000 from $360,000 even as the average rig count fell from 10 to 9.
Cash is where Seadrill delivered on its stated promises. Operating cash flow was $195 million and free cash flow reached $179 million, a sharp reversal from the $43 million of negative free cash flow in the second quarter. Cash climbed to $506 million, net debt fell to $244 million, and buybacks rose modestly to $22 million. Investors should note that the inflection was flattered by a lump-sum West Tellus mobilization fee and a working-capital release, so $179 million is not a clean quarterly run rate.
The call preserved a credible growth story. Full-year revenue guidance rose to $1.56-$1.58 billion excluding reimbursables, up from $1.50-$1.55 billion. Adjusted EBITDA guidance increased to $440-$460 million from $420-$450 million. This was the third consecutive raise, and the EBITDA range now sits well above the $350-$400 million range set at the start of the year. Commercially, Seadrill added roughly $800 million of contract value since August, versus about $200 million in the prior period. The headline addition was a West Carina award in Indonesia worth about $420 million over 880 firm days. That contract carries an $85 million mobilization fee and completes the repricing of all three legacy contracts. The West Capella was extended to February 2028, with unpriced options exercised in the mid-$400,000s. The Sonangol Libongos is committed into 2030. More than 85% of 2027 drillship days are now booked, down from roughly 30% open at the second-quarter call. Leading-edge rates have moved into the mid-to-high $400,000s.
Bears have legitimate ammunition, however. The raised guidance still implies a softer fourth quarter, burdened by repairs, maintenance and West Carina preparation costs. Management described the U.S. Gulf as oversupplied by a few drillships, and the Sevan Louisiana has limited 2027 visibility beyond short Kosmos and LLOG programs. Petrobras is releasing about one-fifth of its drillship fleet, with its next award wave not expected until the first half of 2027. The West Gemini has no follow-on work after January 2027. Management also conceded that IOCs remain capital-disciplined and are contracting for discrete programs rather than long terms.
Investors appear to have priced in that ambiguity. Earnings Whispers sentiment weakened from 0.14 to essentially neutral at 0.01, a meaningful cooling of expectations heading into the report. Shares have gone nowhere since the August report, sitting 0.6% below the post-report open at $46.32. The stock trades just 2.6% above its $45.15 200-day moving average. Price, momentum and AVWAP trend readings are positive, while sequential growth remains negative, which fits a business whose reported quarters are softening even as its outlook improves.
The bottom line is that Seadrill traded near-term earnings softness for a far more secure 2027. The whisper miss, the GAAP loss and the margin compression are real, and fourth-quarter costs will keep pressure on reported results. Still, three straight guidance raises, repriced legacy contracts, rising dayrates and better than 85% 2027 coverage give the stock earnings visibility that a neutral sentiment reading does not fully reflect. The open questions are the U.S. Gulf, Brazil and whether free cash flow holds up once one-time mobilization receipts fade.
Read our earnings preview for Seadrill Limited: https://www.earningswhispers.com/article/SDRL/21624
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-16 | |
| Oct-12 | |
| Oct-06 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-14 | |
| Jul-09 | |
| Jun-22 | |
| Jun-15 |
