Sprout Social's Cost Cuts Face First Real Test As Rallying Stock Demands More Than Margins
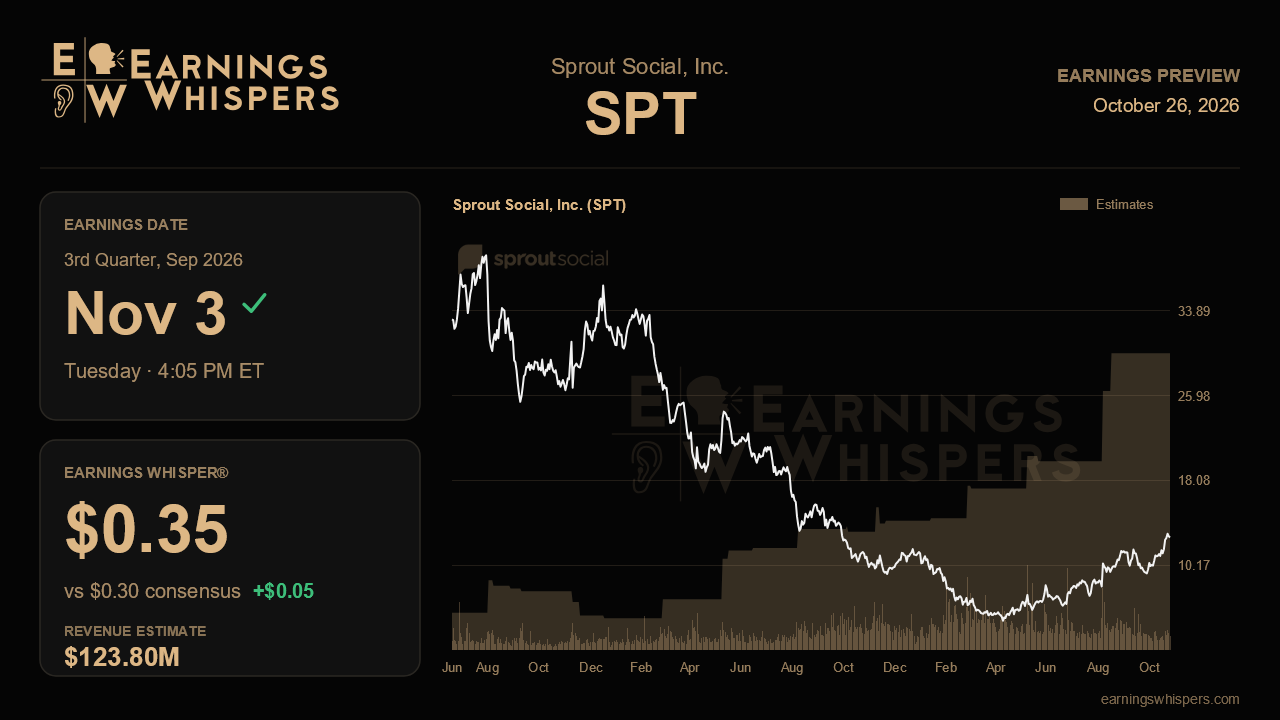
Sprout Social enters its third-quarter report with a story that has changed almost entirely in one quarter. The July restructuring, which removed roughly a fifth of the workforce and should take at least $50 million out of the annual cost base, turned a slow-growth software company into a margin expansion story. The market approved: shares have climbed nearly 33% since the last report while the S&P 500 slipped slightly. The quarter ending in September is the first to show the cuts in the numbers, and it will help settle whether the rally rests on durable improvement or on a one-time reset of expectations.
The Street expects non-GAAP earnings of $0.30 per share on revenue of $123.8 million. That EPS figure sits at the top of management's $0.29 to $0.30 guidance range, so analysts already assume the company will hit its own high end. The Earnings Whisper of $0.35 is meaningfully higher and suggests the more aggressive crowd expects cost savings to show up faster than guided. Revenue consensus falls in the middle of the $123.3 million to $124.1 million range. It implies about 7% year-over-year growth but essentially no change from the second quarter's $123.8 million. That flat sequential line is the heart of the debate.
Last quarter, management raised full-year operating income guidance about 20% at the midpoint and lifted annual EPS guidance to $1.11 to $1.15 from $0.88 to $0.97. It also raised its fourth-quarter exit margin target to about 17% from 15%. Revenue guidance barely moved, though, and it implies fourth-quarter growth of only 3% to 4%. Executives said they assume no improvement in demand. The best validation this quarter would be a non-GAAP operating margin clearly above the second quarter's 12.9%, plus commentary that keeps the 17% exit target on track. Investors should also expect a GAAP restructuring charge of about $18 million to $20 million. That charge is anticipated and should not distort the picture, but any increase in its size or scope would raise questions about how smoothly the reorganization is going.
The growth side carries more risk. Current remaining performance obligations accelerated to 12.4% growth last quarter, but management warned that renewal timing and longer contract durations flattered that figure and that it would moderate in the third quarter. The company also begins lapping the NewsWhip acquisition, which removes a source of inorganic growth. A modest slowdown in CRPO is expected. A sharp one would challenge the bull case. Larger customers matter here too. Net additions of customers paying more than $30,000 a year slowed to 51 from 72. If that slowdown continues, it would suggest the enterprise engine, which grew 20% on a trailing basis, is losing speed. That would happen just as the smaller-customer cohort, about 39% of revenue, is guided slightly negative for the year. Early evidence from Trellis Plus, the paid AI tier launched in July, and from the self-serve Essentials product would help show that growth can stabilize.
Sentiment has cooled even as the stock rallied, with bearish readings rising to roughly 15% from about 3% before the last report. The shares trade far above their 200-day moving average near $8.20 and sit about 4% below the post-earnings high of $13.35. The stock is well above the previous quarter's $5.85 to $9.12 range but has not yet reached a breakout. Free cash flow, up 60% last quarter, and the start of the $50 million buyback offer some support.
The central question is whether Sprout can show margin gains ahead of plan while showing that cost cuts have not weakened the sales engine. A beat on earnings alone is largely expected. Holding the rally probably requires stable revenue guidance and enterprise metrics that stop slowing.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Oct-05 | |
| Sep-16 | |
| Aug-31 | |
| Aug-21 | |
| Aug-19 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-10 | |
| Jul-06 |
