Sprout Social's Margin Surge Drives A Big Beat, But Stalling Bookings And Soft Q4 Revenue Guidance Shift The Story
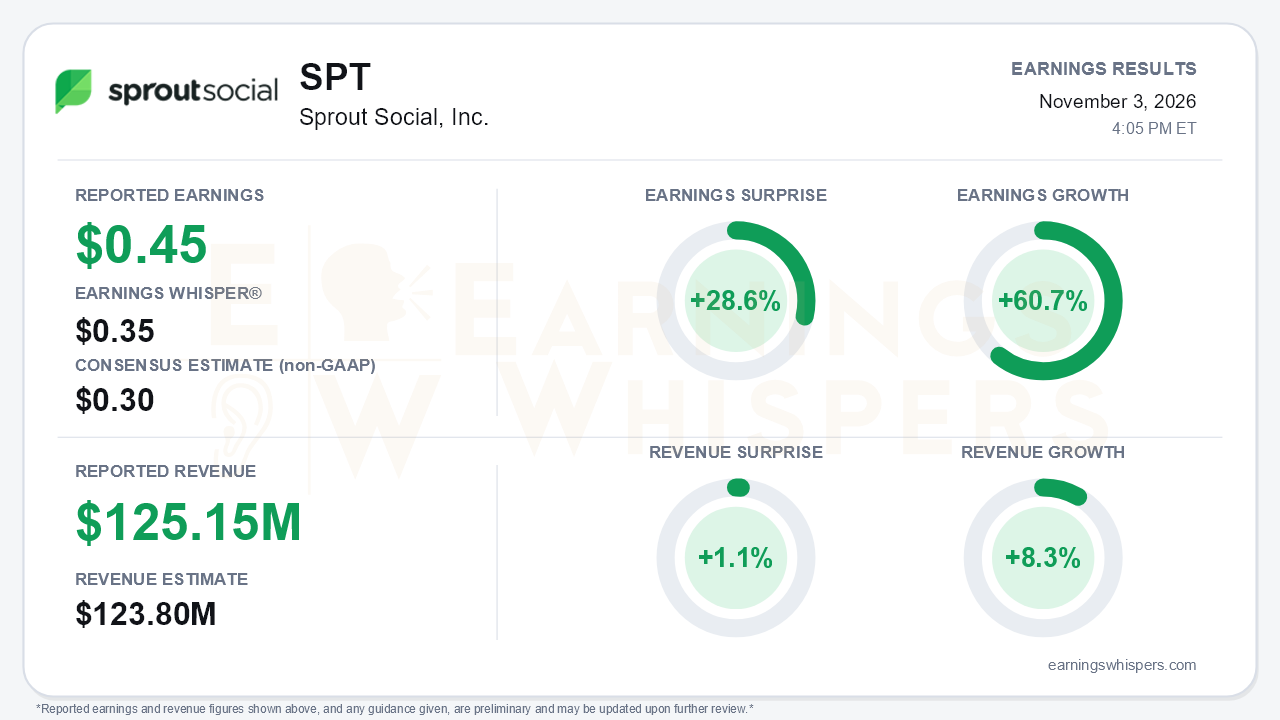
Sprout Social delivered one of its cleanest earnings beats in years, and the quarter also exposed its most important weakness. Non-GAAP EPS of $0.45 topped the $0.30 consensus by 28.6% and cleared the $0.35 Earnings Whisper number. Earnings grew 60.7% year over year. Revenue of $125.15 million beat consensus by 1.1%, but growth slowed to 8.3%, down from 10.8% in Q2, 11.2% in Q1 and 12.9% in Q4 FY25. The guidance note, that Sprout sees revenue below estimates, captures the central tension. This is now a profitability story outrunning a decelerating top line.
The quality of the beat deserves scrutiny. Non-GAAP operating margin reached 21.0%, up from 11.9% a year ago and 12.9% in Q2. That jump came mainly from cost actions, not revenue leverage. The GAAP picture shows how much was excluded. Sprout still posted a GAAP operating loss of $6.9 million, or $0.11 per share, an improvement from a $0.16 loss a year ago. That loss was struck after $17.5 million of restructuring charges, or $0.30 per share, which non-GAAP results exclude. Stock-based compensation fell to $11.4 million from $19.0 million, which genuinely helps the GAAP trajectory. Free cash flow needs similar care. Non-GAAP free cash flow of $26.7 million rose 158%, but it adds back $15.9 million of restructuring payments. Reported operating cash flow was only $10.7 million. Cash fell to $103.7 million from $119.9 million at the end of June, as Sprout spent $26.3 million buying back roughly 2.6 million shares at about $10.25. Deferred revenue also drew down by $8.9 million in the quarter, compared with $2.9 million a year ago.
The call made the deceleration hard to dismiss. Several forward indicators weakened together:
- cRPO growth fell to 8.4% from 12.4% in Q2, and total RPO growth slowed to 10.3% from 15.5%.
- ACV growth eased to 12.1% from 14.8%.
- The count of customers paying $30K or more in ARR fell by one sequentially to 3,925, after adding 72 in Q1 and 51 in Q2. Management said the weakness was concentrated in the $30-50K band.
- Growth in the $50K+ cohort slowed to 11% from 18% earlier in the year.
Management partly attributed the cRPO slowdown to lapping the NewsWhip acquisition and to shorter Q3 contract durations. The tone, however, shifted noticeably from Q2's message that cRPO had accelerated. Management now cites longer sales cycles, more approvers, heavier ROI scrutiny and AI spending crowding out social budgets. The upmarket thesis is not broken. Customers above $150K grew 22%, gross retention was described as stable, and Sprout signed new logos worth roughly $250K and $200K in ARR.
Guidance splits along the same line as the quarter. Full-year non-GAAP operating income guidance rose to $77.8-78.8 million, from $68.3-70.3 million last quarter. EPS guidance rose to $1.29-1.31 from $1.11-1.15. The Q4 exit-margin target moved to about 18% from 17%, and Sprout expects its first GAAP-profitable quarter in Q4, with the goal of sustaining it. Revenue guidance tells a different story. The Q4 range of $124.2-125.2 million implies only about 3-4% growth, and it is flat to down sequentially. Management also warned that variability in Q4 bookings could weigh on the FY2027 trajectory. It acknowledged that progress toward its Rule of 30 target will lean on margin rather than growth. The catalysts are real but early. Trellis is now available on every plan, Trellis Plus has its first buyers, and a pooled-credits option targets large enterprises. None of these is yet visible in the growth rate.
The market setup is more complicated than the surprise implies. Shares ended the pre-report snapshot at $12.09, up 25.8% from the $9.61 open after the August report and 46.6% above the 200-day moving average. The stock rallied from a September 28 low of $8.95 to a 52-week high of $13.35 on October 23. It entered earnings about 9% below that peak, so investors had already rewarded the margin pivot. The Earnings Whispers trend signals were uniformly positive heading into the print, which reflects that price strength. Investor sentiment, by contrast, slipped from -0.03 to -0.12. That is a modest move deeper into negative territory, and it suggests the rally was not accompanied by rising conviction.
The bottom line is that Sprout has proven it can generate earnings. Its margin expansion, rising guidance and approaching GAAP profitability are tangible achievements. Bears still have legitimate ammunition. Revenue growth is heading toward the low single digits, bookings indicators have rolled over, and management has itself flagged risk to 2027. A margin-led story can keep working for a while, but the stock's next leg likely depends on whether Trellis monetization and the enterprise mix can stabilize cRPO and net adds in the $30K+ cohort.
Read our earnings preview for Sprout Social, Inc.: https://www.earningswhispers.com/article/SPT/21631
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-27 | |
| Oct-26 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Oct-05 | |
| Sep-16 | |
| Aug-31 | |
| Aug-21 | |
| Aug-19 |
