Talos Faces Its First Post-Bolt-On Test As Stock Presses Against Highs
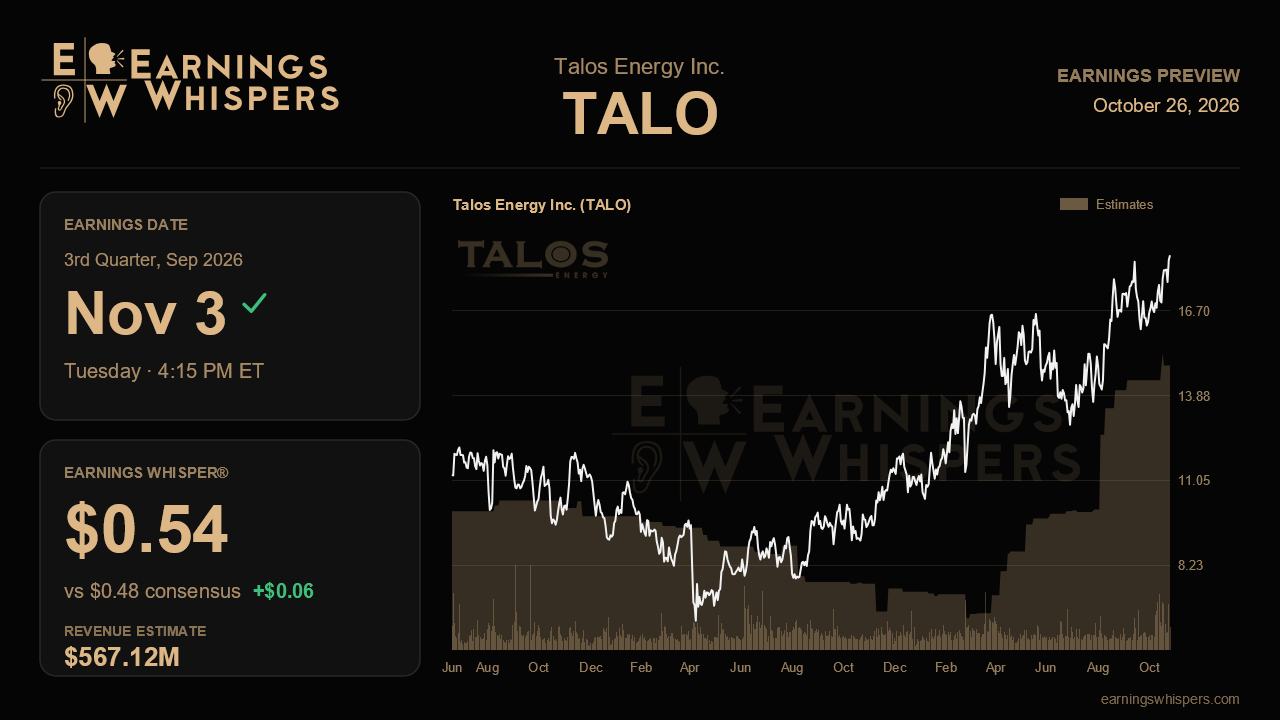
Talos Energy heads into its third-quarter report with a split personality. On paper, the quarter should look softer than the last one: management guided production lower after selling non-core shelf assets, and that guidance excluded the Gulf of America bolt-on that was expected to close during the period. Yet the stock has climbed about 26% since the last report while the S&P 500 slipped, which means the market is already pricing in the bigger, cash-richer company Talos says it is becoming. The release after the close on November 3 needs to show that the sequential dip is optics, not erosion.
Wall Street expects earnings of $0.48 a share on revenue of roughly $567 million. That revenue figure would be about 26% above the year-ago quarter, when Talos lost $0.21 a share, but well below the $665 million booked last quarter. The Earnings Whisper sits at $0.54, above consensus and matching last quarter's result, a sign that the more engaged corner of the market thinks Talos can hold earnings flat despite lower volumes. That is a meaningfully higher bar than the published estimate suggests.
The production guide is the first checkpoint. Management called for oil output of 61,000 to 65,000 barrels a day and total output of 81,000 to 85,000 barrels of oil equivalent per day, down from second-quarter levels of roughly 69,000 and 94,000. Talos beat its own guidance last quarter, and a repeat landing at or above the top of the range would support the claim that the base business is strong enough to more than absorb the divestment. That claim underpinned the full-year standalone raise to 64,000 to 68,000 barrels of oil a day. Results toward the low end would make that raise look stretched, since the second half now has to carry more of the weight.
The second checkpoint is the Coulomb and Nikika acquisition, which adds about 18,000 barrels of oil equivalent per day and was pitched as margin-accretive with roughly 20% oil growth. Confirmation that the deal closed on schedule, along with an updated outlook that folds it in, would be the clearest validation of the expansion narrative. Any delay or integration hiccup would challenge it. Closing also lifts the blackout that halted buybacks last quarter after five straight quarters of repurchases, so a resumption of buybacks, or at least a firm commitment, would signal that growth spending is not crowding out shareholder returns.
Cash generation and costs round out the test. Talos posted record adjusted free cash flow of about $232 million and EBITDA near $402 million last quarter, and had already captured more than two-thirds of its $100 million cost-savings target by midyear. Lower volumes will pressure absolute cash flow, but per-barrel costs and progress toward the full savings goal will reveal whether efficiency gains are durable. Leverage of 0.5x and liquidity near $1.2 billion give management room, but early spending on Mexico's Block 29, the Honduras seismic program and the Daenerys appraisal will show how much of the free cash flow is being redirected toward longer-dated, less proven bets.
Sentiment has drifted more bearish than it was ahead of the last report, even as the stock trades about 25% above its 200-day moving average and within 1% of its post-earnings high near $18.73. That mix suggests a crowd that has bought the story but is uneasy about paying up for it. The question this report must answer is simple: did the base business beat a lowered production guide while the bolt-on closed cleanly? If so, the pro forma momentum story holds. If not, a stock near its highs leaves little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Sep-25 | |
| Sep-23 | |
| Sep-23 | |
| Sep-23 | |
| Sep-22 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-27 | |
| Jul-15 | |
| Jul-14 |
