Talos Energy Beats On Production And Raises Guidance Again, But Slower Free Cash Flow And Project Delays Temper The Quarter
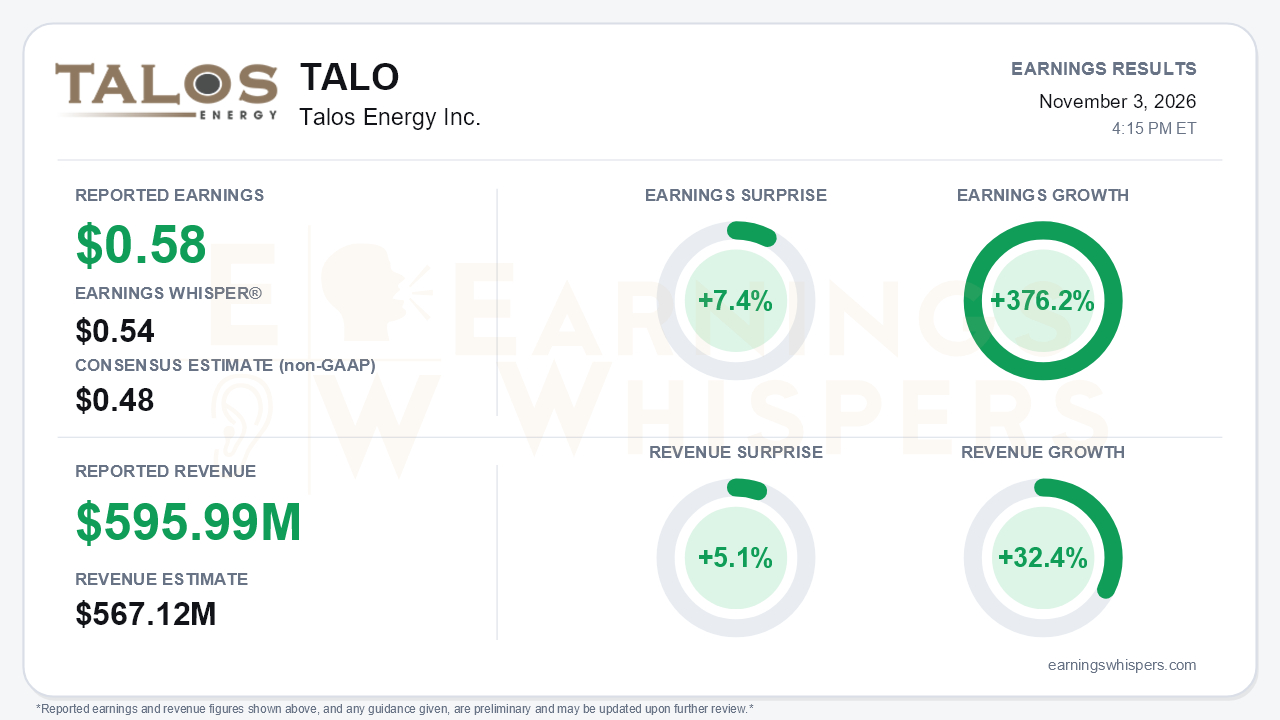
Talos Energy delivered the kind of operational quarter that offshore bulls have been waiting for. Adjusted earnings came in at $0.58 per share, ahead of the $0.48 consensus and the $0.54 Earnings Whisper number, a 7.4% beat. Revenue of $595.99 million topped the $567.12 million consensus by 5.1%. Year over year, earnings grew 376.2% and revenue grew 32.4%, driven by a near-37% jump in oil revenue to $549.8 million. The quarter also produced a second straight guidance raise and an acquisition that closed below its expected cost. The central tension is that the headline strength sits alongside several softer underlying signals: free cash flow came off its peak, the balance sheet absorbed the deal, and two of the company's most-watched growth projects moved further out.
The quality of the beat deserves some scrutiny on two fronts. First, the adjusted figure diverges sharply from GAAP. Talos posted a net loss of $81.2 million, or $0.49 per share, only modestly better than the $0.55 loss a year ago. The gap reflects a $120.6 million derivative mark-to-market loss, a $37.4 million loss on debt extinguishment and $47.1 million of non-cash tax expense. Those are largely non-operating items, but they are not trivial. Second, hedges are now a real drag. Realized hedge settlements cost $29.8 million, and unhedged Adjusted EBITDA per BOE fell to $51.80 from $55.85 in the second quarter. Hedged Adjusted EBITDA of $406.1 million was essentially flat against Q2's $402.2 million, even though volumes beat.
Volumes are the cleanest part of the story. Third-quarter production of 68.5 MBo/d and 91.5 MBoe/d cleared guidance of 61-65 MBo/d and 81-85 MBoe/d. Management said the base business ran at the high end of guidance even before counting the absence of storm downtime and the roughly one week of contribution from the Shell assets. Full-year guidance now stands at 68-70 MBo/d and 92.5-94.5 MBoe/d, up from 64-68 MBo/d in August. The oil midpoint is about 8% above the original February guide, and that is after absorbing a shelf divestment and roughly 7 MBoe/d of fourth-quarter Hurricane Isaias downtime. The $100 million Optimal Performance Plan target was fully achieved by quarter-end, having stood at more than two-thirds complete in Q2. CPN reached first oil, and Brutus started drilling with an expanded five-well program. Management described the portfolio as deeper than Talos has ever had.
The weaker spots are genuine. Adjusted free cash flow slipped to $186.3 million from a record $232 million in Q2. Cash fell from about $578 million to $410 million after funding the $420 million deal, and leverage edged up from 0.5x to 0.6x. Lease operating expense rose to $16.74/BOE, P&A guidance rose to $135-145 million as work was pulled forward, and the capex midpoint was trimmed, leaving combined spending unchanged. More consequential for the growth narrative, Monument first oil has now slipped from "late 2026" to the first quarter of 2027 after the operator redeployed its rig. Daenerys has also been reframed as a multi-year appraisal requiring a 2027 sidetrack, with 2029 first oil called "highly unlikely." Investors should also note that the oil collars carry ceilings near $77-78 through mid-2027, below the $87.19 realized oil price this quarter. That structure limits upside capture if crude stays elevated.
Market positioning has not fully embraced the operational progress. Earnings Whispers investor sentiment stayed negative and weakened slightly, moving from -0.19 to -0.24. That is a modest deterioration rather than a capitulation. Shares, meanwhile, have gained 9.6% since the open following the August report and sit at $16.10, about 7.1% above the 200-day moving average of $15.03. The Earnings Whispers trend signals are mostly positive, with sequential growth neutral, consistent with a stock that has been grinding higher while investors stay unconvinced. That mix gives the market setup more nuance than the beat implies: the price reflects improving execution, but sentiment suggests skepticism about durability, project timing and commodity exposure.
The bottom line is that Talos delivered a credible quarter on what it controls: production, costs, deal execution and guidance. The acquisition adds oil-weighted scale without stretching the balance sheet. Bears still have legitimate ammunition, however. GAAP results remain in the red, hedges are eroding realized margins, free cash flow is off its peak, and the 2027 growth cadence now leans more heavily on Monument and Brutus delivering on revised timelines. The next few quarters will test whether integration and project execution can turn record production into sustained cash flow growth.
Read our earnings preview for Talos Energy Inc.: https://www.earningswhispers.com/article/TALO/21636
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-26 | |
| Oct-23 | |
| Sep-25 | |
| Sep-23 | |
| Sep-23 | |
| Sep-23 | |
| Sep-22 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 |
