Carter's Must Prove Tariff-Driven Margin Rebound Can Outrun Wholesale Slump And Price Resistance
Carter's heads into its third-quarter report with an unusual split personality. Profits are set to rise for a second straight quarter after a bruising 2025, yet sales are expected to shrink. Investors have sold first and asked questions later. The question now is whether the earnings recovery management sketched in July is real operating progress or mostly the arithmetic of lapping last year's tariff shock.
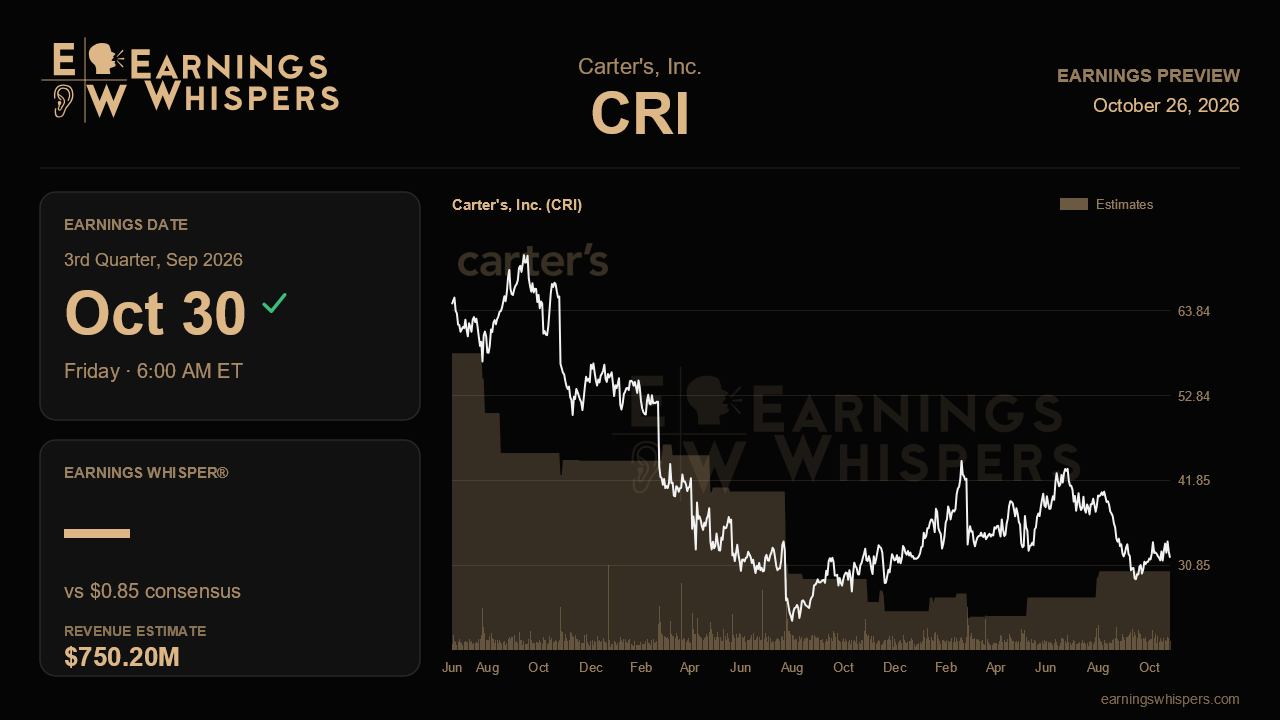
Wall Street expects adjusted earnings of $0.85 a share on revenue of about $750.2 million. That would be roughly 15% EPS growth from $0.74 a year ago on sales down about 1%. Those figures sit essentially on top of management's own third-quarter outlook of about $0.85 and $750 million. Analysts have simply adopted the company's numbers, and that matters. Before the guide, the Street was looking for $0.77 on nearly $790 million in sales, so expectations were reset to lower revenue but higher profit. For the full year, Carter's narrowed its range to $3.04 to $3.21 in EPS on $2.96 billion to $2.99 billion in revenue. The top end of that sales range now sits below where analysts had been.
The profit story rests on gross margin. Management guided to roughly 200 basis points of expansion in the quarter as last year's tariff costs roll off, with operating income climbing to about $50 million from $39 million. That is the piece most likely to be validated, since it is largely mechanical. A shift from the expired Section 122 tariffs to lower Section 301 rates offers some potential cushion. The harder test is whether merchandise margins hold up. In the second quarter, heavier-than-planned clearance of soft seasonal goods shaved about 80 basis points off gross margin versus the company's plan. Management also tempered its second-half assumptions for average unit retail, citing price resistance and slower unit velocity across the market. If clearance activity repeated in the fall season, the 200-basis-point target could slip even with tariff relief in hand.
On the top line, the company has already warned that wholesale will fall by a high-single-digit rate. Part of that reflects fall product shipped early into the second quarter, but some customers are also committing to inventory more cautiously. A decline in line with guidance would be tolerable. A steeper drop would suggest the caution is about end demand rather than timing. U.S. retail is the counterweight, with five straight quarters of positive comparable sales and double-digit e-commerce growth. Store traffic, however, was only flat in the second quarter. A sixth positive comp achieved without leaning on deeper promotions would go a long way toward supporting the new chief executive's more confident tone. A comp that turns negative as pricing softens would undercut it.
Sentiment has cooled sharply. Readings have moved from modestly bullish before the last report to slightly bearish now. The stock has fallen about 16.5% since July while the S&P 500 gained nearly 3%. At $31.81, shares trade well below their 200-day moving average of $36.32 and closer to the post-earnings low of $28.86 than the $41.26 high. In effect, the market has discounted the earnings beat and the windfall tariff refund that pushed cash above $650 million. It has focused instead on the trimmed sales outlook and a more value-conscious consumer.
That skepticism lowers the bar for relief, but only if the details cooperate. Matching $0.85 is largely baked in. What will decide the narrative is whether Carter's can deliver margin expansion that comes from cleaner inventory and stable pricing, not just tariff anniversaries, while showing that wholesale weakness is a timing issue rather than a retreat by its partners. Holding the full-year range would help, as would early strategic detail from Sharon Price-John. The central issue is whether profitability can recover without the sales base continuing to erode beneath it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Sep-24 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-02 | |
| Aug-26 | |
| Aug-20 | |
| Jul-31 | |
| Jul-31 |
