Carter's Margin-Driven Beat Collides With A Second Straight Sales Guidance Cut
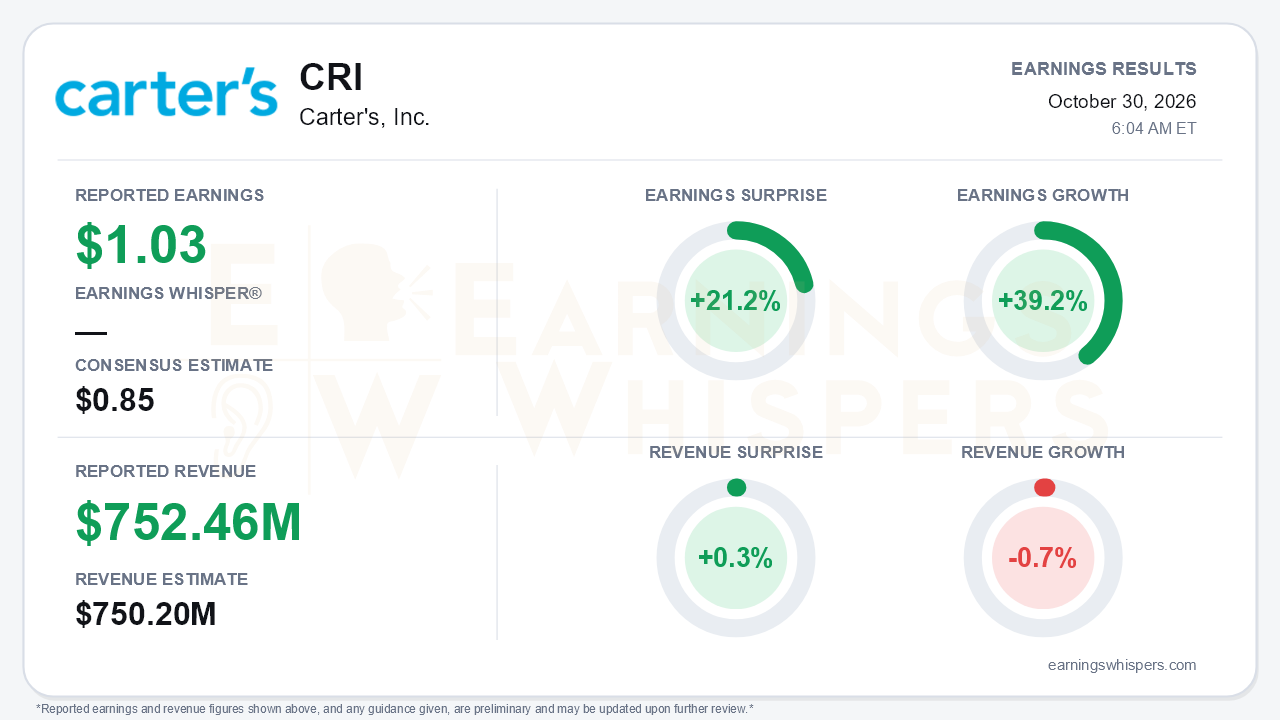
Carter's delivered a clean profit beat in the third quarter, but it came with a top-line warning that weighs more heavily on the investment debate. Adjusted EPS of $1.03 topped the $0.85 consensus by 21.2% and grew 39.2% year over year. GAAP EPS rose to $1.00 from $0.32, helped by the absence of last year's restructuring, consulting and pension charges. Revenue of $752.46 million edged past the $750.2 million estimate by 0.3% but fell 0.7% from a year ago. That is the central tension. Margins are working, while demand is fading quarter by quarter, and management cut its sales outlook again.
The beat was real at the operating level and was not a product of adjustments. Only $1.2 million of IP litigation costs separated GAAP from adjusted operating income this quarter. Adjusted gross margin reached 47.1%, up 200 basis points, a sharp reversal from declines of roughly 180 basis points in Q2 and about 300 basis points in Q1. Adjusted operating income rose 45% to $57 million, against roughly $50 million guided in Q2, for a 7.6% margin versus 5.2% a year earlier. Every segment expanded margin:
- U.S. Retail operating profit nearly doubled, with margin rising to 5.3% from 2.8%.
- Wholesale margin climbed to 17.8%.
- International reached 10.0%.
The quality of the beat still deserves scrutiny. The company credited higher realized pricing and productivity, but units fell mid-single digits. Carter's is earning more on less volume, which is a less durable formula if the consumer keeps weakening.
The revenue trajectory is the problem. U.S. Retail comparable sales slowed from +10% in Q1 to +5% in Q2 to just +0.4% in Q3. U.S. Wholesale sales fell 3.8%, and the replenishment forecast was trimmed; full-year wholesale is now expected flat to slightly down. International was the one growth engine, up 4.5% (3.6% in constant currency). The call offered encouraging data points:
- September comps rose double digits after the first Carter's brand reimagination in 25 years.
- Sleepwear grew double digits on the Stellar Sleep launch.
- Baby logged its eighth straight quarter of comp growth.
Those bright spots were quickly offset. Quarter-to-date Q4 retail comps are negative, and management said it will no longer disclose intra-quarter comps. That decision will not reassure investors trying to judge whether the September lift was durable.
Guidance is where bears have legitimate ammunition. Full-year sales are now projected at $2.91 billion to $2.93 billion, about 1% growth. That compares with 2-3% guided in Q2 and low-to-mid single digits earlier in the year. Q4 sales of $860 million to $880 million imply a mid-single-digit decline against a $925 million, 14-week prior-year quarter. Q4 adjusted EPS of $1.37 to $1.55 compares with $1.90 a year ago, and Earnings Whispers characterizes the outlook as below estimates. The full-year adjusted operating income growth range (low-to-mid single digits) and the projected EPS decline (high single digits to low double digits) were maintained. The call analysis indicates lower tariffs helped hold that line. Management flagged meaningful headwinds:
- softening store traffic tied to gas prices and inflation;
- election-year media costs;
- an aggressive holiday promotional environment as competitors reinvest tariff relief into price;
- cotton up about 20%;
- $4-5 million in freight surcharges;
- port congestion;
- product cost inflation into the second half of 2027.
The balance sheet and cash flow offer genuine support. Year-to-date operating cash flow was $101.8 million, versus a $136.3 million outflow last year, aided by a $128 million tariff refund and better working capital. The full-year operating cash flow outlook rose again to $240-250 million. Inventory was down 11%, and cash plus short-term investments totaled roughly $526 million. Strategically, CEO Sharon Price John is reshaping leadership: a Chief Commercial Officer, an incoming Chief Product Officer from H&M, and a COO search. She also outlined a market-expansion framework. Spring 2027 pre-ships are up about 30%, and a full strategic plan is due after the new year.
Investor sentiment had already soured heading into the print, swinging from a modestly positive 0.21 after the prior report to -0.22. That is a meaningful shift from optimism to skepticism. Shares closed at $33.38 before the release, down 12.4% from the open after the July report. They sat about 8% below the 200-day moving average and 19% below the inter-earnings high of $41.26 set August 3. The stock had recovered about 16% off its September 15 low of $28.86, so the market entered the report already discounting weaker demand. It had not discounted a deterioration this persistent.
The bottom line is that Carter's proved it can expand margins sharply even as volumes shrink, and its cash generation is markedly stronger than a year ago. However, a third straight quarter of comp deceleration, negative Q4-to-date trends, reduced disclosure and a second consecutive sales guidance cut mean the growth story now rests on a strategic plan investors have yet to see. Until the brand relaunch translates into sustained traffic, the beat reads more as cost discipline than as a turn in demand.
Read our earnings preview for Carter's, Inc.: https://www.earningswhispers.com/article/CRI/21650
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-30 | |
| Oct-26 | |
| Oct-26 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Sep-24 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-02 |
