USANA Needs Steady China Core To Offset Venture Brand Damage After Guidance Cut
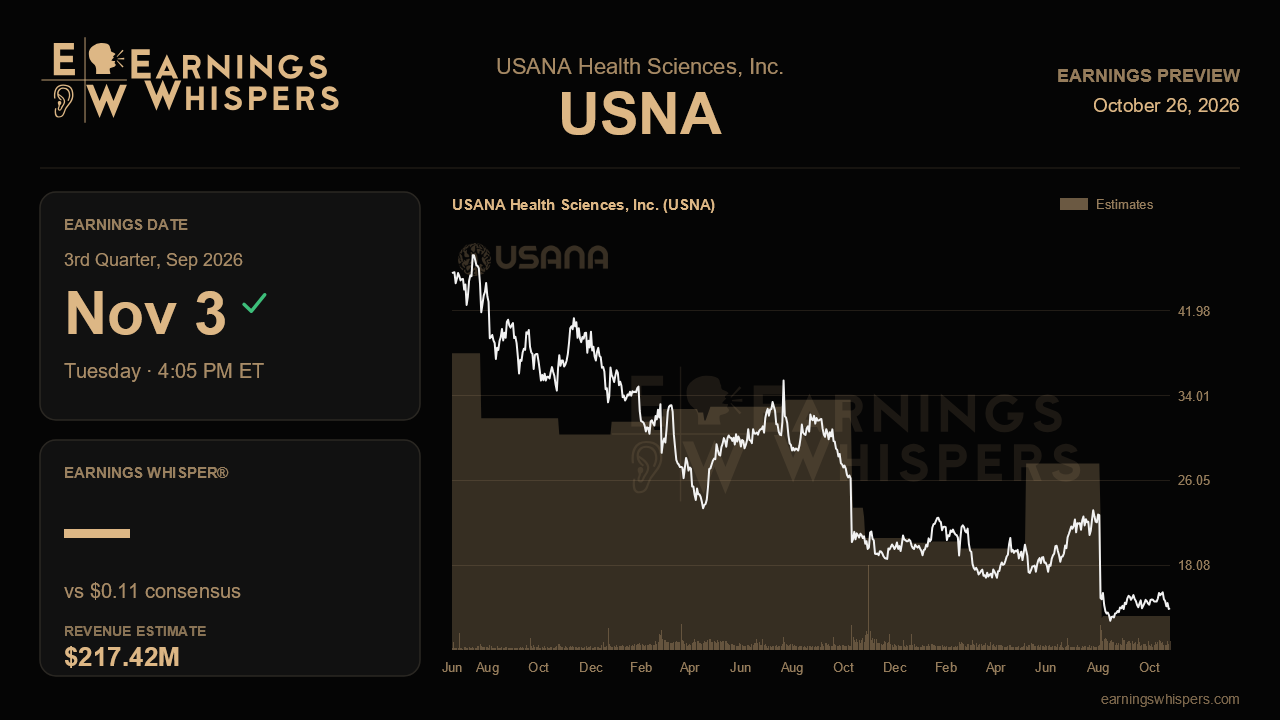
USANA heads into its third-quarter report with a credibility problem that has little to do with its oldest business. Last quarter, the network marketing nutrition company slashed its full-year outlook, wrote down $29 million of goodwill tied to its Hiya (HIA) children's vitamin unit and posted a loss. This came after management spent three quarters framing the venture brands as the growth engine of an omnichannel transformation. The core direct selling business, meanwhile, was quietly stabilizing. This report is the first real chance to see whether the reset was a one-time clearing event or the start of something worse.
The bar for the quarter itself is modest. Analysts expect earnings of $0.11 per share on revenue of $217.4 million. That would be a swing to profit from a $0.15 loss a year ago, which is where the eye-catching 173% growth figure comes from. Revenue would be up only 1.8% from last year and slightly below the $223.3 million posted last quarter. The more telling comparison is with the annual numbers. Management now targets roughly $0.76 per share on about $910 million of revenue, down sharply from its prior range of $1.95 to $2.29 on $925 million to $1.0 billion. Yet the full-year consensus still sits around $2.12 on $945 million, far above the company's own outlook. Some of that gap may reflect estimates that have not been updated, or differences in how the impairment is treated. Either way, the quarterly print and any reaffirmation of the new outlook will shape where full-year estimates settle.
Operationally, the story splits in two. The core nutritional business is where the good news lives. China showed renewed strength in the second quarter, helped by a strong first-quarter incentive and product launches, and management pointed to improved leadership there. Confirmation would come from steady China customer counts without a fresh incentive doing the heavy lifting. Early traction from the Glow skin-health supplement, Korea's new market-specific product packs and any lift following the August Americas Convention would also help. Sequential softness in China would undercut the one segment that is supposed to carry the year.
The venture brands are the bigger swing factor. HIA is fighting a costlier, less predictable Meta advertising environment that management first flagged a year ago and that has not gone away. The company is shifting spending toward TikTok, influencers, Amazon and retail. Subscriber trends and customer acquisition costs will show whether that diversification is working or simply moving the expense elsewhere. Rise Wellness needs to show the packaging problem is fixed, that shipments have resumed and that it remains on track for more than 4,000 retail doors by year end, aided by the new Protein Pop product. The elevated tax rate also matters. It made last quarter's loss look worse, and it will keep distorting results as long as venture losses sit in the wrong jurisdictions.
The market has already passed judgment. Shares are down 23% since the last report, against a 1.4% dip in the S&P 500, and at $14.04 they sit well below the 200-day moving average of $18.23. The stock is nearer the bottom of its post-earnings range of $12.57 to $18.24, a band that sits entirely below the prior quarter's $16.91 to $23.59. Sentiment has improved from distinctly bearish heading into the last report to roughly neutral. That suggests the sellers may be tiring rather than buyers returning in force. Strong free cash flow and a debt-free balance sheet with $169 million in cash give the company room to work through its problems.
The core question is whether the lowered guidance was the floor. If China holds up, HIA's marketing costs stabilize and Rise is back on shelves, management can argue the second-quarter damage was about timing, not the strategy. Another cut, or more venture-related charges, would suggest the omnichannel bet is costing more than the core business can absorb.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-12 | |
| Oct-07 | |
| Oct-01 | |
| Sep-03 | |
| Sep-01 | |
| Aug-17 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-20 | |
| Jul-14 | |
| Jul-01 |
