USANA Misses And Cuts Guidance Again As Hiya's Subscriber Rebound Collides With A Shrinking Core Customer Base
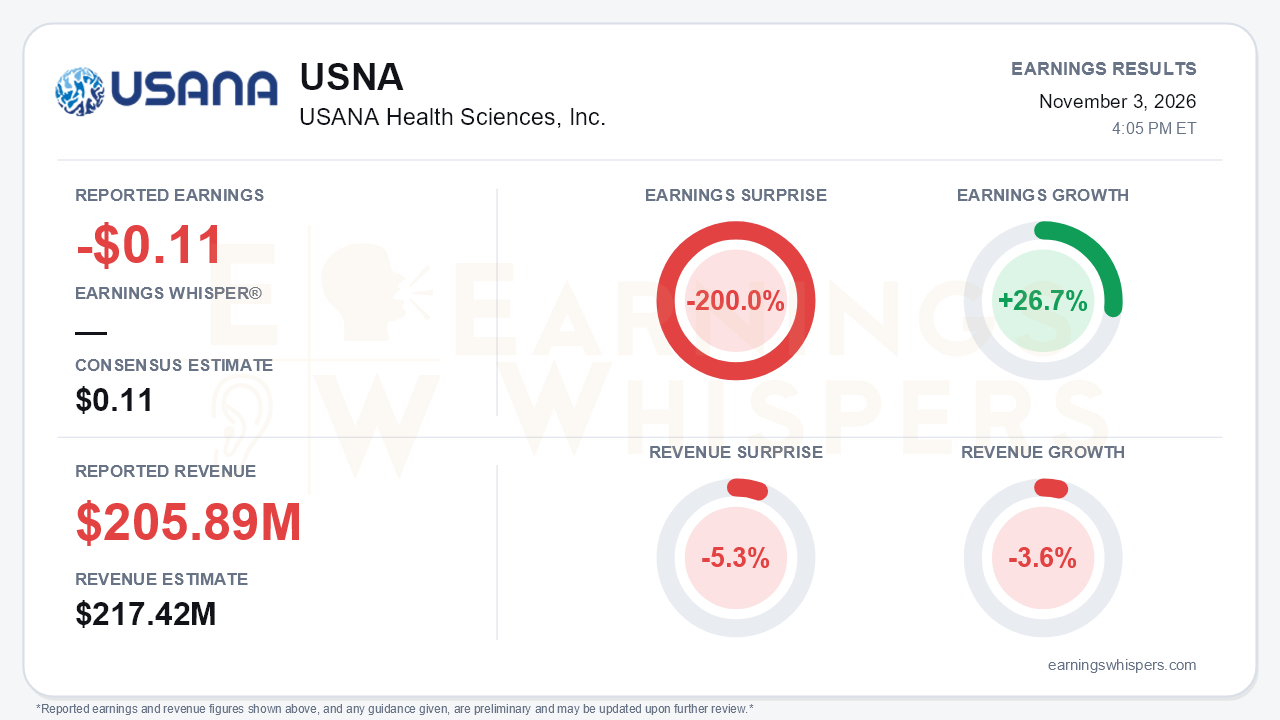
USANA Health Sciences delivered a clear miss and a second consecutive guidance cut. The adjusted loss of $0.11 per share fell well short of the consensus estimate for a $0.11 profit, a 200.0% negative surprise. Revenue of $205.89 million missed the $217.42 million consensus by 5.3% and declined 3.6% year over year. On paper, earnings improved 26.7% from a year ago because the adjusted loss narrowed from $0.15, and the GAAP loss narrowed to $0.30 from $0.36. That comparison flatters a quarter in which the operating picture weakened. The central tension is that management is spending to revive Hiya just as the core direct-selling franchise, which still generates 83% of sales, keeps losing customers.
The quality of the quarter deserves scrutiny. Currency added roughly 2 points to sales, so the constant-currency decline was 5.6%. Adjusted EBITDA attributable to USANA fell 13% year over year to $12.1 million and dropped 44% sequentially. The company also posted a GAAP operating loss of $1.4 million versus a small profit a year ago. Taxes made the bottom line worse: $6.1 million of income tax expense landed on a pretax loss of just $0.8 million, and the call flagged the elevated rate as persistent. Credibility took a hit as well. USANA disclosed that its second-quarter adjusted EBITDA had been overstated by $6.2 million because the Hiya goodwill impairment was added back without netting out the noncontrolling interest. As a result, the prior full-year EBITDA outlook of roughly $87 million was really $80.5 million. The new $77 million target therefore represents a deeper retreat from what investors were originally shown. Adjusted EPS guidance fell to $0.55 from $0.76. Consolidated sales are now guided to "approaching $900 million," well below the original $925 million to $1 billion range.
Beneath the headline, the segments are moving in opposite directions.
- **Core Nutritional:** Sales fell 3% (6% in constant currency) and 11% sequentially. Active customers declined 8% year over year to 356,000 and 7% from the prior quarter. Greater China drove most of the sequential deterioration, with sales down 18% and active customers down 11% from the second quarter. That is a sharp reversal from the "renewed strength" management described last quarter. Every region except Southeast Asia Pacific declined in constant currency. Southeast Asia Pacific was the lone bright spot, swinging to 2% growth from a 13% decline in the second quarter, with active customers up 3% sequentially. To management's credit, core operating margin improved to 4.1% from 1.2% on lower incentive, event and compensation costs. That margin gain came from a leaner cost structure, not from demand.
- **Hiya:** The subsidiary is the genuine catalyst. Active monthly subscribers jumped 18% sequentially to 195,500, about 29,500 net additions. Sales grew 12% sequentially and returned to year-over-year growth. Target and Amazon sales more than doubled from the second quarter, though from a small base. Hiya also launched TikTok Shops and creator programs that reduce its dependence on Meta, and it enters the club channel in early 2027. The cost was steep. Hiya's operating margin fell to -20.1% from -2.1% as SG&A climbed to 86% of sales. Management raised Hiya's full-year sales outlook to $130 million and expects sequential improvement in both sales and EBITDA in the fourth quarter. Still, that target sits far below the $140 million to $155 million originally guided.
- **Rise Wellness:** This remains a problem. Sales dropped 45%, gross margin turned negative at -10.4%, and club orders again missed expectations. Management lowered the outlook a second time and warned that fourth-quarter retail orders could slip into 2027.
The call's tone shifted noticeably. Management moved from confident transformation messaging to candidly calling the quarter "mixed" and saying it was not satisfied with Rise and the core business. The fixes for the core business are real but slow. They include phased incentive-plan changes aimed at customer loyalty and retention rolling out through 2027, more digital brand marketing, and women's and kids' product launches next year. None of these is likely to help the fourth quarter.
The balance sheet buys time. Free cash flow reached $8 million in the quarter and $36 million year to date, more than double last year. Inventory fell 13% from year-end, and cash rose to $179 million with no debt. No shares were repurchased, leaving $34 million on the authorization.
Investor sentiment improved substantially heading into the report, rising from -0.51 to slightly positive at 0.06. That shift looks poorly aligned with a miss and another guidance reduction. The stock tells a less forgiving story. At $14.87, shares are down 18.5% since opening after the August report and sit 17.6% below the 200-day moving average of $18.06. The Earnings Whispers trend signals remain mostly negative, with price, momentum and AVWAP readings all pointing lower.
The bottom line is that USANA's quarter offered one credible growth thread in Hiya's subscriber recovery, along with strong cash generation. Both were overshadowed by a shrinking core customer base, a faltering Rise, a corrected non-GAAP baseline and a guidance cut on nearly every line. Bears have legitimate ammunition until Core Nutritional active customers stabilize outside Southeast Asia Pacific.
Read our earnings preview for USANA Health Sciences, Inc.: https://www.earningswhispers.com/article/USNA/21644
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Oct-12 | |
| Oct-07 | |
| Oct-01 | |
| Sep-03 | |
| Sep-01 | |
| Aug-17 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 |
